For recent commercial property buyers, qualified improvement property depreciation generally means a 15-year recovery period for eligible interior improvements to an existing nonresidential building, according to the Internal Revenue Service. Qualified property acquired after January 19, 2025, may qualify for 100% bonus depreciation under IRC §168(k), subject to the applicable requirements.
The rules can be confusing, especially when a project combines renovations with an expansion or includes work on the building’s core and shell. This article explains what counts as qualified improvement property (QIP), how the recovery period and bonus depreciation interact, and which commercial improvement eligibility tests matter. It also traces how the category developed, so you can understand why the current treatment differs from the rules that initially applied after 2017.
Key Takeaways
- Check whether the work improves the interior of an existing nonresidential building; expansions and certain structural components fall outside the QIP definition.
- According to the Internal Revenue Service, eligible QIP generally has a 15-year recovery period, while the applicable depreciation method and system affect how deductions are claimed.
- Bonus depreciation depends on the property’s acquisition date; eligible property acquired after January 19, 2025, may qualify for a 100% allowance.
- Bring project descriptions, invoices, and acquisition and in-service dates to your CPA to discuss classification, depreciation treatment, and whether a cost segregation analysis may help distinguish asset types.
Who Qualified Improvement Property Depreciation Applies To, and Who It Doesn’t
Recent commercial property buyers and existing-building owners may claim QIP treatment for eligible interior work they make to a nonresidential building already in service. Under IRC §168(e)(6), the improvement must be made by the taxpayer; buying a property doesn’t turn a previous owner’s improvements into the buyer’s QIP.
Tenant improvements may qualify when the building’s core and shell were already placed in service before the tenant leases the space. The sequence of the project and who is responsible for the work matter, not just how the space is used.
QIP treatment generally doesn’t apply to residential facilities, work in a newly constructed building, or improvements made by a previous owner. Building enlargement, elevators or escalators, and the internal structural framework are excluded. Mixed-use property has an additional test: it’s treated as residential for this purpose if more than 80% of its income comes from residential sources. These limits help separate potentially eligible renovations from work that belongs to another property category.
What Is Qualified Improvement Property and Its Depreciation?
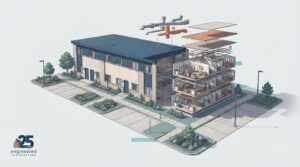
QIP is work the taxpayer makes to the interior of a building already in service. The building must be nonresidential. IRC §168(e)(6) excludes building enlargements, elevators, escalators, and the internal structural framework. Interior retail work may qualify, but adding floor area does not.
According to the Internal Revenue Service, QIP is depreciated over a 15-year recovery period for U.S. tax purposes. Under ADS, its recovery period is 20 years. By comparison, a building generally follows a 39-year recovery period. The applicable depreciation system affects the schedule used for tax accounting.
A project may combine renovation work and excluded additions, so classify costs by component. Does QIP qualify for Section 179 expensing? Yes. Under IRC §179(e), QIP may be treated as qualified real property eligible for a Section 179 election, subject to the rules governing that election.
Eligibility Tests for Commercial Building Improvements
QIP must improve the interior of an existing nonresidential building already in service. Interior ductwork and controls may qualify; external rooftop units do not.
Eligibility Requirements
Under IRC §168(e)(6), the taxpayer must make the improvement to the building’s interior. This test ties eligibility to the taxpayer’s work and the building’s existing use.
Eligible Interior Improvements
Interior systems such as ductwork and controls may qualify when they improve existing commercial space. In a retail renovation, assess each component separately: the project label alone does not establish eligibility.
Excluded Improvements
Building enlargements, elevators, escalators, and the building’s internal structural framework are excluded. New-construction work and improvements made by a previous owner also do not qualify as QIP.
Property Eligible for Depreciation
Depreciable property generally must be owned and used in a business or income-producing activity, with a determinable useful life exceeding one year. Land itself is not depreciable. When classifying costs, distinguish eligible building components from land and excluded structural work.
Qualified Leasehold Improvement Property History
Before QIP, IRC §168 provided favorable tax treatment for qualified leasehold improvement property from 2001 through 2017. The PATH Act of 2015 established QIP as a building-improvement category. Then the Tax Cuts and Jobs Act, passed in 2017, consolidated qualified leasehold, retail, and restaurant improvement categories into QIP. That shift changed the definition investors and tax preparers used to classify improvement assets.
The transition initially left QIP with a 39-year recovery period, rather than the intended shorter period. The CARES Act of 2020 corrected that treatment retroactively: QIP placed in service in 2018 and 2019 could receive a 15-year recovery period.
How did the CARES Act correct the QIP depreciation rules? It assigned qualifying improvements the 15-year recovery period retroactively for those years. Revenue Procedure 2020-25 provided a process for claiming missed depreciation on QIP placed in service during 2018-2020. The takeaway: for older projects, the placed-in-service year and prior accounting treatment can affect whether depreciation was correctly reported.
What Is the Rate of Bonus Depreciation on QIP?
IRC §168(k) bonus depreciation depends on eligibility and acquisition timing. QIP must meet the applicable property requirements.
Bonus Depreciation Eligibility and Timing
Under the One Big Beautiful Bill Act, timing can change the allowance. Eligible property acquired after January 19, 2025, may qualify for a 100% special depreciation allowance, subject to applicable requirements. Excluded structural components, including the internal structural framework, don’t become eligible through this rule.
Rates by Placed-in-Service Year
According to the Internal Revenue Service, qualified property acquired on or before January 19, 2025, and placed in service in 2025 receives a 40% allowance, or 60% for long production period property and certain aircraft. The 100% test depends on the acquisition date. If you elect out, QIP generally uses a 15-year recovery period under GDS or 20 years under ADS; ADS property isn’t bonus-eligible.
Use the return’s depreciation form and retain invoices, plans, contracts, cost allocations, and records showing when the property was placed in service. Establish the date using project-completion and use documentation, and determine basis from eligible improvement costs. Common errors include treating structural work as QIP or using the wrong placed-in-service date. Keep records at the component level to support each classification.
How Qualified Improvement Property Depreciation Works
Qualified improvement property depreciation starts with classifying project costs, then applying the relevant recovery period or bonus allowance. The placed-in-service date and acquisition timing affect the available treatment.
According to the Internal Revenue Service, qualified property acquired after January 19, 2025, may receive a 100% special depreciation allowance under the One Big Beautiful Bill Act. This illustrates the allowance, not a guaranteed result for every renovation.
If the taxpayer elects out of bonus depreciation, eligible QIP generally uses the 15-year GDS recovery period and straight-line method. The project’s invoices, plans, and cost allocations help distinguish QIP from excluded structural work. The deduction applies to eligible improvement costs, not automatically to every cost associated with a commercial renovation. Have your CPA align the asset classification and tax treatment with the project records.
Common Mistakes About Qualified Improvement Property Depreciation
A common mistake is treating an entire project as one asset instead of separating its components. Three distinctions can help prevent misclassification.
- Assuming every renovation qualifies: QIP covers eligible interior improvements, not building enlargements or the internal structural framework. A renovation that also adds floor area needs separate cost classifications for each portion.
- Using the wrong recovery period: The CARES Act corrected the treatment of qualifying improvements placed in service in 2018 and 2019. If QIP was instead depreciated over 39 years, ask your CPA whether Form 3115 and a Section 481(a) adjustment can address missed depreciation.
- Confusing acquisition and service dates: For 100% bonus depreciation under the One Big Beautiful Bill Act, eligible property must be acquired after January 19, 2025. One date alone doesn’t meet the timing condition.
Keep contracts, invoices, and completion records alongside the asset classifications supporting the tax return.
Questions to Ask Your CPA
Bring the project scope, construction invoices, plans, contracts, and completion records to your meeting with your CPA. These documents can help connect the physical work to the tax positions reported for the property.
- Which project components meet the QIP definition, and how will excluded structural work or additions be classified?
- How do the acquisition date and placed-in-service date affect the depreciation treatment for each eligible component?
- Which depreciation system and elections apply to this property, and how will they affect the deductions reported?
- If prior returns used a different recovery period, should we consider an accounting-method change for the affected assets?
Ask your CPA to explain the basis for each classification and how the supporting documents align with the return. Clear explanations can help you understand the treatment and identify project details that need further discussion.
Engineered Tax Services
Engineered Tax Services combines engineering analysis with tax expertise to help commercial property owners assess complex building costs. Its Cost Segregation studies can clarify how physical assets fit different tax classifications and provide technical findings for discussion with your CPA. This is particularly useful when project records describe work broadly, but the tax treatment depends on the components installed.
A cost segregation study can analyze building components and separate costs among asset categories. It complements, rather than replaces, the QIP analysis: each improvement still needs to be assessed under its own statutory definition and project facts.
When working with your CPA, focus on aligning the engineering findings with project documentation and the tax positions under consideration. Plans, invoices, and descriptions of completed work help connect the physical improvements to the analysis.
Prepare Your Property Records for the Next Tax Discussion
A useful next step is to connect the construction record with the tax return. Gather the scope of work, invoices, plans, contracts, and completion details so your CPA can see how the project developed, not just its final cost.
That record can also support consistent decisions in the future. If the property is sold, refinanced, or improved again, clear asset classifications give your advisors a stronger starting point for evaluating its tax history. Qualified improvement property depreciation is one part of that record, alongside other building components and their tax treatment.
Engineered Tax Services can work with property owners and their CPAs on engineering-based tax analysis and related incentive studies. The right engagement depends on the question at hand, and no study guarantees a particular tax result. If you’d like to discuss how your project documentation fits your tax planning, contact Engineered Tax Services. A well-supported discussion with your CPA is a practical foundation for sound decisions.
Frequently Asked Questions
What Does & Doesn’t Qualify as QIP?
QIP generally includes eligible interior improvements made by the taxpayer to an existing nonresidential building after it has been placed in service. Eligibility depends on the work performed, not on whether the project is called a renovation. For example, one contract may cover interior alterations and unrelated building work, so cost records should distinguish the components. This breakdown helps your CPA apply the appropriate tax treatment to each part.
Does QIP include structural building expansions?
No. Structural building expansions are not QIP. If a project renovates existing space while adding a new portion, separate the renovation costs from the addition costs. The renovation may qualify if it meets the QIP requirements; the new addition does not. Construction plans, invoices, and contractor cost details can support that distinction instead of assigning the entire project a single classification.
How do you fix QIP depreciated over 39 years?
A taxpayer may generally correct an improper depreciation method using Form 3115 and a Section 481(a) adjustment, rather than amending prior returns. The adjustment accounts for the difference between depreciation claimed and depreciation allowable under the proper method. Have your CPA review the asset’s placed-in-service year, prior returns, and depreciation history to determine the appropriate accounting-method treatment for that property.
Is QIP Section 1245 or 1250 property?
QIP is generally Section 1250 real property. However, when a taxpayer claims a Section 179 deduction for real property, the amount deducted is treated as Section 1245 property to that extent. This distinction can matter when the property is sold, because accelerated deductions may affect gain characterization. Keep the depreciation schedules and deduction elections with the property’s tax records for future sale reporting.
Is QIP treatment the same for all taxpayers?
No. The improvement must meet the QIP definition, and the taxpayer’s depreciation system and elections affect its treatment. For example, a taxpayer electing to treat the activity as a real property trade or business must use ADS for QIP; ADS treatment uses a 20-year recovery period and excludes the property from bonus depreciation. Ownership, project scope, and tax elections all matter.
What Is QIP?
Qualified improvement property is a tax category for eligible improvements a taxpayer makes to the interior of an existing nonresidential building after it has been placed in service. It distinguishes qualifying renovation components from other building costs. For example, interior work in an operating commercial property may be considered under the QIP rules, while work on a newly constructed building falls outside this category.
Disclaimer
This article is general information, not tax or legal advice. Tax rules change, and how they apply depends on your specific facts. Talk with your CPA or tax advisor before acting on anything here.