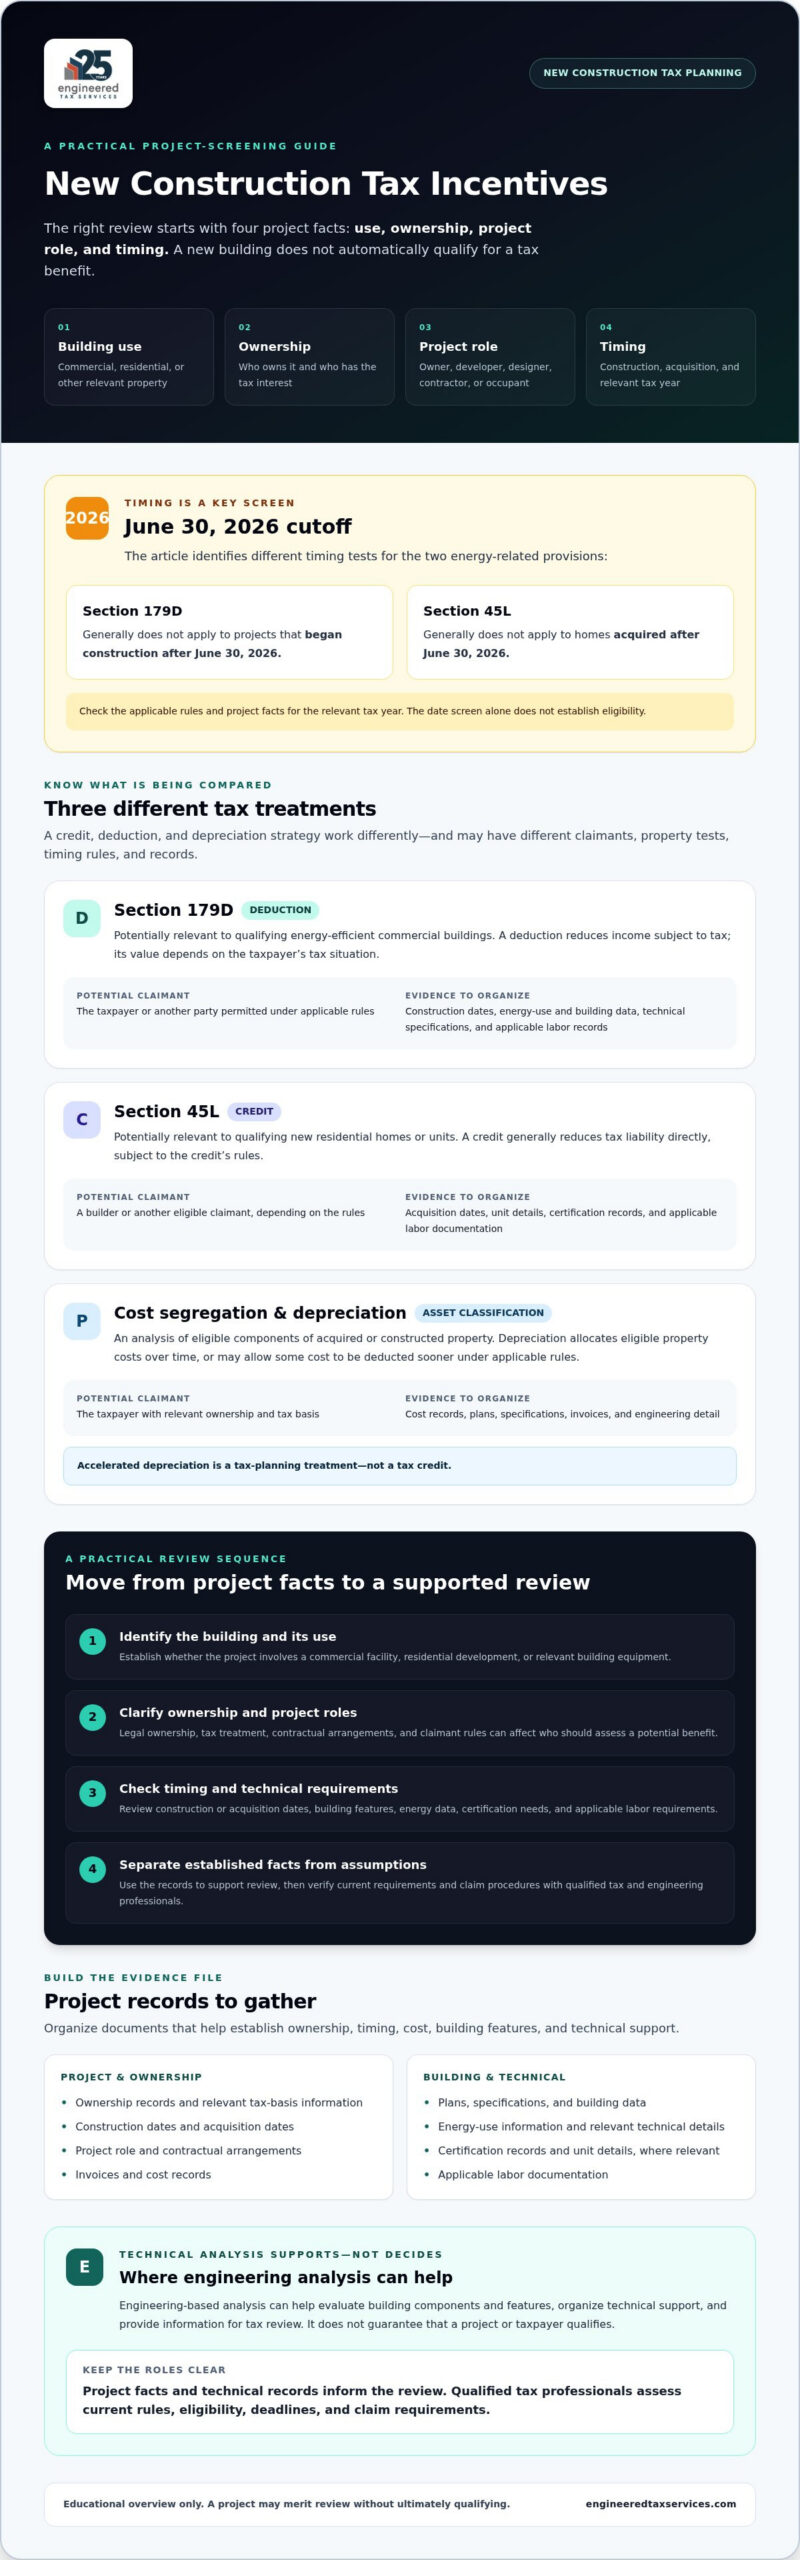
A building’s tax treatment may depend less on the fact that it’s new than on who owns it, how it’s used, and when key project milestones occurred. That’s why tax incentives for new construction aren’t a one-size-fits-all checklist. In 2026, timing is especially important: the federal Section 179D deduction generally doesn’t apply to projects that began construction after June 30, and the Section 45L credit generally doesn’t apply to homes acquired after that date.
If you’re unsure which provisions fit your building or role in the project, start by separating the possible benefits. A deduction, a tax credit, and a depreciation strategy work differently. Eligibility can also depend on technical building details, labor requirements, ownership, and supporting records.
This guide explains how to assess potential opportunities without assuming a project qualifies. You’ll learn how 179D, 45L, and cost segregation differ; which project facts and records to gather; and where timing or certification may matter. It also explains how engineering-based analysis can help evaluate building components and organize technical support, alongside advice from your qualified tax professional.
Key Takeaways
- Assess tax incentives for new construction by matching the building’s use, owner, project role, and tax year to the provisions under review.
- Distinguish credits, deductions, and depreciation strategies before comparing options such as 179D, 45L, and cost segregation.
- Gather plans, specifications, invoices, ownership records, construction dates, and energy-related documents to support an eligibility review.
- Separate confirmed project facts from assumptions, then verify current rules and claim requirements with qualified tax and engineering professionals.
- Engineering analysis can help evaluate building features and organize technical support for tax review, but it doesn’t guarantee eligibility.
Tax Incentives for New Construction: What Owners and Developers Should Know
A new building can raise several tax-planning questions. Its use, ownership structure, construction timeline, and physical features may affect which federal provisions are worth reviewing. Tax incentives for new construction are provisions that may reduce tax liability when a taxpayer and project meet applicable requirements. They are not automatic benefits of building something new, and an initial review does not determine eligibility.
What counts as a tax incentive for new construction?
Start by distinguishing the mechanisms. A tax credit generally reduces tax liability directly, subject to the credit’s rules. A deduction reduces the amount of income subject to tax, so its value depends on factors such as the taxpayer’s tax situation. A depreciation treatment allocates the cost of eligible property over time, or may allow some cost to be deducted sooner under applicable rules. Accelerated depreciation is a tax-planning treatment, not a tax credit.
These distinctions matter because provisions can have different eligible claimants, qualifying property, timing rules, and documentation standards. Energy-focused provisions such as Sections 179D and 45L have a legislative history connected to the Energy Policy Act of 2005, but that history alone doesn’t establish that a provision applies to a particular project. A commercial facility, a residential development, and equipment installed in a building may each require a different analysis. A project may merit review without ultimately qualifying.
Who should evaluate incentives during a building project?
Evaluation can involve more than the building owner. Developers may coordinate project structure and delivery. Designers can identify relevant specifications, contractors may hold construction and installation records, and businesses occupying a facility may have a tax interest in eligible property or project costs. Their involvement doesn’t mean each party can claim a provision.
Identify the tax owner and project role early. Legal ownership, tax treatment, contractual arrangements, and a provision’s claimant rules can affect who should assess a potential benefit. The person who designed or built a feature may not be the taxpayer entitled to claim a related benefit. Coordination among the owner, project team, and tax professional can clarify which facts need to be established and who should retain the supporting records.
Use early evaluation as a planning step, not an eligibility promise. Check building use, ownership, project timing, and technical features against the rules for the relevant tax year. This overview is educational, not tax advice. Confirm current eligibility, deadlines, and claim procedures with qualified tax professionals. Engineering analysis may help assess building-level facts and organize technical support for that review.
Compare 179D, 45L, and Depreciation Strategies for New Buildings
These options address different parts of a project: energy performance in commercial buildings, efficiency in qualifying homes, and the tax treatment of building costs or assets. Use the comparison below to screen for questions to investigate, not to decide eligibility. For 2026, timing is especially important: Section 179D is terminated for projects that began construction after June 30, 2026, while Section 45L is terminated for homes acquired after that date.
| Provision | Type | Potentially relevant property | Potential claimant | Evidence to organize |
|---|---|---|---|---|
| Section 179D | Deduction | Qualifying energy-efficient commercial buildings | The taxpayer or other party permitted under the applicable rules | Construction dates, energy-use and building data, technical specifications, and applicable labor records |
| Section 45L | Credit | Qualifying new residential homes or units | A builder or other eligible claimant, depending on the rules | Acquisition dates, unit details, certification records, and applicable labor documentation |
| Cost segregation and depreciation | Asset-classification analysis and depreciation treatment | Eligible components of acquired or constructed property | The taxpayer with the relevant ownership and tax basis | Cost records, plans, specifications, invoices, and engineering details |
When might 179D or 45L merit a closer review?
Section 179D is a deduction to investigate for qualifying energy-efficient commercial buildings. In 2026, the deduction ranges from $0.59 to $5.94 per square foot, with the amount depending on energy savings and prevailing wage and apprenticeship requirements. The project must also meet applicable timing rules, technical standards, and claimant requirements.
Section 45L is a credit to investigate for qualifying residential construction. For homes acquired before July 1, 2026, the credit could reach $5,000 per unit, depending on certification and other requirements. Review the IRS 45L tax credit guidance and verify the rules for the project and tax year before drawing conclusions.
How does cost segregation fit alongside construction incentives?
Cost segregation is an engineering-based analysis of property components and their appropriate tax classifications. It isn’t a separate tax credit or an energy-building deduction. For eligible property, its findings may inform depreciation planning. The potential treatment depends on current rules and the taxpayer’s facts. Project cost records and detailed engineering information can support the analysis. Explore engineering-based tax study offerings to see how technical review may complement tax planning.
How to Evaluate New-Construction Tax Incentives
A new building doesn’t automatically qualify for a tax incentive, and a project may raise different questions for its owner, developer, and occupants. Evaluate potential tax incentives for new construction by looking at the building’s use, who owns it for tax purposes, the project stage, its technical features, and the tax year under review. Treat each possible pathway as a question to investigate, not a benefit to assume.
Which project facts should guide the comparison?
Start with the project record. Identify the intended use, ownership structure, construction timeline, and when the building or relevant assets were placed in service. Note whether the project is residential or commercial, and gather available information about energy-related design features. These facts help tax and engineering professionals identify potentially relevant rules and missing evidence.
Keep verified information separate from open questions. A specification may confirm that a system was designed into the building, for example, while whether it meets a tax provision’s technical standard still needs review. Ask who may be entitled to claim a provision, which ownership or contractual facts control that answer, and what project dates or certifications need confirmation. For residential projects, consult the IRS guidelines on energy-efficient home credits when checking current requirements.
Use this screening matrix to organize the review:
- Commercial building and 179D: Potential fit depends on the applicable commercial-building and energy-efficiency rules. Gather building plans, specifications, energy-related technical information, and project dates. Confirm current standards, timing, and which taxpayer may claim.
- Residential construction and 45L: Potential fit depends on the home or unit, applicable efficiency requirements, and the claimant’s role. Gather unit details, design and certification records, and relevant acquisition dates. Verify current eligibility, deadlines, and claimant rules.
- Property costs and depreciation analysis: Potential fit depends on ownership, tax basis, and the classification of building components. Gather invoices, cost records, plans, and engineering details. Ask which assets may receive different depreciation treatment and how current tax rules apply.
Can incentives and depreciation strategies work together?
Possibly, but don’t assume that multiple benefits can be combined, applied to the same costs, or claimed by the same party. Interactions depend on current law and the project’s tax treatment. A building-level engineering review can help establish technical facts, while a qualified tax professional assesses how those facts affect the taxpayer’s position.
Before making project or reporting decisions, have the relevant professionals review the same timeline, ownership details, technical records, and tax year. A coordinated assessment helps distinguish established facts from assumptions and identify questions to resolve before pursuing a potential tax treatment.
Prepare Project Records Before Claiming Construction Tax Incentives
Strong documentation starts before anyone evaluates a potential claim. Records created during design and construction can help professionals compare the project’s actual features, costs, ownership, and timeline with the rules for a particular provision. Reconstructing those details later may be difficult, especially if plans changed or records are spread across multiple teams.
Use a practical sequence: define the project and its tax owner, gather supporting records, screen potentially relevant provisions, verify the current rules for the applicable tax year, then document the review’s conclusions and open questions. This process helps separate confirmed project facts from assumptions, but doesn’t establish eligibility on its own.
What records can help a technical review?
Keep a shared project file and update it as work progresses. Include design plans, specifications, construction invoices, and records of scope changes. Add ownership and entity information, intended occupancy or use, and key project dates for tax-professional review.
- Design and cost: Plans, specifications, invoices, and change orders that show what was installed and when.
- Ownership and timing: Ownership records, entity details, occupancy information, construction milestones, and placed-in-service details.
- Technical support: Energy models, equipment information, and relevant certification records, when available.
Preserve versions and supporting materials as they’re generated. If equipment or building specifications change during construction, retain records that show the final installed conditions, not just the initial design. These materials can help an engineering team assess building features and organize technical support for tax review.
Discuss an engineering-based incentive review to consider how project-specific technical analysis may support an evaluation. An engineering review can help assess facts, but it doesn’t guarantee that a provision applies.
When should owners begin evaluating potential incentives?
Begin screening during planning, while project scope and design decisions are still being documented. Then revisit the analysis using completed-project records. Dates and requirements differ across provisions, and a milestone that matters for one pathway may not determine another. Verify applicable deadlines, placed-in-service rules, and claim procedures with a qualified tax professional for the relevant tax year.
For more detail, consult the article’s guides to the 179D deduction and 45L tax credit. Use them as starting points, then confirm current requirements against authoritative guidance and your project facts. Well-organized records make that review more focused.
Work With an Engineering Team to Evaluate New-Construction Tax Incentives
A project’s tax review may depend on details that aren’t obvious from a high-level budget or building description. Engineering analysis can help assess physical features, compare installed conditions with project documentation, and organize technical findings for review by the taxpayer’s tax professional. It adds a building-level perspective while keeping technical conclusions distinct from tax advice and final eligibility determinations.
What does an engineering-based incentive study contribute?
An engineering-based study can examine relevant building systems, components, specifications, and project records to clarify what was designed and installed. If a project team is evaluating an energy-related provision, for example, technical analysis may help establish which building characteristics and supporting materials need further review. If the question involves asset classification, engineering detail can help connect project costs to physical components for a cost segregation analysis.
Those findings don’t, by themselves, establish that a taxpayer qualifies or determine the final tax treatment. In a coordinated review, engineering professionals address building facts while qualified tax professionals assess the applicable rules, claimant, tax year, and reporting considerations. This division of expertise can help surface missing information and unresolved questions before conclusions are drawn.
Engineered Tax Services offers the 179D EPAct deduction, 45L tax credits, cost segregation, and engineered incentives reports. The right scope depends on the project and the questions being investigated. Not every building requires the same analysis.
What should owners ask before beginning a review?
Set expectations at the outset. Ask which provisions are being evaluated, why they may be relevant to the building, and which project facts support the initial screening. Clarify what technical records are needed, what the engineering scope includes, who will provide missing materials, and how findings will be shared with the tax professional.
Confirm that the review will address the correct filing-year rules and relevant project dates. If a key fact is uncertain, such as the final installed condition or the party with the potential claim, identify how it will be investigated rather than treating an assumption as settled. Clear responsibilities help the owner, project team, engineering specialist, and tax professional work from consistent information.
For a project-specific discussion of engineering-based analysis, explore Engineered Tax Services incentive studies. A study can help evaluate project facts and organize technical support, but eligibility and any tax outcome depend on the applicable rules and taxpayer circumstances.
Turn Project Records Into a Clear Next Step
The right review starts with the project, not an assumption that every new building qualifies. Match building use, ownership, timing, and technical features to the provisions under consideration, then confirm current rules with qualified tax professionals. Organized project records help the team separate established facts from open questions and decide whether further analysis is warranted.
Engineered Tax Services’ engineering-based studies include 179D, 45L, cost segregation, and engineered incentives reports. The company conducts more than 10,000 tax studies annually. Technical analysis can help assess building details and support tax review, but it doesn’t promise eligibility, savings, or a particular tax result.
To assess which tax incentives for new construction may merit review for your project, discuss your new-construction incentive review with Engineered Tax Services. Organized records and coordinated expertise can help clarify your next steps.
Frequently Asked Questions
What tax incentives are available for new construction in 2026?
Potential options include the Section 179D deduction for qualifying energy-efficient commercial buildings, the Section 45L credit for qualifying new homes, and depreciation strategies for eligible property. Timing limits matter: 179D is terminated for projects that began construction after June 30, 2026, and 45L is terminated for homes acquired after that date. Qualified assets acquired and placed in service in 2026 may also qualify for 100% bonus depreciation. Verify current rules and project facts with a tax professional.
Can a new commercial building qualify for the 179D deduction?
A commercial building may merit review for 179D, but new construction alone doesn’t establish eligibility. The building must meet applicable energy-efficiency and other requirements, and the claimant and supporting documentation must align with current rules. For projects that began construction after June 30, 2026, the deduction has been terminated. Projects that began construction on or before that date may remain eligible, subject to review of technical standards, dates, and claimant requirements.
Can multifamily new construction qualify for the 45L tax credit?
Potentially. Section 45L may apply to qualifying residential units, including multifamily construction, when applicable efficiency, certification, claimant, and other requirements are met. For homes acquired before July 1, 2026, the credit could reach $5,000 per unit, depending on certification and other requirements. The credit is terminated for homes acquired after June 30, 2026. Have a tax professional verify how acquisition timing and the project’s facts affect a potential claim.
Is cost segregation a tax credit for new construction?
No. Cost segregation is an engineering-based depreciation analysis, not a tax credit. It examines building components and project costs to assess their appropriate tax classifications under applicable rules. For a new building, plans, specifications, invoices, and construction details can inform the analysis. Any resulting depreciation treatment depends on the taxpayer’s ownership, tax basis, and current law. A qualified tax professional should assess how study findings apply to the taxpayer’s return and tax year.
Can a building qualify for more than one construction tax incentive?
Possibly, but don’t assume that multiple provisions can be claimed together, applied to the same costs, or claimed by the same party. The answer depends on current law, project details, tax ownership, and each provision’s requirements. A building’s energy features and asset classifications raise distinct questions that may need separate technical and tax analysis. Ask qualified professionals to review potential interactions before relying on a combined tax result.
What documents should I keep for a new-construction tax incentive review?
Keep design plans, specifications, invoices, construction dates, ownership and entity records, and documentation of scope changes. For energy-related reviews, retain available energy models, equipment details, and certification records. Occupancy and placed-in-service information may also help tax professionals assess the timeline. Preserve records as the project progresses rather than trying to recreate them later. The exact evidence needed depends on the provision under review and should be confirmed for the relevant tax year.
When should I evaluate tax incentives for a new construction project?
Begin screening during project planning, then revisit the analysis with records showing what was ultimately built and when. Early review can help identify which design details, dates, and documents need attention, but it doesn’t confirm eligibility. Deadlines and placed-in-service or acquisition rules vary by provision. For example, 179D and 45L have different 2026 termination timing. Confirm current dates, requirements, and claim procedures with qualified tax professionals before making project or filing decisions.