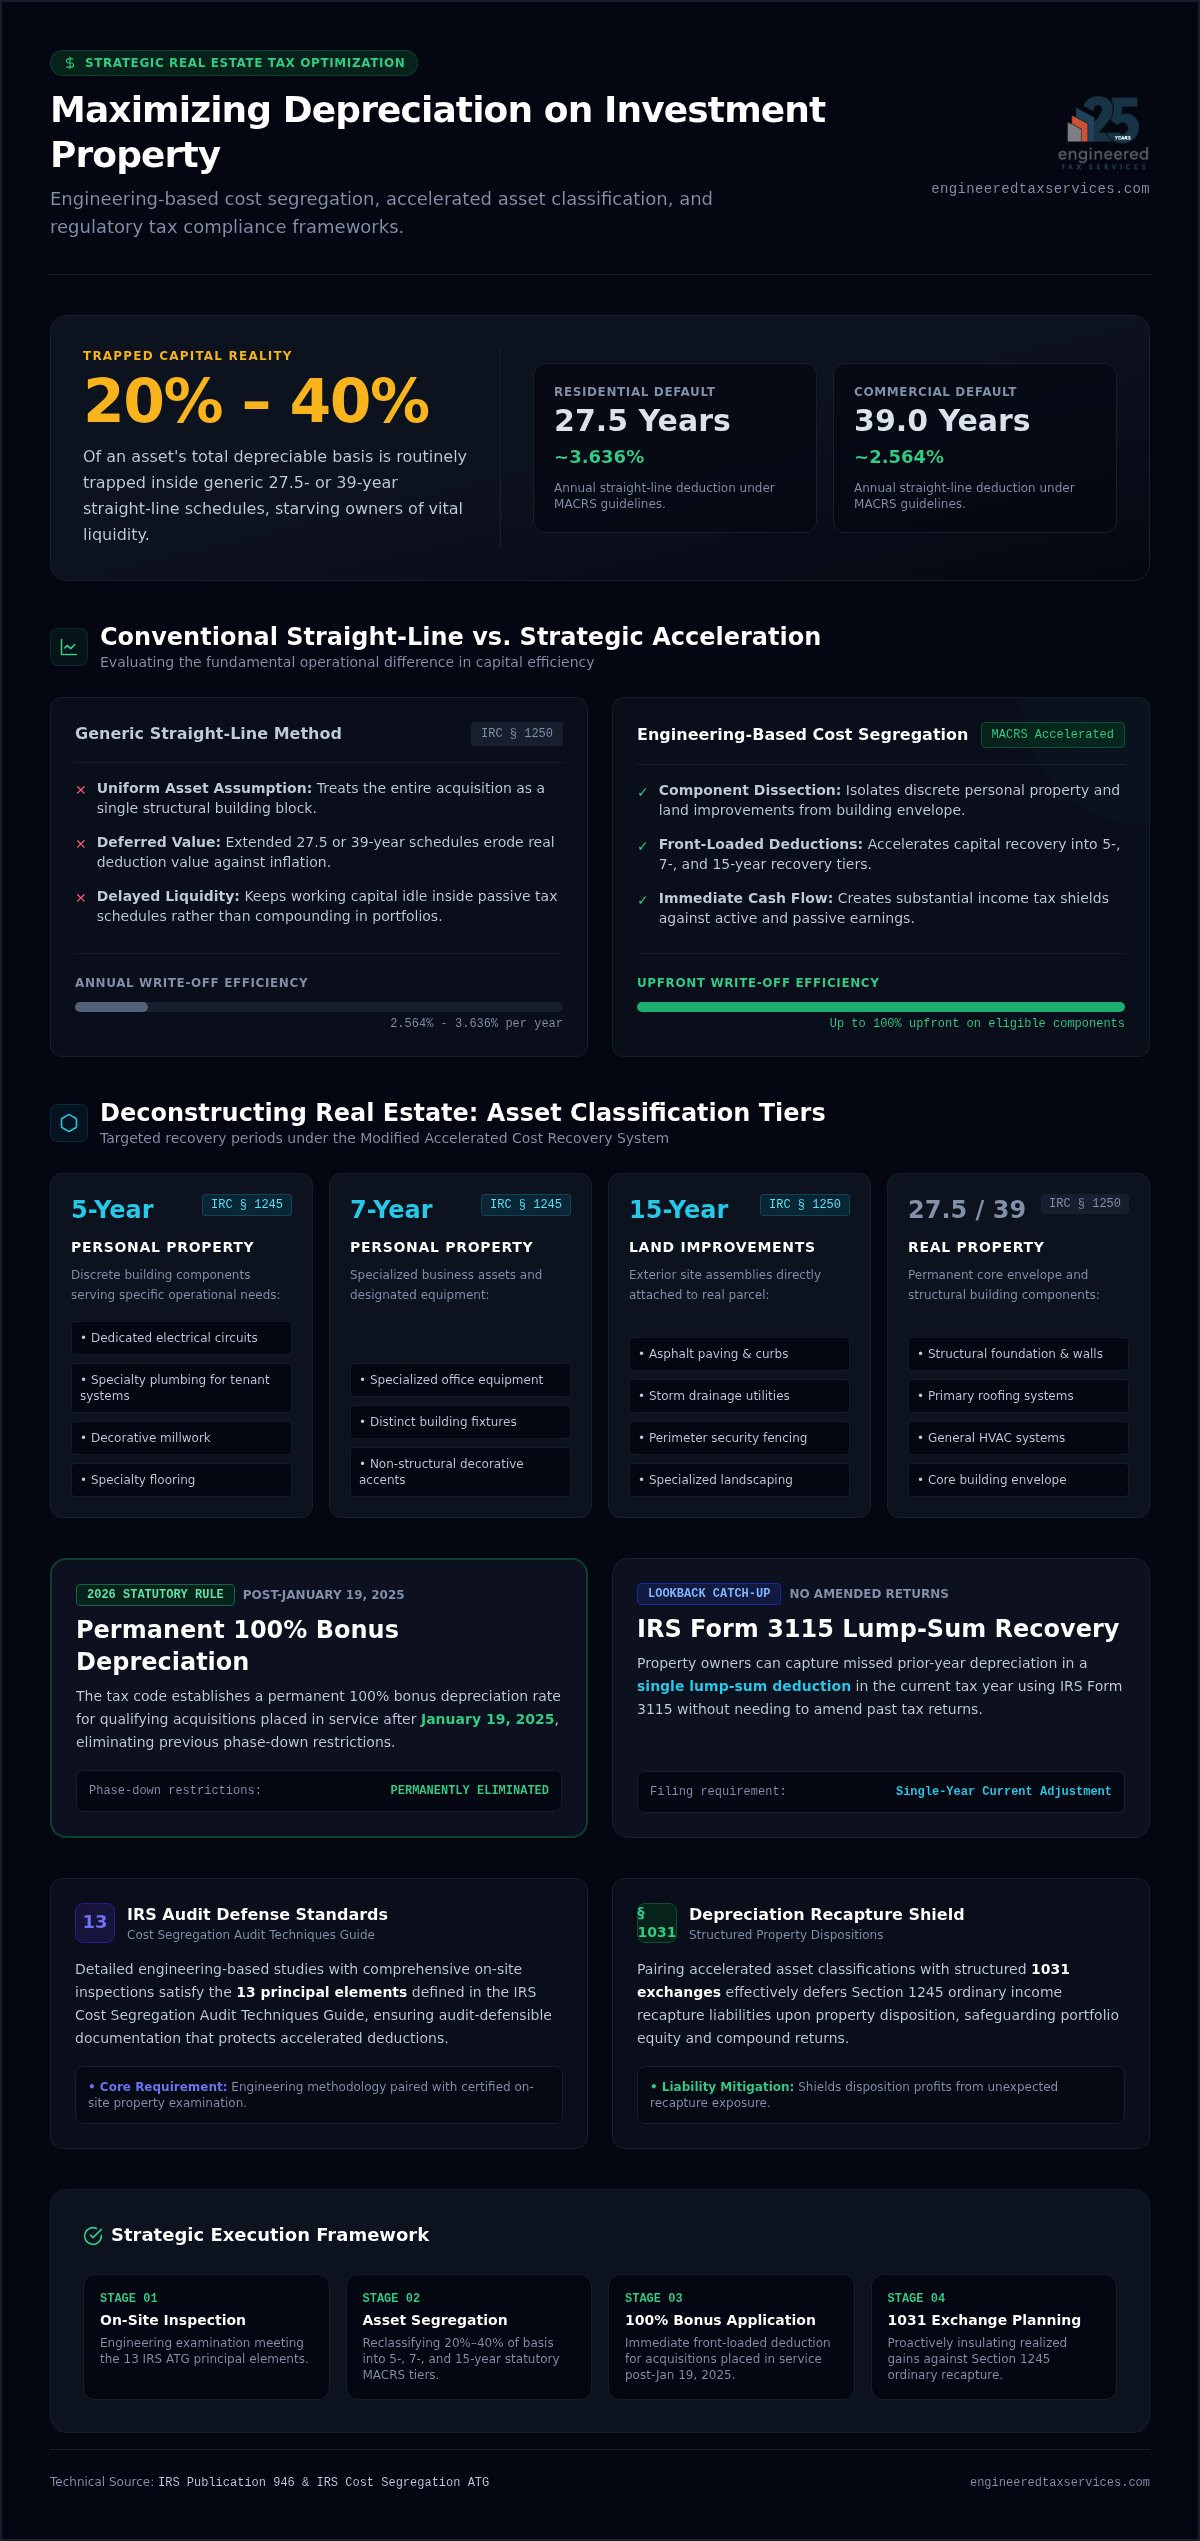
Between 20% and 40% of an asset's depreciable basis is routinely trapped inside generic 27.5- or 39-year straight-line schedules, starving commercial and residential investors of vital liquidity. Maximizing depreciation on investment property requires moving beyond baseline compliance to treat your real estate as a high-performance financial asset. You already recognize that conventional accounting schedules deliver negligible annual tax relief, yet shifting bonus depreciation statutes and fears of IRS examination often cause investors to leave substantial capital on the table.
Discover how engineering-based cost segregation and strategic asset classification accelerate property depreciation to dramatically enhance cash flow. You don't have to wait decades to unlock that equity. In this 2026 strategic guide, we explore how to front-load substantial deductions into your earliest ownership periods, establish audit-defensible documentation aligned with the IRS Cost Segregation Audit Techniques Guide, and integrate proactive 1031 exchange planning to shield disposition profits from unexpected recapture taxes.
Key Takeaways
- Reclassifying building components into 5-, 7-, and 15-year recovery periods is the cornerstone of maximizing depreciation on investment property to optimize current liquidity.
- The tax code establishes a permanent 100% bonus depreciation rate for qualifying acquisitions placed in service after January 19, 2025, eliminating previous phase-down restrictions.
- Property owners can capture missed prior-year depreciation in a single lump-sum deduction using IRS Form 3115 without amending past returns.
- Pairing accelerated asset classifications with structured 1031 exchanges effectively defers Section 1245 ordinary income recapture liabilities upon disposition.
- Detailed engineering-based studies with on-site inspections satisfy the 13 principal elements defined in the IRS Cost Segregation Audit Techniques Guide to safeguard deductions.
Understanding Investment Property Depreciation: Straight-Line Versus Accelerated Strategies
Under the Internal Revenue Code, property depreciation allows investors to recover the capital cost basis of income-producing real estate over statutory IRS lifespans. Under the Modified Accelerated Cost Recovery System (MACRS), residential rental real estate defaults to an extended 27.5-year straight-line schedule, yielding an annual deduction of roughly 3.636%. Nonresidential commercial real estate stretches across 39 years, spreading tax benefits over four decades at an annual rate of approximately 2.564%. While standard schedules deliver passive paper deductions, they fail to optimize immediate portfolio liquidity. Strategic acceleration re-engineers this approach, front-loading tax deductions to maximize the net present value of capital. For forward-thinking investors, maximizing depreciation on investment property is a fundamental discipline of capital efficiency.
The Limitations of Conventional Straight-Line Depreciation
Default straight-line accounting treats an entire property as a single, uniform asset. In practice, modern properties contain intricate mechanical, electrical, and decorative assemblies that wear out long before decades elapse. Spreading your basis evenly over 27.5 or 39 years ignores the rapid economic deterioration of these shorter-lived components. Simultaneously, inflation steadily degrades the purchasing power of deductions deferred deep into your ownership horizon. Conventional straight-line depreciation traps vital working capital within slow-motion tax schedules, delaying liquidity that could otherwise finance higher-yielding investments today.
The Economic Power of Accelerated Cash Flow
Transitioning to an accelerated framework converts passive tax allowances into dynamic liquidity. By commissioning an engineering-based cost segregation study, property owners can isolate specific building systems from structural envelopes and shift them into accelerated asset classes. This strategy establishes substantial upfront income tax shields against passive earnings and active income streams alike. That preserved equity can be immediately redeployed, producing compound returns across an expanding real estate portfolio. Review our comprehensive 2026 Guide to Commercial Real Estate Depreciation to explore baseline fundamentals and recovery benchmarks. Ultimately, maximizing depreciation on investment property keeps your wealth compounding inside your portfolio rather than sitting idle on standard tax forms.
Engineering-Based Cost Segregation: The Engine for Maximized Deductions
Cost segregation operates as the primary catalyst for maximizing depreciation on investment property. Rather than accepting the standard assumption that an entire acquisition constitutes long-life real property under IRC Section 1250, this engineering methodology dissects acquired real estate into its discrete structural and non-structural elements. By referencing statutory guidelines outlined in IRS Publication 946, licensed engineers isolate qualifying personal property from the overarching 39-year commercial or 27.5-year residential envelope, accelerating cost recovery into dramatically shorter tax lifecycles.
Deconstructing Real Estate: 5-, 7-, and 15-Year Class Lifetimes
Precision asset classification relies on segregating components into distinct recovery tiers under the Modified Accelerated Cost Recovery System:
- 5-Year Personal Property (IRC § 1245): Includes dedicated electrical circuits, specialty plumbing connections for tenant equipment, decorative millwork, and specialty flooring.
- 7-Year Personal Property (IRC § 1245): Covers specialized office equipment, distinct building fixtures, and non-structural decorative accents.
- 15-Year Land Improvements (IRC § 1250): Captures exterior site improvements such as asphalt paving, concrete curbing, storm drainage utilities, perimeter fencing, and specialized landscaping.
Reclassifying these short-life assets unlocks accelerated write-offs, dramatically improving immediate operational liquidity.
Engineering Rigor Versus Accounting Estimation
True asset segregation cannot be completed through desk reviews or crude mathematical modeling. The IRS Cost Segregation Audit Techniques Guide explicitly mandates rigorous physical inspections, detailed blueprint analyses, and precise contractor payment reconciliations. Algorithmic software estimates lack the technical substantiation necessary during formal audits, leaving taxpayers vulnerable to reclassification disallowances and penalties.
Licensed engineering professionals review technical architectural specifications and inspect actual build-outs to establish verifiable unit-cost valuations. Review our strategic blueprint for cost segregation for commercial property to evaluate these institutional standards. By collaborating with seasoned specialists such as Engineered Tax Services, property owners secure audit-defensible reports that bridge CPA accounting compliance with forensic engineering precision.
Navigating Bonus Depreciation and Asset Reclassifications in 2026
The Tax Cuts and Jobs Act of 2017 initially established a phased reduction schedule that saw bonus expensing drop across consecutive years, leading many investors to assume deductions would bottom out in 2026. However, under current federal tax statutes governing the 2026 tax year, bonus depreciation is permanently established at 100% for qualifying property acquired and placed in service after January 19, 2025. This permanent expensing status eliminates phase-down uncertainty, ensuring assets segregated into 5-, 7-, or 15-year buckets are eligible for full, immediate first-year write-offs. Strategic engineering timing coordinates contract execution dates and placed-in-service declarations, ensuring every transaction secures peak deduction efficiency. For commercial and residential operators, maximizing depreciation on investment property begins by aligning these statutory classifications directly with acquisition milestones.
The Compounding Value of MACRS Accelerated Depreciation
Even when property owners elect out of bonus expensing to manage specific passive loss limitations, reclassified personal property and land improvements still outperform standard schedules through the statutory Modified Accelerated Cost Recovery System. Under MACRS, 5- and 7-year asset classes utilize the 200% declining balance convention, while 15-year land improvements deploy the 150% declining balance method. This structure concentrates significant tax deductions into the opening years of ownership. Component segregation creates exceptional financial leverage across any tax posture, keeping capital active in your business rather than locking it into four decades of linear amortization.
Integrating Energy Deductions Under Section 179D
Commercial property owners can amplify their immediate tax relief by layering specialized federal energy incentives alongside accelerated asset recovery. Modernizations to central HVAC systems, automated interior lighting, and thermal building envelopes can qualify for the 179D energy efficient commercial building deduction. This provision delivers immediate per-square-foot tax deductions that stack cleanly on top of core cost segregation results. Integrating engineering studies across both programs establishes a comprehensive tax shield, boosting cash flow and maximizing depreciation on investment property during extensive capital improvement cycles.
Safeguarding Wealth: Managing Depreciation Recapture and Dispositions
Accelerated write-offs create immense initial liquidity, but maximizing depreciation on investment property demands a clear disposition strategy. When an investor liquidates a property, the IRS mandates depreciation recapture to recover prior tax deductions. Navigating this exit requires understanding the distinct tax treatment between statutory asset classifications:
- IRC Section 1245 Recapture: Gain attributable to personal property reclassified into 5- and 7-year schedules is taxed at ordinary income rates up to 37%.
- IRC Section 1250 Unrecaptured Gain: Deductions claimed against 27.5- or 39-year real property envelopes face a maximum federal statutory rate of 25%.
This 12-point spread between ordinary income and capital rates highlights why upfront modeling is critical. Without a multi-year disposition roadmap, sudden recapture liabilities can erode early cash flow windfalls.
Partial Asset Dispositions and Abandonment Losses
Investors can systematically mitigate recapture exposure during renovations by utilizing the IRS Tangible Property Regulations. When you demolish obsolete building components, such as outdated roof structures, worn flooring, or aging chillers, you don't have to continue depreciating them for decades. A partial asset disposition election enables property owners to write off the remaining unrecovered basis of discarded assets as an immediate ordinary loss deduction. Detailed engineering records establish exact historical cost allocations for those retired components, converting demolition work into an immediate tax shield while permanently eliminating future Section 1250 recapture obligations on discarded materials.
Deferring Recapture Liabilities via Section 1031 Exchanges
Property owners planning full divestments can circumvent immediate tax consequences through strategic reinvestment. Executing a like-kind exchange under IRC Section 1031 defers recognized capital gains and accumulated Section 1245 and 1250 depreciation recapture in full. When acquiring a replacement asset, initiating a new cost segregation study generates fresh front-loaded deductions, effectively counteracting residual tax burdens while keeping baseline portfolio equity intact. Explore how comprehensive 1031 exchange services safeguard wealth across complex commercial acquisitions. To safeguard your disposition profits while optimizing annual deductions, connect with Engineered Tax Services to implement an integrated tax optimization strategy across your real estate portfolio.
Executing an Audit-Defensible Property Depreciation Strategy
Successfully maximizing depreciation on investment property requires moving from theoretical tax models to an institutional execution framework. While certified public accountants excel at yearly compliance and ledger reconciliation, they rarely possess the architectural training necessary to value isolated physical building components. Unlocking maximum value demands a collaborative model where licensed engineering specialists partner directly with your primary CPA. This cross-disciplinary approach generates the detailed evidentiary trail required by the IRS Cost Segregation Audit Techniques Guide, giving property owners confidence that their accelerated deductions will withstand federal scrutiny.
The Four-Stage Engineering Tax Study Process
Precision tax engineering follows a structured, four-phase project lifecycle designed to satisfy all 13 principal elements recognized by IRS examiners:
- Phase 1: Feasibility and Preliminary Modeling: Analysts evaluate purchase documentation, closing statements, and depreciation schedules to determine whether projected tax savings comfortably justify an engineering engagement.
- Phase 2: On-Site Engineering Inspection: Field engineers tour the property to photograph, measure, and catalog qualifying assets, documenting dedicated electrical lines, specialty plumbing runs, decorative treatments, and site infrastructure.
- Phase 3: Unit-Cost Allocation and Pricing: Specialists cross-reference blueprints, architectural specifications, and contractor applications against verified construction cost databases to calculate replacement and historic costs.
- Phase 4: Final Reporting and CPA Delivery: The engineering team issues a signed technical report allocating asset costs directly into corresponding MACRS asset classes ready for immediate tax preparation.
Retroactive Deductions: Maximizing Prior Acquisitions Without Amending Returns
Investors who maintained properties on default 27.5- or 39-year schedules in prior tax years haven't lost those deductions. IRS regulations do not require you to file cumbersome amended returns to claim unrecovered past benefits. Under Revenue Procedure 2015-13, taxpayers file IRS Form 3115 to execute an automatic change in accounting method.
This procedural look-back triggers a Section 481(a) negative adjustment, allowing property owners to recognize the entire cumulative difference between straight-line and accelerated depreciation as a single lump-sum deduction in the current filing year. That mechanism turns prior oversight into immediate working capital. Partner with Engineered Tax Services to implement defensible, high-impact depreciation strategies across your national portfolio and transform latent property equity into dynamic enterprise liquidity.
Accelerate Your Capital Strategy Through Precision Engineering
Relying on generic straight-line schedules unnecessarily handcuffs your operational liquidity. By leveraging forensic cost segregation to separate short-life building components, capturing permanent 100% bonus expensing, and structuring proactive exit plans, maximizing depreciation on investment property becomes your most dependable catalyst for sustained wealth creation. Every tax dollar preserved through technical precision represents fresh equity ready for deployment into your next commercial opportunity.
As an independent licensed engineering firm conducting over 10,000 engineering tax studies nationwide each year, Engineered Tax Services delivers audit-defense methodologies strictly aligned with the IRS Cost Segregation Audit Techniques Guide. Our dedicated technical specialists partner seamlessly with your primary CPA to convert complex property assets into verified cash flow. You don't have to leave vital working capital trapped across decades of linear amortization. Request an Engineering Feasibility Analysis from Engineered Tax Services today to safeguard your disposition profits and unlock the latent capital inside your real estate portfolio.
Frequently Asked Questions
How much can a cost segregation study increase first-year depreciation on an investment property?
A certified engineering study typically reclassifies 20% to 40% of a property's depreciable basis into 5-, 7-, or 15-year asset classes. When paired with 100% bonus depreciation, these reclassified components are deducted entirely in the first year. For a building basis of one million dollars, this can translate into $200,000 to $400,000 in immediate tax write-offs, creating liquidity that straight-line schedules would otherwise defer across decades.
Can I maximize depreciation on an investment property purchased in previous tax years?
Yes, you can capture missed deductions on properties acquired in prior tax years through a retroactive look-back study. IRS rules don't require you to file cumbersome amended returns. Instead, you file IRS Form 3115 under automatic consent procedures. This triggers a Section 481(a) adjustment, delivering the full cumulative difference of all uncaptured prior-year depreciation as an immediate lump-sum deduction on your current federal return.
What is the difference between Section 1245 and Section 1250 depreciation recapture?
Section 1245 governs personal property and specialized building systems, taxing recaptured deductions as ordinary income at rates reaching 37% upon sale. Section 1250 governs straight-line structural real estate, taxing unrecaptured depreciation at a statutory maximum federal rate of 25%. Understanding this rate differential is vital when structuring long-term hold periods, planning capital asset dispositions, or coordinating tax-deferred 1031 exchanges across commercial portfolios.
How does the bonus depreciation phaseout affect accelerated depreciation strategies in 2026?
The previous bonus depreciation phase-down schedule is no longer active for current transactions. Current tax legislation permanently restored 100% bonus depreciation for qualifying real property components placed in service after January 19, 2025. For property owners, maximizing depreciation on investment property no longer requires navigating partial write-off thresholds, allowing full first-year expensing for all segregated 5-, 7-, and 15-year building components.
Is a physical engineering inspection required by the IRS for cost segregation studies?
While the tax code doesn't explicitly bar desk reviews, the IRS Cost Segregation Audit Techniques Guide strongly prioritizes physical site visits. Studies performed without physical engineering inspections face substantially higher audit scrutiny and disallowance risk. Licensed engineers conduct on-site evaluations to accurately photograph, measure, and substantiate individual components, creating an indisputable evidentiary trail that protects your deductions during federal examinations.
Can residential rental property owners utilize accelerated depreciation strategies?
Yes, residential rental owners can fully utilize engineering-based acceleration strategies. Even though residential buildings default to a standard 27.5-year schedule, multifamily complexes and single-family rental portfolios contain substantial eligible short-life property. Flooring, cabinetry, tenant-specific electrical lines, appliances, and outdoor site improvements can all be segregated out of the structural basis, accelerating capital recovery and maximizing depreciation on investment property.
What qualifies as a land improvement under 15-year property classifications?
Land improvements encompass exterior non-structural assets situated directly on the real estate parcel. Under statutory MACRS 15-year guidelines, qualifying items include asphalt parking lots, concrete sidewalks, curbing, perimeter fencing, outdoor security lighting, and hardscaping elements. These improvements remain completely distinct from non-depreciable raw land, allowing property owners to accelerate substantial exterior site development costs that would otherwise sit trapped inside long-term schedules.