Can an upgrade to an existing building qualify for the 179D deduction for retrofits? Yes, but installing efficient equipment alone isn’t enough. Eligibility depends on the project’s timing, the applicable energy-savings pathway, and technical evidence that supports the claim. For 2026, the construction-start deadline is especially important: projects beginning construction after June 30, 2026, aren’t eligible under current law.
Retrofit rules can differ from new-construction requirements. Building age, energy-use measurements, and project records can all affect the analysis. This guide explains the retrofit eligibility framework, the upgrades and performance evidence to evaluate, and the documentation that can help substantiate a claim. It also covers 2026 timing and standards to verify before taking a deduction. An engineering-based review connects project records with building-performance analysis, bringing structure and clarity to the evaluation.
Key Takeaways
- The 179D deduction for retrofits depends on the applicable eligibility pathway and project facts, not simply on whether new equipment is energy efficient.
- Assess whether the project scope and building-performance evidence align with the retrofit-specific technical tests.
- Gather drawings, specifications, invoices, equipment schedules, utility bills, and completion dates for a thorough review.
- Compare retrofit and new-construction requirements, especially for timing, energy-performance evidence, and documentation.
- Use engineering analysis to connect project records with building-performance evidence, then verify current legal requirements before pursuing a claim.
What Is the 179D Deduction for Retrofits to Existing Buildings?
Section 179D is a federal income tax deduction for qualifying energy-efficient commercial building property. A deduction reduces taxable income; unlike a tax credit, it doesn’t directly reduce tax owed dollar for dollar. Created under the Energy Policy Act of 2005, the incentive applies only when a project meets the applicable legal and technical requirements.
The 179D deduction for retrofits concerns qualifying energy improvements to existing commercial buildings, not every renovation or equipment replacement. Lighting, HVAC, hot water systems, and the building envelope may warrant evaluation, but the project scope and statutory definitions determine which property counts. Replacing an aging system with a newer model, for example, doesn’t by itself prove that the retrofit meets the required energy-performance test.
Which existing-building projects might warrant a 179D review?
An integrated upgrade involving lighting controls, HVAC equipment, or insulation may warrant technical review, but it doesn’t automatically qualify for a deduction. Repainting, reconfiguring office space, or replacing finishes is generally cosmetic work unless it is part of a qualifying energy-efficiency project. To assess a project, identify the work performed, the property included, and the evidence available to evaluate energy performance.
How does the retrofit pathway differ from new construction?
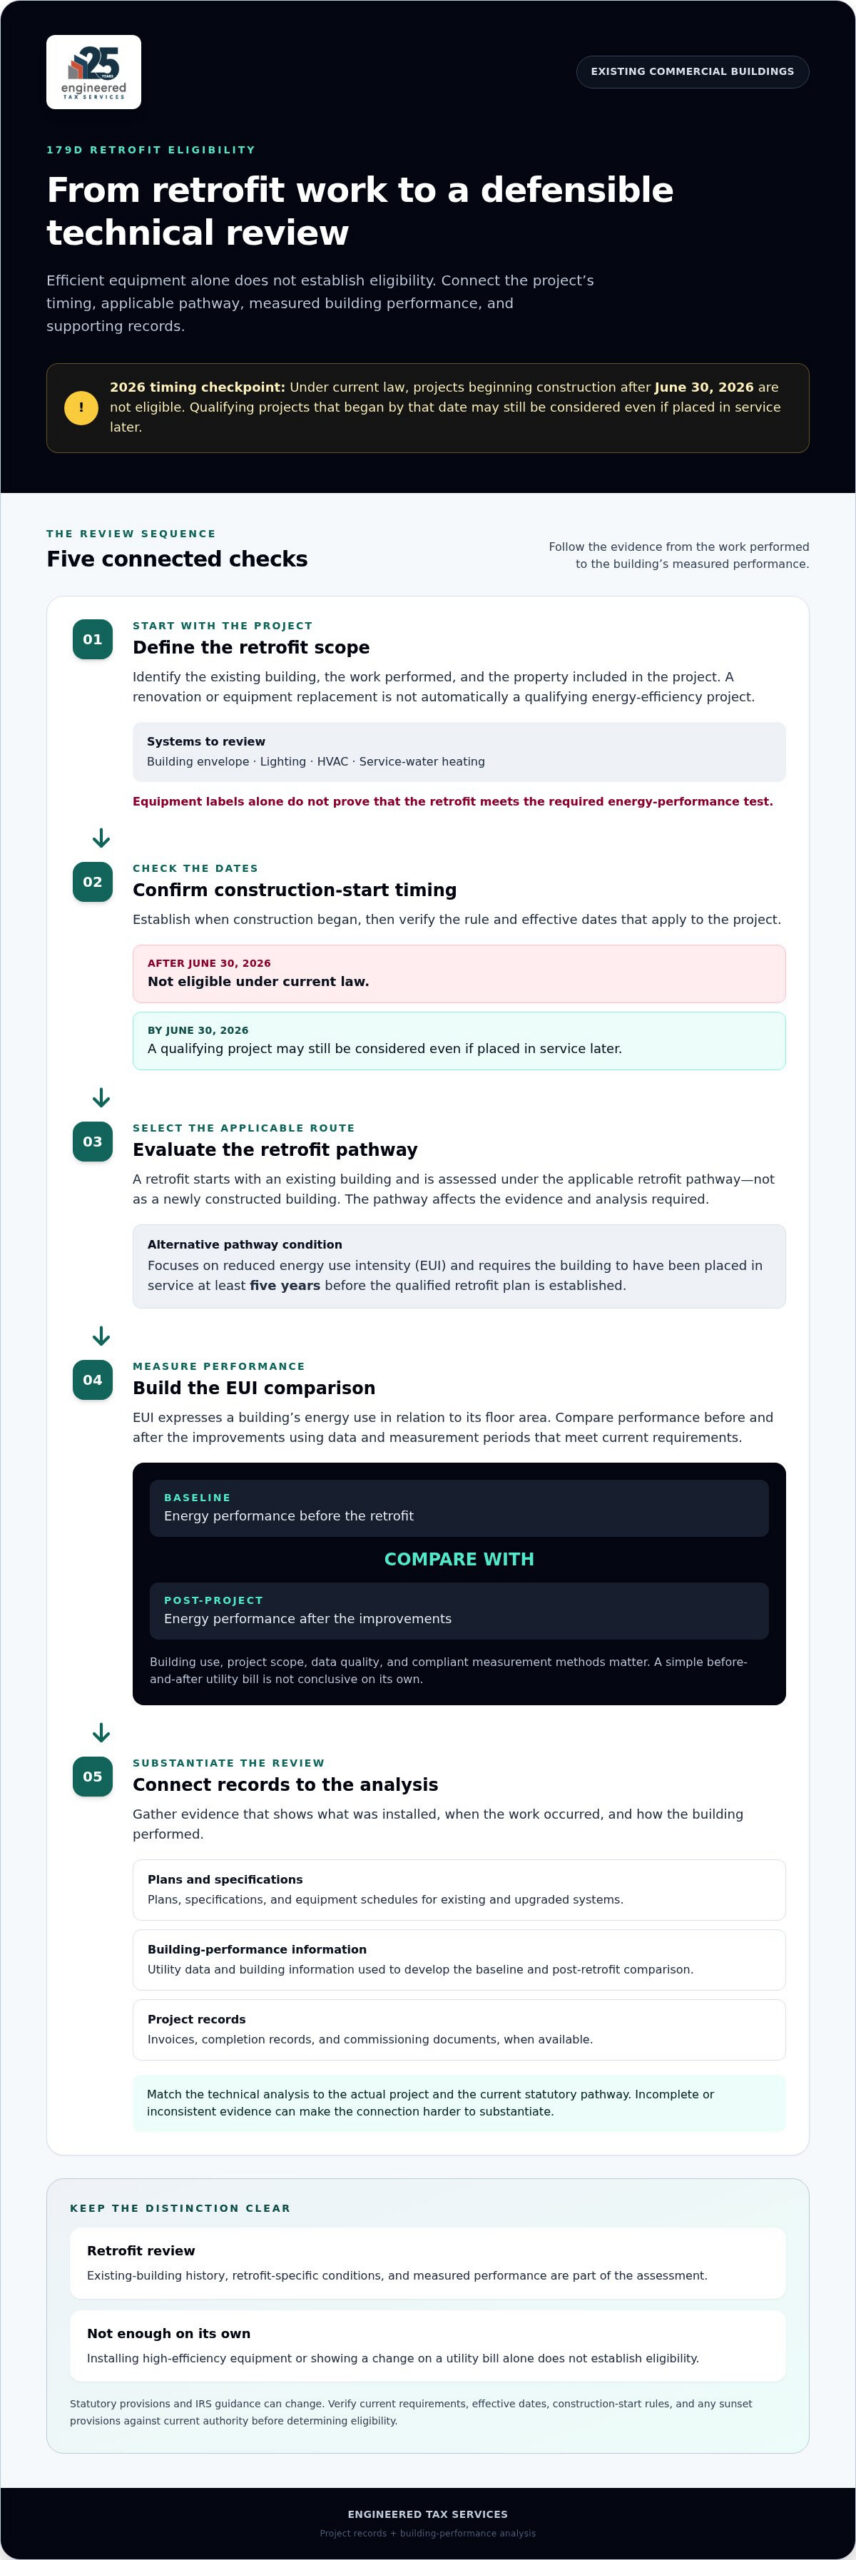
A new building is evaluated as a newly constructed project. A retrofit starts with an existing building and assesses improvements under the applicable retrofit pathway. That distinction can affect the evidence and analysis required, including how energy performance is evaluated and whether the building meets retrofit-specific conditions. Under current 2026 law, construction-start timing also matters: projects beginning construction after June 30, 2026, aren’t eligible, while qualifying projects that began by that date may still be considered even if placed in service later. Verify the rules that apply to the project’s facts before relying on this treatment.
For a retrofit, the alternative pathway focuses on reduced energy use intensity and requires that the building have been placed in service at least five years before the qualified retrofit plan is established. The technical analysis must connect the building’s history and plan with measured performance, rather than rely on equipment labels alone. A broader 179D strategic guide can provide additional context on the deduction’s framework and claim considerations.
How Does a 179D Retrofit Qualify? Understand the Technical Tests
A retrofit doesn’t qualify simply because it uses high-efficiency equipment. The analysis must identify the applicable statutory pathway, define the work performed, and assess building performance under the rules that apply to the project. A new chiller, LED lighting, or upgraded insulation may be relevant, but equipment labels alone don’t establish eligibility.
For the retrofit pathway, the qualified retrofit plan and energy-use-intensity (EUI) analysis are central considerations. EUI expresses a building’s energy use in relation to its floor area. The analysis compares a baseline period with performance after the improvements, using data and measurement periods that meet current requirements. The comparison should reflect the building and project accurately; a simple before-and-after utility bill isn’t conclusive on its own.
Statutory provisions and IRS guidance can change, so verify current requirements before relying on a particular plan, measurement period, or claimed reduction. The IRS guidelines on 179D are an important primary reference. For 2026 projects, confirm the applicable effective dates, construction-start rules, and any sunset provisions against current authority before determining eligibility.
What does energy-use-intensity reduction mean in a retrofit analysis?
EUI is energy use divided by a building’s floor area over a defined period. The baseline describes energy performance before the retrofit; post-project data shows performance after the improvements. Comparing the two can help evaluate whether energy use changed, but a reliable analysis must use periods and methods that satisfy the governing requirements. Project scope, building use, and the quality of available data all matter.
What building systems and project records support evaluation?
Review the improvements and supporting evidence together. Relevant systems may include the building envelope, lighting, HVAC, and service-water heating. Records can establish what was installed, when the work occurred, and how the building performed:
- Plans, specifications, and equipment schedules showing existing and upgraded systems
- Utility data and building information used to develop the baseline and post-retrofit comparison
- Invoices, completion records, and commissioning documents, when available
Match the technical analysis to the actual project and the current statutory pathway. A complete record helps explain the connection between retrofit work and measured building performance; incomplete or inconsistent evidence can make that connection harder to substantiate. Engineered Tax Services conducts engineering-based 179D studies that bring project documentation and performance analysis together. Explore 179D engineering analysis as part of a technically grounded review.
179D Retrofit Deduction vs. New Construction: Resolve Common Eligibility Misconceptions
An energy-efficient renovation doesn’t automatically qualify for a 179D deduction. The project must meet statutory requirements and the applicable technical test. The deduction amount depends on current law and the project’s specific facts. Replacing a rooftop unit with a more efficient model may support an analysis, but the equipment’s efficiency rating alone doesn’t establish that the building or qualifying property meets the required criteria.
Retrofit and new-construction projects also start from different building conditions, which affects the performance evidence and records needed to evaluate them.
| Review factor | Existing-building retrofit | New construction |
|---|---|---|
| Project type | Improvements to an existing building; evaluate the actual retrofit scope and applicable pathway. | Energy-efficient property incorporated into a newly constructed building. |
| Timing | Review construction-start dates and relevant building history, including dates tied to the retrofit plan. | Review construction-start and placed-in-service facts under the rules for the project. |
| Energy-performance evidence | May require baseline and post-retrofit energy-use evidence under the applicable measurement pathway. | Evaluate performance using the applicable new-construction method and reference criteria. |
| Documentation | Preserve records of existing conditions, retrofit scope, energy data, and completed work. | Preserve design, construction, system, and performance records supporting the project analysis. |
For 2026, current law generally excludes projects whose construction begins after June 30, 2026. Confirm the effective-date rules and how they apply to the project before relying on a deduction, including where construction began by the cutoff but the building is placed in service later. The Department of Energy 179D guidance describes technical pathways, including the alternative measurement approach for retrofits. Verify current legal requirements against primary authority.
Does every energy-efficient renovation qualify for 179D?
No. The work must satisfy the applicable statutory and technical requirements. A product specification can show that a fixture or system is efficient, but it doesn’t by itself demonstrate whole-building or system-level qualification. For example, a lighting replacement may be one part of a larger project; its treatment depends on the scope, performance evidence, and governing rules. Engineering and tax review help assess those facts without assuming an outcome.
Can an existing building use the same rules as new construction?
Not necessarily. Retrofit analysis must account for the building’s existing condition, project history, and any baseline or measurement requirements under the applicable pathway. New construction is assessed using the criteria that apply to that project type. Because statutory distinctions and effective dates can change, verify the rules for the construction start, placed-in-service date, and project pathway before calculating or claiming a deduction.
How to Prepare a 179D Retrofit Project for Technical and Tax Review
A well-organized project file makes it easier to evaluate whether retrofit work and building-performance evidence align with applicable 179D requirements. Prepare for review in sequence: define the scope, assemble records, assess energy data, analyze the relevant rules, and document the findings. This process can reveal missing information before technical conclusions or tax decisions are made.
Start by describing what changed, where the work occurred, and which building systems were affected. Then organize supporting records by system and project milestone. The 179D deduction for retrofits depends on project-specific facts, so a file that connects improvements to performance evidence is more useful than a folder of equipment specifications alone.
What records should owners assemble before a retrofit review?
Gather materials that establish both the building’s prior condition and the completed work. Useful records may include:
- Existing-building plans, renovation scope, and project specifications
- Equipment schedules, product information, invoices, and contractor documentation
- Utility consumption records for periods relevant to the applicable analysis
- Commissioning documents, project milestones, completion dates, and placed-in-service information
Keep records in a consistent timeline. For example, link an equipment schedule to the relevant invoice and completion record, then organize energy data by the periods needed for the analysis. This helps reviewers understand what was installed and when, while preserving information needed to assess building performance and current-law requirements.
How can engineering analysis strengthen the deduction file?
Engineering analysis connects the project record to the technical test. An engineer can review the affected systems, evaluate available energy evidence, identify gaps or inconsistencies, and explain how the methodology addresses the project’s facts. The analysis should be clear and reproducible, with calculations, assumptions, source records, and conclusions retained in the supporting file. That documentation makes the reasoning easier to follow, but it doesn’t guarantee eligibility or a particular deduction amount.
Coordinate technical conclusions with current tax guidance before determining treatment or filing. Review the related 179D guidance and verify applicable requirements for the project. A focused engineering study brings building records and performance analysis into one substantiated review.
Request a 179D engineering study to evaluate project documentation and technical evidence.
Plan a Defensible 179D Retrofit Review with Engineering Support
A strong review begins with a clear account of the building and the work performed. Establish the project scope and key dates, identify the systems affected, and organize energy-performance records. Then verify the law applicable to the tax year and project pathway before drawing conclusions. This sequence connects the technical analysis to the facts a tax review will need.
Engineered Tax Services (ETS) is an independent, licensed engineering firm that conducts 179D technical studies. Its engineering-based analysis and reporting connect project documentation with building-performance evidence and applicable technical requirements. ETS conducts over 10,000 tax studies annually. A study supports a disciplined review, but doesn’t guarantee eligibility or a particular tax outcome.
What does a 179D engineering study contribute?
A project-specific study evaluates building systems, available performance data, and records describing the retrofit. It documents the analytical approach, relevant assumptions, and conclusions so the relationship between project evidence and applicable requirements is clear. For the 179D deduction for retrofits, this technical file can support substantiation; it doesn’t replace current tax guidance or determine the final tax treatment.
What should owners do before taking a retrofit deduction?
Before considering a claim, organize project dates, building information, and relevant energy-performance records. Confirm that the technical analysis addresses the correct statutory pathway, then have the provisions and IRS guidance for the applicable tax year reviewed. Keep the supporting analysis and source documents together so the basis for the conclusions can be followed.
- Establish the facts: Identify the building, retrofit scope, key milestones, and placed-in-service information.
- Assemble the evidence: Bring together plans, equipment and project records, and relevant energy data.
- Verify the rules: Review current statutory provisions and IRS guidance for the project and tax year.
- Evaluate the study: Ensure the technical analysis explains its methods, evidence, and conclusions.
Engineering and tax review serve different purposes: engineering connects building evidence to technical requirements, while tax professionals consider how current law applies to claiming the deduction. A careful, project-specific review can clarify the documentation’s strengths and identify unresolved questions.
Explore ETS 179D engineering support to learn how technical study and reporting can support a retrofit review.
Move Forward with a Well-Supported 179D Review
The 179D deduction for retrofits isn’t established by an equipment upgrade alone. A sound evaluation starts with project dates and scope, then connects organized building records with the applicable energy-performance analysis and current requirements. Retrofit and new-construction pathways may rely on different facts, so confirm which rules apply before reaching a tax conclusion.
Keep the evidence together: plans, system specifications, utility data, invoices, and project milestones can help explain what changed and how performance was evaluated. A clear engineering study documents the technical approach and findings, supporting a more defensible review without guaranteeing eligibility or a particular tax outcome.
Engineered Tax Services is an independent, licensed engineering firm that conducts technical 179D analyses. ETS conducts more than 10,000 tax studies annually. For a project-specific review grounded in building evidence, explore ETS 179D engineering support. Precise records and careful analysis help you assess the opportunity with greater clarity.
Frequently Asked Questions
Can an existing commercial building qualify for the 179D deduction after an energy-efficient retrofit?
Yes, an existing commercial building may qualify if the retrofit meets applicable statutory and technical requirements. The 179D deduction for retrofits can involve an alternative pathway that evaluates reductions in the building’s energy use intensity under a qualified retrofit plan. The building’s history, project scope, performance records, and relevant dates all matter. An engineering analysis can assess the evidence, but eligibility depends on the specific project and current law.
What energy-efficiency improvements may qualify for a 179D retrofit deduction?
Improvements involving the building envelope, interior lighting, HVAC, and service-water heating may be candidates for evaluation. Examples include upgrades to insulation, lighting systems, heating or cooling equipment, and hot-water systems. These categories don’t make a project automatically eligible. The work must fit the applicable statutory definitions and pathway, and the technical analysis must evaluate the project scope and required energy-performance evidence.
How is energy-use reduction measured for a 179D retrofit?
Under the retrofit measurement pathway, analysis compares energy use intensity, or energy use relative to building floor area, before and after the improvements. A qualified retrofit plan and supporting energy records inform that comparison. The measurement periods and methodology must follow current requirements; a simple comparison of utility bills may not be sufficient. Verify the applicable standards and documentation rules for the project before relying on a calculated reduction.
Does every HVAC or lighting upgrade qualify for the 179D deduction?
No. Installing a more efficient HVAC unit or lighting system doesn’t establish eligibility by itself. The work must meet the applicable statutory pathway and technical performance requirements, supported by project-specific evidence. An equipment rating may document a product’s efficiency, but it doesn’t necessarily prove that the retrofit satisfies the required building-performance analysis. Review the complete project scope, energy data, and records before reaching a conclusion.
What documentation is needed to support a 179D retrofit claim?
Assemble records showing the building’s prior condition, the retrofit scope, completed work, and energy performance. Useful materials include existing and updated drawings, specifications, equipment schedules, invoices, contractor records, utility data, commissioning documents, and project completion or placed-in-service dates. Organize records by system and timeline so the technical analysis can connect improvements to performance evidence. The required documentation depends on the applicable pathway and current rules.
Can a building owner claim 179D for a retrofit completed in 2026?
Possibly, but completion in 2026 alone doesn’t determine eligibility. Under current 2026 law, projects that began construction after June 30, 2026, aren’t eligible; projects that began on or before that date may still qualify even if placed in service later. The project must also meet applicable technical and statutory requirements. Confirm how the construction-start rule applies to the project and tax year before claiming a deduction.
How does the 179D retrofit deduction differ from the deduction for new construction?
New-construction analysis evaluates a newly built project under the criteria applicable to that pathway. A retrofit review starts with an existing building and may use an alternative measurement pathway based on changes in energy use intensity. That makes building history, baseline data, the retrofit plan, and project dates especially relevant. The evidence and tests vary by pathway, so verify current requirements rather than applying new-construction assumptions to an existing building.
Who can claim or receive an allocation of a 179D deduction for a retrofit?
The owner of an eligible commercial building may claim the deduction if the project satisfies the requirements. For a government-owned building, the deduction may be allocated to the designer responsible for the energy-efficient design, such as an architect or engineer, under applicable rules. Allocation isn’t a general transfer available for every private-building retrofit. Confirm who is entitled to claim or receive an allocation based on ownership, project facts, and current law.
Contact Engineered Tax Services to request a 179D engineering study for your retrofit project.