Could an energy-efficient home qualify for a tax credit while its homeowner can’t claim it? That distinction is central to the 45L energy efficient home credit. It’s generally a project and claimant incentive, not a homeowner rebate. In most cases, the potential claimant is the builder or developer who constructed and owned the home during construction, rather than a general contractor or buyer.
It’s also a time-sensitive review. Under federal law changes enacted in July 2025, the credit generally applies to qualifying homes acquired on or before June 30, 2026. If your project may have met that deadline, a closer look at the facts can help determine whether it merits further analysis. The home’s type, applicable energy-efficiency certification, claimant’s role, and project timing all matter.
This guide explains who may claim the credit, which homes and certification pathways may qualify, and how builders, contractors, owners, and tax professionals fit into a review. It also covers which acquisition dates, third-party certification records, construction documents, and, where relevant, labor records to gather. An engineering-based study can help assess technical eligibility and organize substantiation, but eligibility and any tax result depend on the project facts and current requirements.
Key Takeaways
- The 45L energy efficient home credit depends on more than a home’s efficiency. Assess the claimant, qualifying unit, applicable standard, and supporting evidence together.
- Use third-party certification as project-specific substantiation, then confirm that its pathway matches the home and applicable program rules.
- Organize project records for a focused eligibility review, including construction details, certification materials, and relevant timing documentation.
- An engineering-based study can help evaluate technical evidence and organize documentation, but it doesn’t replace tax advice or establish eligibility on its own.
- Review the project with qualified tax and engineering professionals to identify unresolved eligibility questions before preparing a claim.
What Is the 45L Energy Efficient Home Credit & Who's It For?
Section 45L of the Internal Revenue Code provides a federal tax credit for eligible contractors who construct qualifying energy-efficient dwelling units. The 45L energy efficient home credit is tied to the home and the party entitled to claim it under current rules, not simply to the person who eventually lives there. It’s distinct from a homeowner rebate, a tax deduction, or a utility incentive, each of which has separate eligibility rules and claimants.
The credit’s requirements have changed over time. The Inflation Reduction Act of 2022 amended the credit as part of broader federal energy policy. Later legislation changed its timeline. Under the current rules described in this guide, qualifying homes must have been acquired on or before June 30, 2026. Project dates, claimant status, and technical substantiation are therefore central to any review.
Who may claim the 45L credit?
“Eligible contractor” is a tax-law term, not a label that automatically includes everyone involved in construction. Generally, the potential claimant is the person who constructed the home and owned it, with a basis in it, during construction. This is often the developer or builder. A general contractor may not qualify solely because it managed or performed construction, unless it also meets the ownership requirements.
Sale and lease arrangements can affect who claims and whether the relevant timing requirement is met. Buyers shouldn’t assume that purchasing an efficient home gives them a personal 45L claim. A homeowner may have separate incentives to investigate, but those aren’t the same as this contractor-focused credit. Confirm the claimant’s role and transaction details with a qualified tax professional before treating a project as eligible.
Which residential projects may be relevant?
The credit applies to qualifying dwelling units, and the project type affects which energy-efficiency requirements and certification pathways may apply. For example, single-family and multifamily homes are assessed under different program standards. A multifamily review may involve individual units as well as the project’s applicable certification and construction details. A single-family home follows its own pathway, and manufactured homes may have specific standards to check.
In practical terms, the 45L credit is a federal tax credit that an eligible contractor may claim for a qualifying energy-efficient dwelling unit when applicable statutory, timing, and certification requirements are met. This guide examines residential project questions, deadlines, technical standards, and records that can help substantiate a potential claim. Certification is important evidence, but it doesn’t by itself establish that the claimant or project meets every tax requirement.
How the 45L Energy Efficient Home Credit Works in 2026
A potential claim involves several connected checks, not just an energy rating. The project team must identify the eligible contractor and dwelling unit, establish that the home meets an applicable energy-efficiency pathway, obtain required third-party certification, and have the tax claim reviewed and reported under current rules. The IRS 45L credit guidance is the key reference for current federal requirements, including claimant eligibility and the tax form used to claim the credit.
Certification supports the technical part of the review. It doesn’t, by itself, confirm that the claimant meets the statutory definition, that the home satisfies all applicable requirements, or that the transaction falls within the credit’s timing rules. An engineering-based 45L tax-credit study may help assess project evidence and organize technical documentation, while tax professionals evaluate the tax treatment.
Which energy-efficiency standards should a project review?
ENERGY STAR and the Department of Energy’s Zero Energy Ready Home (ZERH) programs are relevant certification pathways, but the applicable standard depends on the dwelling type and project details. Single-family and multifamily homes may follow different requirements, and program versions can change. For example, current ENERGY STAR rules specify different pathways for certain homes based on permit date and home type. Confirm the standard and version that applied to the specific unit rather than assuming one certification qualifies every project.
Review the certification record alongside the home’s construction and permit information. Match the unit to the correct pathway and verify that certification was completed by a qualified third party. Treat the certification as substantiation to evaluate, not as a substitute for a full eligibility review.
Why does project timing matter in 2026?
The credit’s termination and transition rules make transaction dates especially important. Under current federal law, the 45L credit applies to qualifying homes acquired on or before June 30, 2026. Homes acquired after that date generally fall beyond the termination cutoff. The relevant event is acquisition, so don’t assume that construction completion or permit issuance alone preserves eligibility.
Document dates that help establish the project timeline, including construction and permit milestones, certification, and the sale or lease transaction. Have a tax professional determine which date controls for the specific facts and whether any transition rule applies. The eligible contractor’s tax year and reporting process also matter. Eligible contractors generally use IRS Form 8908 with their annual tax return. Verify current IRS instructions before filing, since technical qualification and proper tax treatment are separate parts of the analysis.
45L Eligibility: Correct the Homeowner Rebate Misconception
Buying an energy-efficient home doesn’t, by itself, give the buyer a personal claim to the 45L energy efficient home credit. The federal credit generally applies to an eligible contractor who constructed and owned the qualifying home, with a basis in it during construction. A buyer’s purchase and the contractor’s potential tax claim are separate matters.
The IRS outlines the federal rules in its 45L Energy Efficient Home Credit guidance. State, local, and utility incentives are separate programs, each with its own eligibility terms. Don’t assume an incentive advertised to homebuyers is part of 45L, or that a potential 45L claim establishes eligibility for a separate program.
Does a homebuyer receive the 45L credit?
Generally, an ordinary homebuyer doesn’t claim 45L just because the purchased home meets an efficiency standard. The potential claimant is usually the qualifying builder or developer, subject to the statutory requirements. Contracts, ownership structures, and development arrangements can complicate who constructed and owned a home. Have a qualified tax professional review unclear roles rather than relying on job titles alone.
What can prevent a project from qualifying?
Eligibility depends on a combination of facts, not a single label such as “green” or “energy efficient.” Use this comparison to identify what needs review:
| Review factor | Question to resolve |
|---|---|
| Potential claimant | Did the claimant meet the current eligible-contractor and ownership requirements? |
| Dwelling unit | Does the home fit the qualifying unit and project criteria? |
| Energy standard | Did it meet the applicable pathway for its type and relevant program version? |
| Timing | Was the home acquired within the period allowed under current law? |
| Evidence | Are certification and project records available to substantiate the facts? |
The credit generally applies to qualifying homes acquired on or before June 30, 2026. An acquisition after that date may put a project outside the credit’s time window, but the full project facts and any applicable transition rules should be checked against current law.
A standard mismatch, missing third-party certification, uncertain claimant status, or incomplete transaction records can raise eligibility or substantiation concerns. Incomplete files may make a potential claim harder to support, even if the home appears efficient. Treat each issue as a prompt for review, not an automatic conclusion. Qualified tax and engineering professionals can assess the project evidence and identify what remains unresolved.
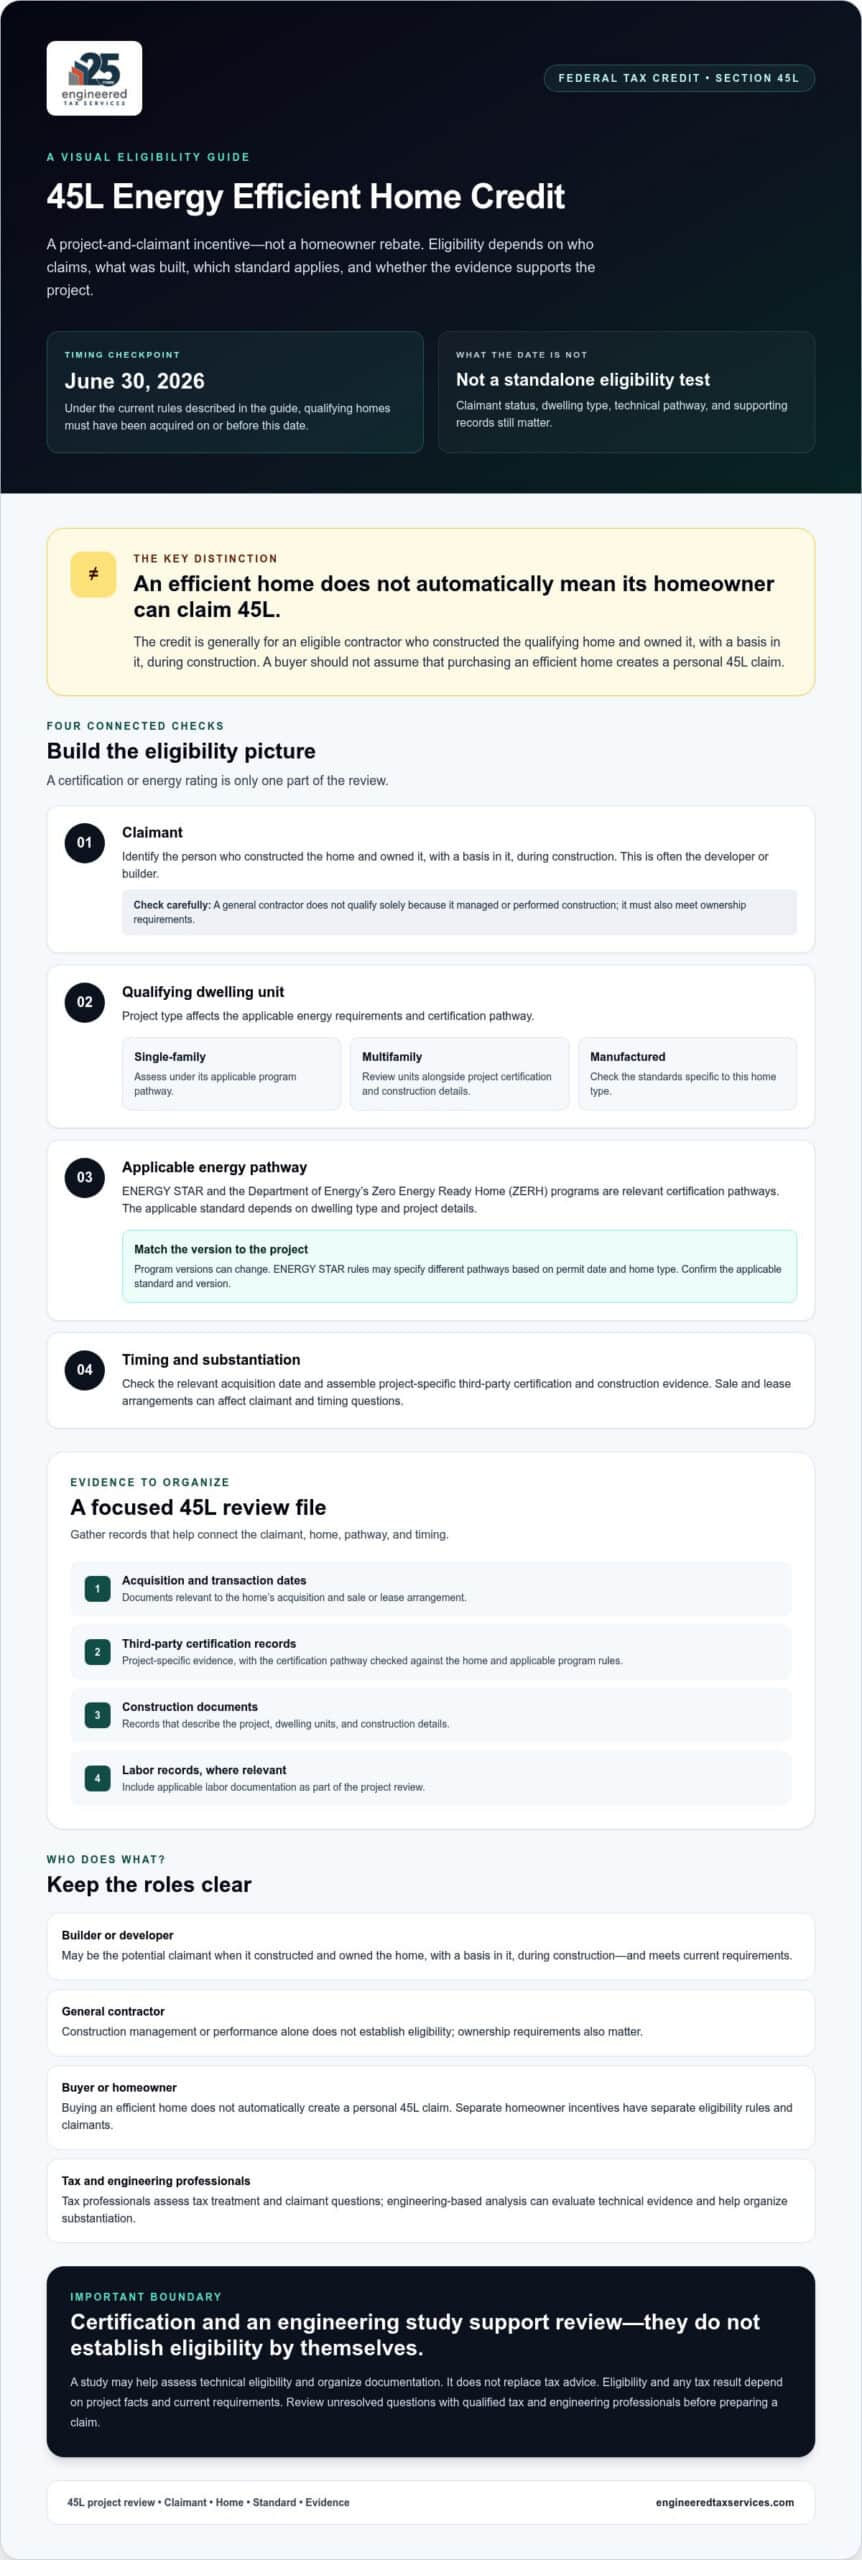
Build a 45L Eligibility and Documentation Checklist
A structured review helps project teams separate key facts from assumptions. Use this sequence to prepare for professional analysis of a potential 45L energy efficient home credit claim. A completed checklist is a starting point, not proof of eligibility.
- Identify the potential claimant. Record who constructed the home, who owned it during construction, and how each developer, builder, or contractor was involved.
- Define the project and units. Note the property type, number of dwelling units, and whether the review concerns single-family, multifamily, or manufactured homes.
- Match the energy pathway. Gather the certification and identify the applicable standard and program version for the home type and project period.
- Build the timeline. Assemble permit, construction, certification, sale, and lease dates. Ask a tax professional to determine which dates control and whether current termination or transition rules apply.
- Review the tax claim. Have the taxpayer’s tax professional assess statutory eligibility, reporting requirements, and the records needed for the return.
What project information should teams assemble?
Start with a unit schedule, ownership and development records, construction contracts, and documents identifying the parties responsible for building the homes. Collect permit and construction dates, sale or lease records, applicable third-party energy certifications, inspection records, building plans, and technical materials that support the claimed pathway. For multifamily projects, organize records by building and unit where applicable. Readers assessing those projects can also consult the dedicated 45L multifamily guide for project-specific considerations.
There isn’t one universal file list for every project. Confirm with the tax professional responsible for the claim which records are required, how they should be retained, and whether any gaps need follow-up. Keep source documents together with the project facts they substantiate.
How should teams review a potential claim?
Begin with the claimant and ownership facts, then assess the dwelling units, applicable energy criteria, certification, timing, and supporting evidence. Ask qualified engineering and tax professionals to validate the technical pathway, deadlines, and documentation sufficiency under current rules. An engineering review can assess energy-related evidence and prepare technical documentation. The taxpayer’s tax professional uses the relevant conclusions to evaluate and prepare the tax claim. Neither a checklist nor a study alone determines eligibility.
For an engineering-based assessment and supporting documentation, learn about ETS’s 45L study process.
Evaluate a 45L Claim with Engineering and Tax Professionals
A 45L review brings technical evidence and tax rules together. Engineering analysis can help assess whether a home’s documented characteristics align with the applicable energy-efficiency pathway and organize the records that support that assessment. Tax professionals then evaluate claimant eligibility, timing, and tax treatment. Coordinating these roles early can help developers identify missing information before a claim is prepared.
What an engineering-based 45L study can address
An engineering-based study may examine project characteristics, dwelling types, applicable technical standards, certification materials, and supporting construction records. Its scope depends on the project facts and applicable program requirements. For example, a team may need to clarify which certification pathway applies to a given unit or reconcile technical records across buildings in a multifamily development.
The study helps assess and document technical evidence. It doesn’t independently establish that the claimant meets the tax-law definition, determine every tax-return requirement, or guarantee a credit amount, eligibility, or IRS acceptance. Tax advice remains the responsibility of the taxpayer’s qualified tax professional.
What to ask before proceeding
Before beginning a review, align the project team, engineer, and tax professional on the questions the analysis is intended to address. Clarify:
- Which construction, permit, sale, or lease dates will be reviewed, and how will the tax professional assess the applicable deadline?
- Which dwelling types and project areas are included in the engineering review?
- Which energy certifications, inspections, plans, and technical records are available, and what additional documentation may be needed?
- Who will coordinate the engineering findings and supporting materials with the taxpayer’s tax professional?
Keep responsibilities clear. The project team can provide complete, organized records; engineers can assess energy-related evidence and prepare technical documentation; and the tax professional can determine how the project facts apply to the claim and tax return. This division supports a disciplined review of a potential 45L energy efficient home credit without treating a technical study as a tax conclusion.
Engineered Tax Services provides engineering-based 45L tax-credit studies and supporting reports. To discuss a project-specific review, request a discussion about ETS’s 45L study services.
Turn Project Records Into a Focused 45L Review
A potential 45L energy efficient home credit claim depends on the full picture: who may claim, whether each dwelling meets applicable efficiency and certification requirements, and whether project timing falls within current law. A home’s energy performance alone isn’t enough. Organized ownership, construction, certification, and transaction records help qualified professionals assess the facts.
The acquisition deadline has passed. Projects with homes acquired on or before June 30, 2026, may merit a timely review. Confirm the applicable rules and project dates with a tax professional, especially if ownership or transaction details are complex. Engineering analysis can help assess technical evidence and prepare supporting documentation, but it doesn’t determine tax eligibility or guarantee a result.
Engineered Tax Services provides 45L tax-credit studies and technical documentation, serves clients nationally, and conducts more than 10,000 tax studies annually. To discuss whether an engineering-based review fits your project, discuss a 45L study with Engineered Tax Services. A careful assessment can help your team move forward with greater clarity.
Frequently Asked Questions
What is the 45L energy efficient home credit?
The 45L energy efficient home credit is a federal tax credit for eligible contractors who construct qualifying energy-efficient dwelling units. It’s tied to the project and the claimant’s role, not simply to a homebuyer’s decision to purchase an efficient home. A qualifying claim depends on current tax rules, the home’s applicable energy-efficiency pathway, required certification, and timing. It isn’t a homeowner rebate or a deduction available just because a house uses less energy.
Who can claim the 45L tax credit?
Generally, the potential claimant is the person who constructed the home and owned it, with a basis in it, during construction. This is often the developer or builder, but a general contractor doesn’t qualify solely because it performed or managed construction. Ownership and project arrangements matter, so the party claiming should confirm that it meets the current eligible-contractor definition. A tax professional can review the facts and applicable reporting requirements, including Form 8908.
Can a homeowner claim the 45L energy efficient home credit?
Usually, buying an energy-efficient home doesn’t make the buyer eligible to claim 45L. The credit generally applies to an eligible contractor who constructed and owned the home during construction, rather than the person who later lives in it. A purchase contract or energy rating alone doesn’t establish a homeowner’s claim. Buyers should distinguish 45L from any separate federal, state, local, or utility incentive and check each program’s eligibility rules independently.
What energy-efficiency standards must a home meet for 45L?
The applicable standard depends on the dwelling type and project details. Potential pathways include relevant ENERGY STAR programs and the Department of Energy’s Zero Energy Ready Home program. Single-family, multifamily, and manufactured homes may follow different requirements, and program versions can change based on factors such as permit date. Required third-party certification helps document technical performance, but the claimant should verify that the specific home meets the pathway and all other current 45L requirements.
Is the 45L tax credit still available in 2026?
For homes acquired after June 30, 2026, the 45L credit is generally no longer available under the current termination rule. A qualifying home acquired on or before June 30, 2026, may still merit a claim review, subject to claimant, certification, and other statutory requirements, as well as applicable filing rules. Because this cutoff has passed, project teams should confirm the acquisition date and any relevant transition provisions with a tax professional.
What documentation is needed for a 45L credit claim?
Records commonly needed for a review include documents identifying the claimant’s construction and ownership role, unit and dwelling types, construction and permit dates, and sale or lease dates. Gather third-party energy certifications, inspection records, plans, and technical materials supporting the applicable efficiency pathway. The taxpayer’s tax professional should confirm what documentation and tax records are needed for the particular claim. A complete file supports review, but collecting documents alone doesn’t prove eligibility.
How can an engineering firm help with a 45L credit?
An engineering firm can assess home characteristics, applicable technical standards, certification materials, and project records, then prepare supporting technical documentation for a potential claim. Engineered Tax Services offers engineering-based 45L tax-credit studies and reports. ETS conducts more than 10,000 tax studies annually and serves clients nationally. An engineering study doesn’t guarantee eligibility, a credit amount, or IRS acceptance, and it doesn’t replace tax advice from the professional responsible for the claim.