What if cost segregation and bonus depreciation aren’t competing strategies, but two steps in the same tax-planning process? A bonus depreciation cost segregation analysis can identify building components that may qualify for shorter depreciation periods. Bonus depreciation may then accelerate deductions for eligible property. Under current federal rules, qualifying property acquired and placed in service after January 19, 2025, may be eligible for 100% bonus depreciation, subject to applicable requirements.
Which components qualify, when can deductions apply, and what records support the analysis? A building’s structural components don’t automatically qualify for shorter recovery periods just because a study identifies other assets. Accurate, property-specific classification matters.
This article explains the distinct role of each strategy, the property details and records that inform an evaluation, and the tax questions to consider for 2026. It also explains how engineering analysis supports asset classification and a documented depreciation study. The goal is to clarify potential deduction timing, not to assume every component qualifies or a particular deduction is guaranteed.
Key Takeaways
- Cost segregation classifies building components for depreciation; bonus depreciation may affect the timing of deductions for eligible assets.
- A bonus depreciation cost segregation evaluation shows how asset classification and tax treatment fit together, without assuming a study guarantees eligibility.
- Assess ownership, property use, basis records, project dates, and placed-in-service timing when screening a property.
- Engineering analysis supports property-specific asset classification, while thorough documentation helps substantiate the analysis for review.
Bonus Depreciation and Cost Segregation: What Each Strategy Does
Cost segregation and bonus depreciation are distinct strategies that can work together. Cost segregation is an engineering-based analysis that classifies building components for depreciation. Bonus depreciation is a tax rule that may allow a deduction for qualifying property to be claimed sooner. One informs how property is classified; the other affects when eligible costs may be deducted.
Both strategies operate within the federal depreciation framework, including the Modified Accelerated Cost Recovery System (MACRS). Asset eligibility and deduction treatment depend on current law and the taxpayer’s specific facts, including the property and its acquisition and placed-in-service dates.
What a cost segregation study identifies
An engineering review examines building costs, construction or acquisition records, and property components to support their depreciation classification. Some components may qualify as shorter-life property, while structural components generally remain in longer recovery-period categories. For example, a study may assess certain fixtures or site improvements separately from the core building structure. Classification depends on the asset’s characteristics and applicable tax rules, not simply where it is located within the property.
This distinction is central to cost segregation for commercial property: an engineering analysis supports a property-specific allocation, but it doesn’t establish that every component qualifies for a particular deduction.
What bonus depreciation changes
Bonus depreciation concerns deduction timing for property that meets applicable requirements. Under current federal rules, qualifying property acquired and placed in service after January 19, 2025, may be eligible for 100% bonus depreciation. The rate alone doesn’t determine eligibility. Property classification, transaction timing, and taxpayer-specific circumstances still matter, and state tax treatment may differ.
A deduction reduces taxable income; it isn’t the same as a tax credit, which generally reduces tax owed directly. Claiming a deduction doesn’t automatically produce a cash refund. Its effect on tax liability or cash flow depends on the taxpayer’s full tax picture.
Cost segregation identifies and classifies assets; bonus depreciation may accelerate deductions for qualifying assets. That distinction explains how bonus depreciation cost segregation works: the study informs asset classification, while tax rules determine whether and when deductions may be claimed.
How Bonus Depreciation and Cost Segregation Work Together
The strategies work in sequence, not as substitutes. First, an engineering analysis reviews the property’s costs and components. It supports the classification of assets into appropriate depreciation categories. Then the applicable tax rules are considered to determine whether any classified property may qualify for bonus depreciation and when a deduction may be claimed.
A study can identify components for separate tax analysis, but it doesn’t guarantee that they qualify for bonus depreciation. Eligibility depends on the asset, the transaction and project facts, and applicable law. This is the key to understanding bonus depreciation cost segregation: engineering findings inform classification, while tax treatment is determined separately.
From engineering analysis to tax-year treatment
Project records, construction documents, invoices, and property details help an engineering team analyze costs and support component-level allocations. The findings give the taxpayer and tax professional a more detailed picture of the property’s assets. The tax professional then applies the relevant depreciation rules to determine reporting and deduction timing.
Engineering analysis supports what the assets are and how costs are allocated; tax analysis determines how depreciation rules treat them. Keeping those roles distinct helps prevent study classifications from being mistaken for a final eligibility determination.
Why dates and property details matter
Dates can change the analysis. Review when the property was acquired, when construction or renovation occurred, and when the property or improvements were placed in service. Records should distinguish costs from the original acquisition and later work. The property’s use and the specific assets involved also matter.
For 2026, current federal law generally provides 100% bonus depreciation for qualified property acquired and placed in service after January 19, 2025. Don’t apply that rate automatically to every asset or project. Acquisition and placed-in-service requirements, exceptions, and transition rules can affect the outcome. Assess the applicable treatment against current rules and the taxpayer’s specific facts.
For example, an owner acquires a commercial property and later renovates part of it. An engineering review may identify certain components and allocate their costs separately from the building structure. A tax professional can then assess each classification under the rules applicable to the acquisition or improvement, including the relevant dates. The study informs that review, but it doesn’t promise a particular deduction.
For a property-specific assessment, explore engineering-based cost segregation analysis to support detailed asset classification and depreciation planning.
Does Bonus Depreciation Make Cost Segregation Unnecessary?
No. Bonus depreciation doesn’t identify or classify building assets. It governs the timing of deductions for property that meets applicable requirements. Cost segregation provides an engineering-based analysis of property costs and components, informing a broader depreciation review. The strategies answer different questions, so one doesn’t automatically replace the other.
Compare the strategies by function, not by label
Think of cost segregation as an asset-analysis step and bonus depreciation as a potential tax treatment applied after classification. Study findings may help distinguish components with different recovery periods, but they don’t establish that each asset qualifies for bonus depreciation. Tax treatment must be evaluated under current law and the taxpayer’s circumstances.
| Strategy | Purpose | Key input | Potential planning role |
|---|---|---|---|
| Cost segregation | Analyzes and classifies property components for depreciation. | Property details, cost records, and engineering findings. | May support a more detailed allocation of depreciable costs. |
| Bonus depreciation | Addresses deduction timing for qualifying property. | Asset classification, transaction and service dates, and applicable tax rules. | May allow an eligible deduction to be claimed sooner. |
In practice, a study’s classifications become one input to the taxpayer’s overall depreciation analysis, not a promise of a deduction or particular tax result. That distinction is central to evaluating bonus depreciation cost segregation accurately.
When the study’s value requires closer analysis
The analytical value of a study depends on the property and the quality of available information. A property with varied components, substantial improvements, or complex construction records may call for a more detailed review than a simpler asset profile. Acquisition, renovation, and placed-in-service timing also affect how costs and tax rules are considered.
Records matter. Invoices, construction documents, and details about property components help support an allocation. If records are incomplete or costs are difficult to distinguish, that may affect the scope and precision of the analysis. Classification should follow property evidence and applicable requirements, not an assumption about the result.
Taxpayer circumstances matter too. The ability to use deductions in a particular year may be affected by taxable income, business structure, passive activity limitations, and other applicable rules. Accelerated depreciation generally affects timing; it doesn’t automatically create additional depreciable basis or guarantee a better outcome for every taxpayer.
A sound evaluation asks whether property records support component-level analysis, which classifications are appropriate, which rules apply to the relevant dates, and how the taxpayer may use any resulting deductions. The review may reveal an opportunity, a limited benefit, or no material advantage. The goal is a documented, property-specific assessment, not an assumed savings outcome.
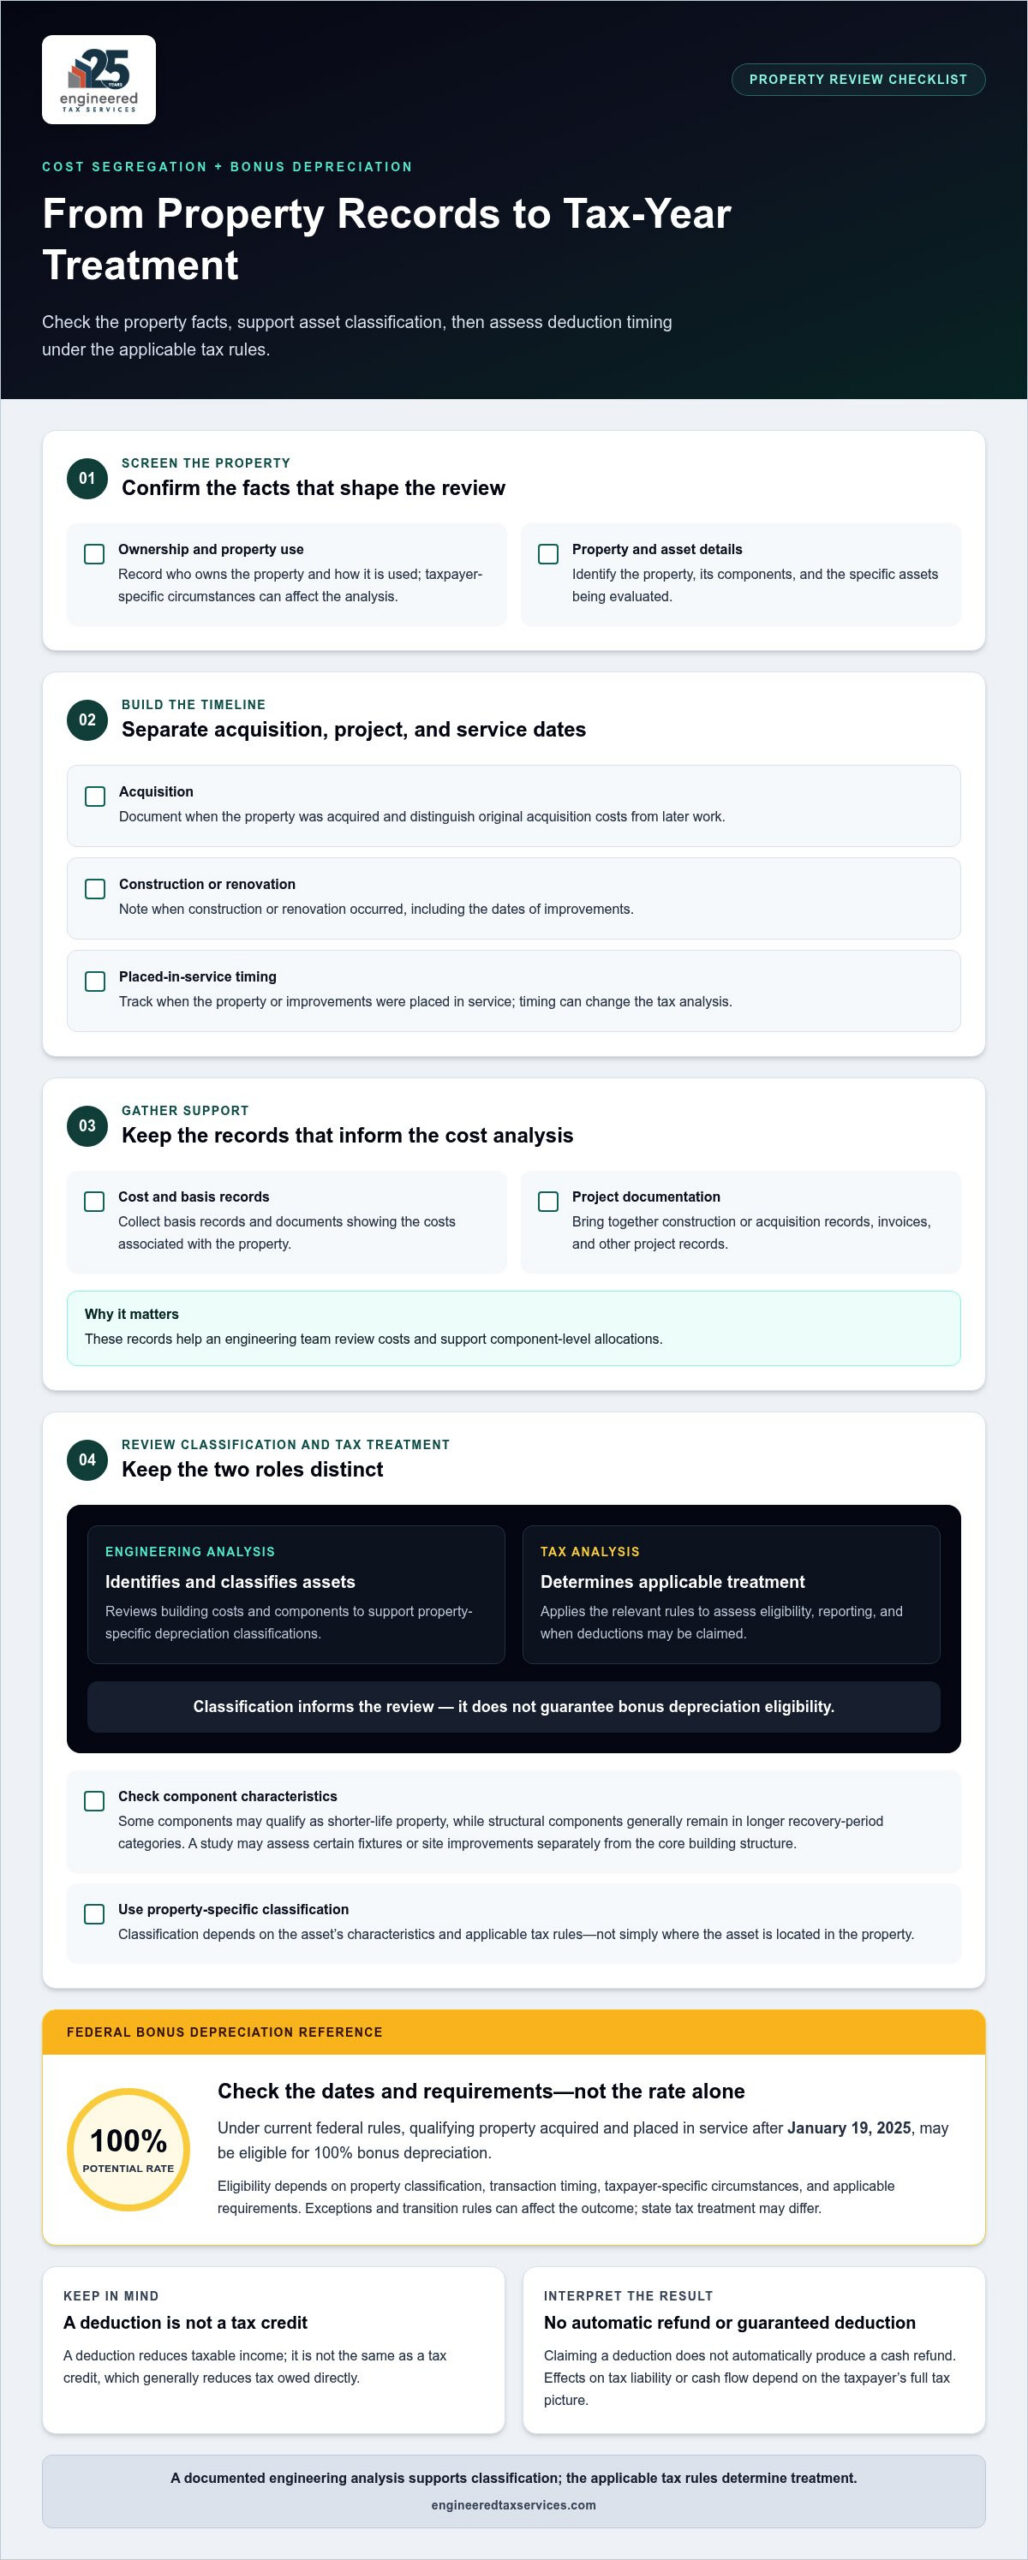
Evaluate a Property for Bonus Depreciation and Cost Segregation
A focused screening helps determine whether a property merits closer review without assuming a particular deduction or tax outcome. Use these four steps to organize the relevant facts for a bonus depreciation cost segregation evaluation:
- Confirm ownership and use. Identify the legal owner, ownership structure, and how the property is used. These details frame the taxpayer-specific analysis.
- Assemble basis records. Gather closing statements and records showing the property’s depreciable basis and how acquisition costs were allocated.
- Document project activity. Collect construction invoices, improvement records, and available plans. Where records allow, separate later renovation or construction costs from the original acquisition.
- Build a date timeline. Record acquisition, construction, renovation, and placed-in-service dates for the property and relevant improvements. These dates can affect which rules apply.
Gather the property and project records
Useful materials include closing documents, construction and contractor invoices, improvement records, and architectural or engineering plans. Add a concise summary of ownership, property use, acquisition date, and placed-in-service timing. Complete, organized documentation gives engineers a stronger factual basis for reviewing costs and components. If records are missing, note the gaps instead of filling them with assumptions.
Coordinate engineering findings with tax planning
An engineering study focuses on property details, cost allocation, and asset classification. It doesn’t replace tax-return preparation or legal advice. Once the analysis is complete, review its findings with the taxpayer’s qualified tax professional, who can assess current-year depreciation rules, transition provisions, and taxpayer-specific limits. For broader context, see this commercial real estate depreciation guide.
That coordination matters because component classification is only one part of the tax analysis. Treatment may depend on the property, relevant dates, the taxpayer’s circumstances, and current federal and state rules. For 2026 planning, assess the applicable rules and effective dates against current primary sources rather than relying on a general summary or prior-year assumption.
A well-prepared file helps the engineering review focus on property evidence and gives the tax professional useful information for evaluating the results. It also separates documented facts from estimates, an important step toward a supportable conclusion.
To evaluate property-specific depreciation opportunities, explore an engineering-based cost segregation study.
Use Engineering Analysis to Build a Defensible Depreciation Strategy
A depreciation analysis is only as reliable as the property facts and records behind it. Engineering expertise connects those records to the building’s actual components and supports a precise, property-specific classification for tax review. In a bonus depreciation cost segregation strategy, that technical foundation informs the next step without predetermining the tax outcome.
What an engineering-based study contributes
An engineering-based cost segregation study reviews available plans, cost records, and property components to evaluate how building costs may be allocated among asset categories. Plans and invoices provide context; examination of the property’s features helps relate documented costs to specific components. The analysis explains the basis for classifications and gives a tax professional organized information to consider when applying depreciation rules.
Supporting documentation makes the analysis traceable. It helps reviewers understand which records were considered, which components were analyzed, and how conclusions relate to the property. Documentation supports review, but it doesn’t guarantee that a tax authority will accept a position, prevent an examination, or establish that a component or taxpayer qualifies for particular treatment. Conclusions depend on the evidence, current law, and taxpayer-specific facts.
Plan the next step with Engineered Tax Services
Engineered Tax Services is an independent, licensed engineering firm specializing in cost segregation and other engineering-based tax studies. Founded in 2001, the firm serves property owners and investors nationwide and conducts over 10,000 tax studies annually. Its engineering analysis helps evaluate property-specific depreciation opportunities through detailed asset classification and supporting documentation.
The engineering study and tax application have distinct roles. A tax professional should review the findings alongside current depreciation rules, relevant dates, ownership and use, and the taxpayer’s circumstances. The analysis informs tax planning, but it doesn’t promise eligibility, a specific deduction, savings, or an audit outcome.
For property owners, a practical next step is to assemble available plans, cost records, and improvement documentation, then evaluate whether a detailed engineering review can clarify the property’s asset classifications. A careful assessment may identify relevant depreciation considerations or show that the available facts don’t support different treatment.
Explore an Engineered Tax Services cost segregation study to evaluate your property’s depreciation opportunities through documented engineering analysis.
Turn Property Analysis Into a Clearer Depreciation Plan
Cost segregation and bonus depreciation serve different purposes, but together they can inform a more complete depreciation strategy. An engineering study analyzes property costs and classifies components; applicable tax rules determine whether qualifying assets may receive accelerated deductions. The outcome depends on the property, its records and dates, current law, and the taxpayer’s circumstances.
A careful bonus depreciation cost segregation evaluation starts with evidence, including acquisition and improvement records, available plans, and placed-in-service details. Engineering documentation supports asset classification and gives a tax professional a stronger foundation for assessing treatment. It can’t guarantee eligibility, a specific deduction, or an examination outcome.
Engineered Tax Services is an independent, licensed engineering firm founded in 2001. The company conducts over 10,000 tax studies annually. Its engineering-based cost segregation studies help property owners and investors evaluate property-specific depreciation opportunities through technical analysis and documentation.
Explore Engineered Tax Services cost segregation studies to assess your property’s depreciation opportunities. Start with your acquisition, improvement, and property records to move into a focused engineering review.
Frequently Asked Questions
Is bonus depreciation available for real estate property in 2026?
Yes, certain real estate-related property may qualify for federal bonus depreciation in 2026. Under current federal law, qualified property acquired and placed in service after January 19, 2025, may be eligible for 100% bonus depreciation. This generally concerns qualifying components, not the building’s structural framework itself. Acquisition dates, placed-in-service timing, asset classification, transition provisions, and taxpayer circumstances can affect treatment, so assess the rules that apply to the specific property.
Can cost segregation and bonus depreciation be used together?
Yes. Cost segregation is an engineering-based analysis that identifies and classifies property components for depreciation. Bonus depreciation is a tax rule that may affect deduction timing for qualifying assets. A study informs asset classification, after which a tax professional assesses whether the assets meet current requirements. The combination doesn’t guarantee eligibility or a particular deduction; property records, dates, use, and taxpayer-specific facts all matter.
Does bonus depreciation make a cost segregation study unnecessary?
No. Bonus depreciation doesn’t classify building components or allocate property costs. A cost segregation study provides engineering analysis of the property and supports the classification of assets into appropriate depreciation categories. Those findings inform a tax professional’s review of applicable depreciation rules. Whether a study is useful depends on the property, available records, applicable law, and the taxpayer’s circumstances. Don’t assume it will produce an additional deduction or favorable result.
What property can qualify for bonus depreciation after a cost segregation study?
A study may identify components for separate analysis, such as certain equipment, fixtures, or site improvements, but classification alone doesn’t establish bonus depreciation eligibility. The asset must meet applicable requirements, which can depend on its recovery period, acquisition date, and placed-in-service date. The building’s structural components generally don’t qualify for bonus depreciation. A tax professional should assess each classification under current rules and the taxpayer’s specific facts.
How does a cost segregation study affect depreciation deductions?
A cost segregation study analyzes property costs and may support allocating some basis to components with shorter depreciation recovery periods rather than treating all costs as part of the building. That classification can affect when depreciation deductions are claimed. Bonus depreciation may further accelerate deductions for assets that qualify under current rules. A study doesn’t increase the property’s total basis or guarantee a deduction; results depend on substantiated costs and tax treatment.
What records are needed for a cost segregation and bonus depreciation analysis?
Gather closing statements, purchase and basis records, construction invoices, improvement documentation, and available building plans. Also note the ownership structure, property use, acquisition and renovation dates, and when the property or improvements were placed in service. These materials help engineers evaluate costs and components, then enable a tax professional to assess the findings under relevant rules. Organized records support a more informed review, but don’t guarantee eligibility.
Can a real estate investor claim bonus depreciation if the property has rental income?
Rental income alone doesn’t determine whether an investor can claim bonus depreciation. The property and assets must meet applicable requirements, and ownership, use, acquisition and placed-in-service dates, and the investor’s tax situation affect the analysis. Individual investors may also face passive activity loss limitations that restrict how deductions offset other income. A tax professional can assess how the rules apply to the investor’s circumstances and whether deductions can be used in the relevant year.