What if the right energy incentive for your business depends less on the equipment you install and more on when the project began, who claims the benefit, and what you can document? For energy efficiency tax credits for businesses 2026, those details matter: some federal deadlines have passed, while other incentives follow different timelines.
The options can be confusing. A tax credit reduces tax liability, while a deduction lowers taxable income. Eligibility may depend on the project, claimant, timing, labor standards, and technical evidence. A building upgrade, energy-efficient housing project, or clean electricity investment may point to different pathways, and a familiar incentive may not apply because of the project’s timing.
This guide explains how to identify potentially relevant federal incentives, compare project fit and claimant requirements, and organize documentation for review. It also highlights what to verify with tax and engineering professionals, including current IRS guidance, certification requirements, and transition deadlines. A clear project and deadline map can help you focus your review without assuming eligibility or a particular tax outcome.
Key Takeaways
- Assess energy efficiency tax credits for businesses 2026 by matching each potential incentive to the project, claimant, and applicable requirements.
- Compare credits, deductions, grants, and utility-bill savings as distinct benefits, not interchangeable forms of support.
- Review 179D separately as a commercial building deduction, and verify current rules before relying on it.
- Organize plans, specifications, contracts, invoices, construction dates, and equipment schedules for professional review.
- If a project appears relevant, consider whether an ETS 179D or 45L study or engineered incentives report fits the technical review needed.
Energy efficiency tax credits for businesses in 2026: start with the project
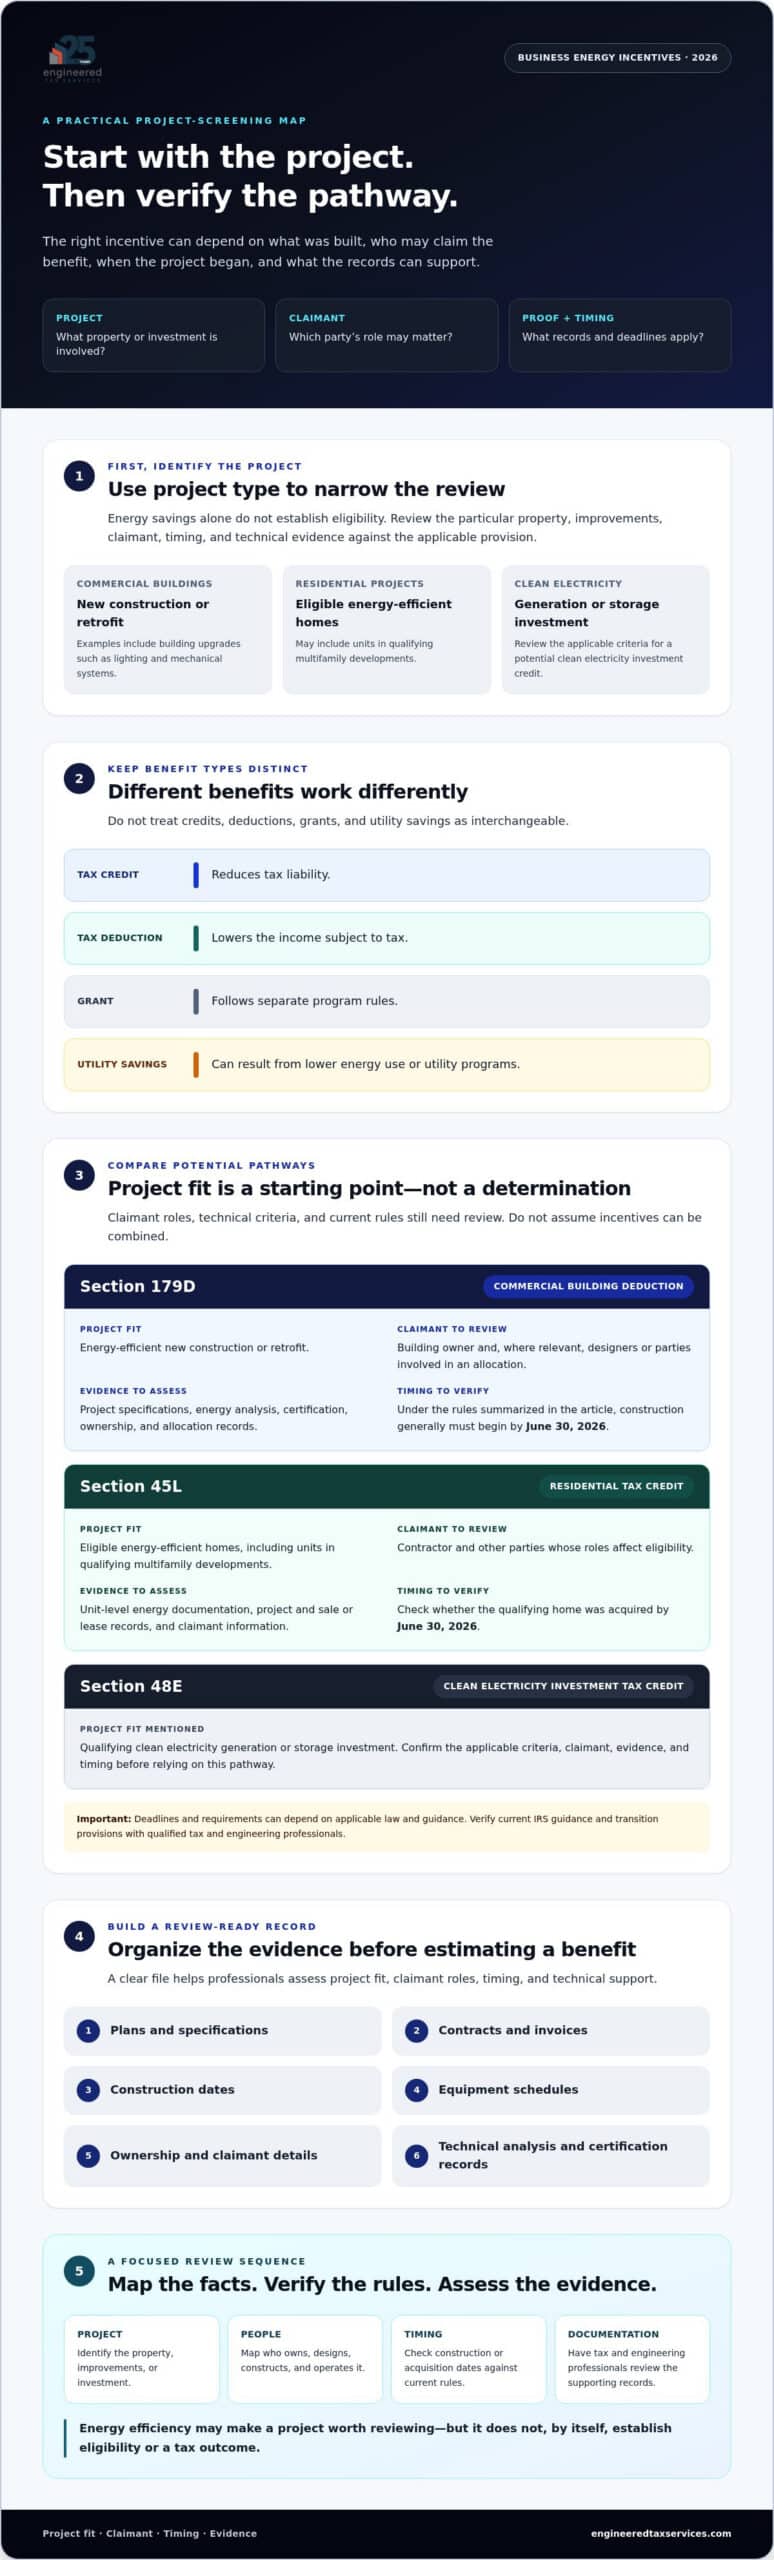
“Energy efficiency incentive” can refer to several types of support, each with different rules. For energy efficiency tax credits for businesses 2026, start with the project itself. Federal tax provisions may set requirements based on the property, improvements, claimant, project timing, and technical evidence. Lower energy use can benefit operations, but it doesn’t by itself establish eligibility for a tax provision.
Keep the benefit types distinct. A tax credit reduces tax liability; a tax deduction reduces the income subject to tax. Grants follow separate program rules, while utility-bill savings result from lower energy consumption or utility programs. Each may have its own administrator, application process, and requirements, so don’t treat one as a substitute for another.
For example, Section 179D is a commercial building deduction, while Section 45L is a tax credit for eligible contractors connected to qualifying energy-efficient homes. Section 179D has historical roots in the Energy Policy Act of 2005, but its current requirements depend on applicable law and guidance. Under the 2026 rules outlined here, construction generally must begin by June 30, 2026, for 179D, while a qualifying home must be acquired by that date for 45L. Confirm current rules and transition provisions before relying on either pathway.
What counts as a business energy efficiency incentive?
Distinguish federal tax provisions from state incentives, utility programs, grants, and operating savings. Each has its own eligibility test and process. A project that uses less energy may be worth reviewing, but qualification depends on the particular provision, property, claimant, timing, and evidence. Identify the relevant pathway before estimating a potential benefit.
Which business projects should be reviewed first?
Start by screening commercial building upgrades and new construction. Then consider residential developments that may include eligible homes. Identify who owns, designs, constructs, and operates the property. The party responsible for the work may not be the party eligible to claim a tax benefit. These roles help frame the review, but don’t establish eligibility by themselves.
For example, a company renovating an office building with new lighting and mechanical systems has a reason to examine 179D, but the improvements alone don’t prove the deduction is available. Review the building and project against current requirements, determine who may claim the benefit, check construction timing, and assess whether the technical evidence supports the analysis. Starting with these facts makes the next step more focused.
Compare 2026 business energy incentives by project and benefit type
Use the project type to narrow the options, then check who may claim a benefit and what evidence supports it. This table is a screening tool, not a determination of eligibility. Rules and deadlines vary by provision, and don’t assume that potential incentives can be combined.
| Provision | Benefit type | Project fit | Claimant to review | Evidence to assess | 2026 status to verify |
|---|---|---|---|---|---|
| Section 179D | Commercial building deduction | Energy-efficient new construction or retrofit | Building owner and, where relevant, designers or parties involved in an allocation | Project specifications, energy analysis, certification, ownership, and allocation records | For the rules summarized here, construction must begin on or before June 30, 2026. Confirm timing and current requirements with the IRS guidelines on the 179D deduction. |
| Section 45L | Residential energy-efficiency tax credit | Eligible energy-efficient homes, including units in qualifying multifamily developments | Contractor and other parties whose roles affect eligibility | Unit-level energy documentation, project and sale or lease records, and claimant information | Verify current criteria and whether the home was acquired by June 30, 2026. |
| Section 48E | Clean electricity investment tax credit | Qualifying clean electricity generation or storage investment | Project owner or other potentially eligible claimant | Investment, construction, and placed-in-service records, plus any applicable bonus-credit support | Check the technology-specific phase-out, construction dates, and any bonus requirements under current law. |
| State or utility programs | Program incentive or bill savings | Projects covered by a particular jurisdiction or utility offering | Customer, property owner, or other party identified by the program | Program terms, project scope, utility account, invoices, and application records | Confirm availability, application windows, and whether the program can interact with federal benefits. |
When might the 179D deduction warrant review?
Consider reviewing a commercial building project when new construction or a retrofit includes energy-related improvements. Don’t focus only on the building owner: ownership, designer roles, allocation arrangements, project timing, and technical performance may all affect the analysis. For detailed criteria, consult the 179D energy-efficient commercial building deduction guide and verify the applicable rules before proceeding.
When might the 45L credit warrant review?
Section 45L concerns qualifying residential units, not every commercial building. A multifamily development may warrant review, but the contractor’s role, unit qualifications, acquisition timing, and supporting records matter. See the 45L tax credit guide for multifamily developers for a focused discussion, and confirm claimant eligibility and current requirements for the specific project.
For energy efficiency tax credits for businesses 2026, compare project facts before comparing dollar benefits. Incentives may have interaction rules, and don’t assume the same expenditure can support multiple claims. A technical study can help assess and document project-specific engineering facts. Businesses considering that review can explore engineered incentives reports as a potential technical resource.
Address the biggest misconception: energy efficiency does not guarantee eligibility
A building that uses less energy may be a strong operational improvement, but energy performance alone doesn’t establish qualification for a federal tax provision. Each incentive has its own statutory test. Project type, property, construction or acquisition dates, claimant status, technical results, and records can all affect the outcome. For energy efficiency tax credits for businesses 2026, treat potential eligibility as a documented analysis, not an assumption based on lower utility use.
Why a qualifying project and a qualifying claimant are different questions
Separate what the project achieves from who may claim a benefit. A building might meet technical criteria, but ownership, allocation arrangements, and the roles of the owner, designer, contractor, and other parties may affect which taxpayer can claim an incentive. Confirm those relationships under the current provision. Don’t infer claimant eligibility from involvement in the project alone.
| Provision | Potential benefit | Key limitation | Facts for professional review |
|---|---|---|---|
| 179D | Deduction for eligible commercial building projects | The 2026 rules summarized here specify a minimum 25% projected reduction in annual energy and power costs against a reference building, with construction beginning on or before June 30, 2026. | Building and systems, energy analysis, certification, construction-start evidence, ownership, and any allocation. Review the 179D Energy Efficient Commercial Buildings Tax Deduction information from the Department of Energy alongside current IRS guidance. |
| 45L | Credit for eligible contractors tied to qualifying energy-efficient homes | Energy-efficient design alone doesn’t establish that a dwelling unit or claimant qualifies. The 2026 rules summarized here include a June 30, 2026 acquisition deadline. | Unit type, certification and energy records, contractor role, sale or lease date, and applicable requirements. |
| 48E | Investment tax credit for qualifying clean electricity projects | Eligibility and credit level depend on project requirements, technology, timing, and any applicable bonus conditions. | Qualified investment, construction and placed-in-service dates, technology, and documentation for claimed conditions. |
Why 2026 deadlines and rule changes need primary-source review
Dates are not interchangeable. Depending on the provision, construction start, completion, placed-in-service, or home acquisition may control. The 2026 guidance summarized here lists June 30, 2026, as a key date for 179D and 45L. Because that date has passed, confirm any applicable transition rule before relying on it. Check current IRS guidance and legislation for the project’s tax year, then ask tax and engineering professionals to assess the facts and evidence. A potential fit is a reason to investigate, not confirmation that a benefit remains available or can be claimed.
Prepare a defensible business energy incentive review
A focused review starts with the project record, not a tax form. Organize the facts so engineering and tax professionals can assess technical requirements, claimant eligibility, timing, and documentation under current rules. Evidence needs vary by provision and project, so treat this checklist as a starting point rather than a universal standard.
- 1. Identify the project. Describe the property, work performed or planned, affected systems, and relevant construction, completion, or placed-in-service dates.
- 2. Confirm the parties. Record who owns the property and who designed, constructed, or operates it. Note allocation arrangements or other project roles that may affect who can claim a benefit.
- 3. Check current rules. Identify the potential incentive, then verify its 2026 availability, deadlines, transition provisions, claimant requirements, and technical criteria against current primary sources.
- 4. Collect project records. Assemble relevant plans, specifications, contracts, invoices, equipment schedules, cost records, and timeline documentation. Include prior incentive claims or related funding for review of possible interactions.
- 5. Obtain a coordinated review. Ask an engineering professional to assess technical findings and supporting evidence, then coordinate with the taxpayer’s qualified tax professional on eligibility and filing treatment.
What project information should a business assemble?
Start with property ownership records and a clear list of project participants, including relevant designers and contractors. Gather available plans, specifications, equipment records, project costs, and dated documents showing the project timeline. If the business has received other incentives or funding, record the details for review. Missing documents don’t automatically determine the outcome, but identifying gaps early can help focus follow-up.
How should technical and tax review work together?
Engineering analysis can support technical findings, such as project characteristics or energy performance, and help organize incentive documentation. It doesn’t replace tax advice or tax return preparation. The taxpayer’s qualified tax professional should assess how the findings apply to the claimant, current eligibility rules, and filing treatment. Confirm documentation standards for the specific provision before relying on a study or report.
For a project-specific technical review, you can discuss an engineering-based incentive review with Engineered Tax Services. Its 179D and 45L studies and engineered incentives reports may be relevant when the project facts align. They don’t guarantee qualification or a particular tax result.
Turn a potential 2026 incentive into a clear next step with ETS
A disciplined review follows a clear sequence: identify a potentially relevant project, verify current law and dates, assemble supporting records, and determine whether technical analysis is needed. This matters for energy efficiency tax credits for businesses 2026 because project timing and claimant details can shape whether an incentive warrants further review.
Engineered Tax Services (ETS) is an independent engineering firm offering 179D and 45L incentive studies and engineered incentives reports. These services may be relevant when a project’s facts align with the requirements under review. ETS can assess and document engineering-related findings, but it doesn’t provide standard income tax filing or legal representation in tax court. A study doesn’t guarantee qualification, a particular filing position, or a tax result.
What an engineering-based incentive study can contribute
An engineering-based study can examine project information against the technical criteria of a potential incentive and help organize findings in a report. Depending on the project and provision, the work may involve reviewing building or unit characteristics, systems, specifications, and other supporting records. Technical analysis is one part of the review. Tax treatment, legal opinions, and any agency determination are separate matters.
Coordinate the analysis with the business’s qualified tax professional, who can consider the taxpayer’s circumstances and filing treatment. Confirm applicable rules and documentation standards before relying on the report.
Questions to ask before engaging a study provider
Ask how the provider will evaluate project-specific facts, document technical conclusions, and identify assumptions or missing records. Clarify the scope of work and how findings can be coordinated with your tax and legal advisors. Ask how the review will address current-law requirements and relevant project dates. Specific answers help you decide whether the proposed technical work matches the question your business needs to resolve.
Engineered Tax Services was founded in 2001 and conducts over 10,000 tax studies annually. If your project may warrant technical analysis, explore an engineering-based incentive review. Share the project facts and available documentation so the appropriate scope can be considered, without assuming the incentive is available or that the project will qualify.
Make your next incentive decision project-specific
A useful review of energy efficiency tax credits for businesses 2026 begins with the project, not the assumption that energy savings automatically qualify. Compare the potential provision with the property, claimant, timing, and technical evidence, then verify current law and deadlines before acting. Plans, specifications, costs, and project dates can help tax and engineering professionals focus their review.
Engineered Tax Services is an independent engineering firm offering 179D and 45L studies and engineered incentives reports. It conducts over 10,000 tax studies annually. Engineering analysis can help assess and substantiate relevant technical findings, while tax filing decisions should be coordinated with your qualified tax professional. No study can guarantee eligibility or a particular tax outcome.
If your project may warrant technical analysis, explore an engineering-based incentive review. A careful, evidence-led review can help you evaluate the opportunity with greater clarity.
Frequently Asked Questions
What energy efficiency tax credits are available to businesses in 2026?
Potential federal incentives depend on the project, claimant, and current law, and not every benefit is a tax credit. Section 179D is a commercial building deduction, while Section 45L is a credit related to qualifying energy-efficient homes. Other clean energy provisions may apply to particular investments. As of September 2026, some incentive deadlines have passed, so verify each provision’s 2026 status, effective dates, claimant rules, and documentation requirements using current primary sources and with a qualified tax professional.
Is the 179D deduction a tax credit?
No. Section 179D is generally described as a deduction for qualifying energy-efficient commercial building property, not a tax credit. A deduction reduces taxable income; a credit reduces tax liability. Whether 179D applies depends on the building and project, the taxpayer or other potential claimant, timing, and technical requirements. Confirm current eligibility, transition provisions, and calculation rules with official guidance and a qualified tax professional before taking a tax position.
Can a business claim both 179D and 45L?
Possibly, but don’t assume both provisions can be claimed for a project or that benefits can be combined. Section 179D concerns qualifying commercial building property; Section 45L relates to qualifying residential units. The answer depends on project facts, claimant status, ownership or allocation arrangements, timing, and applicable interaction rules. Ask a qualified tax professional to review the specific circumstances and current law before claiming either provision or treating both as available.
How do businesses qualify for energy efficiency tax incentives?
Businesses qualify by meeting the specific statutory and technical requirements of a particular incentive, not simply by reducing energy use. For energy efficiency tax credits for businesses 2026, identify the property and project, determine who may claim the benefit, and check current criteria and relevant dates. Assemble supporting records and seek project-specific engineering and tax review. Requirements vary, so a general checklist or efficient equipment alone can’t confirm eligibility.
What documentation should a business keep for an energy efficiency tax claim?
Useful records may include property ownership and project-role details, plans, specifications, equipment schedules, contracts, invoices, construction or acquisition dates, and prior incentive claims or related funding. The evidence required depends on the provision and project, so this isn’t a universal checklist. Preserve source documents and ask engineering and tax professionals what technical substantiation, filing support, and record-retention practices apply to the specific claim under current rules.
Do energy-efficient products automatically qualify a business for a tax credit?
No. An efficient or certified product may help document a project’s technical characteristics, but it doesn’t by itself establish that the property, taxpayer, or project meets a tax provision’s requirements. Eligibility may also depend on project type, timing, claimant status, and other statutory conditions. Before treating a purchase as qualifying, identify the specific incentive and confirm its current rules and evidence requirements with qualified professionals.
Should a business use an engineering firm for an energy tax incentive study?
An engineering firm may help evaluate project characteristics and prepare technical analysis or documentation for a relevant incentive. That work doesn’t guarantee eligibility or replace tax return preparation, tax advice, or legal representation. Ask about the study’s scope, assumptions, records needed, and coordination with your tax professionals. Engineered Tax Services offers engineering-based incentive studies related to 179D and 45L, as well as engineered incentives reports.
To discuss a project-specific technical review, contact Engineered Tax Services about an engineering-based incentive review.