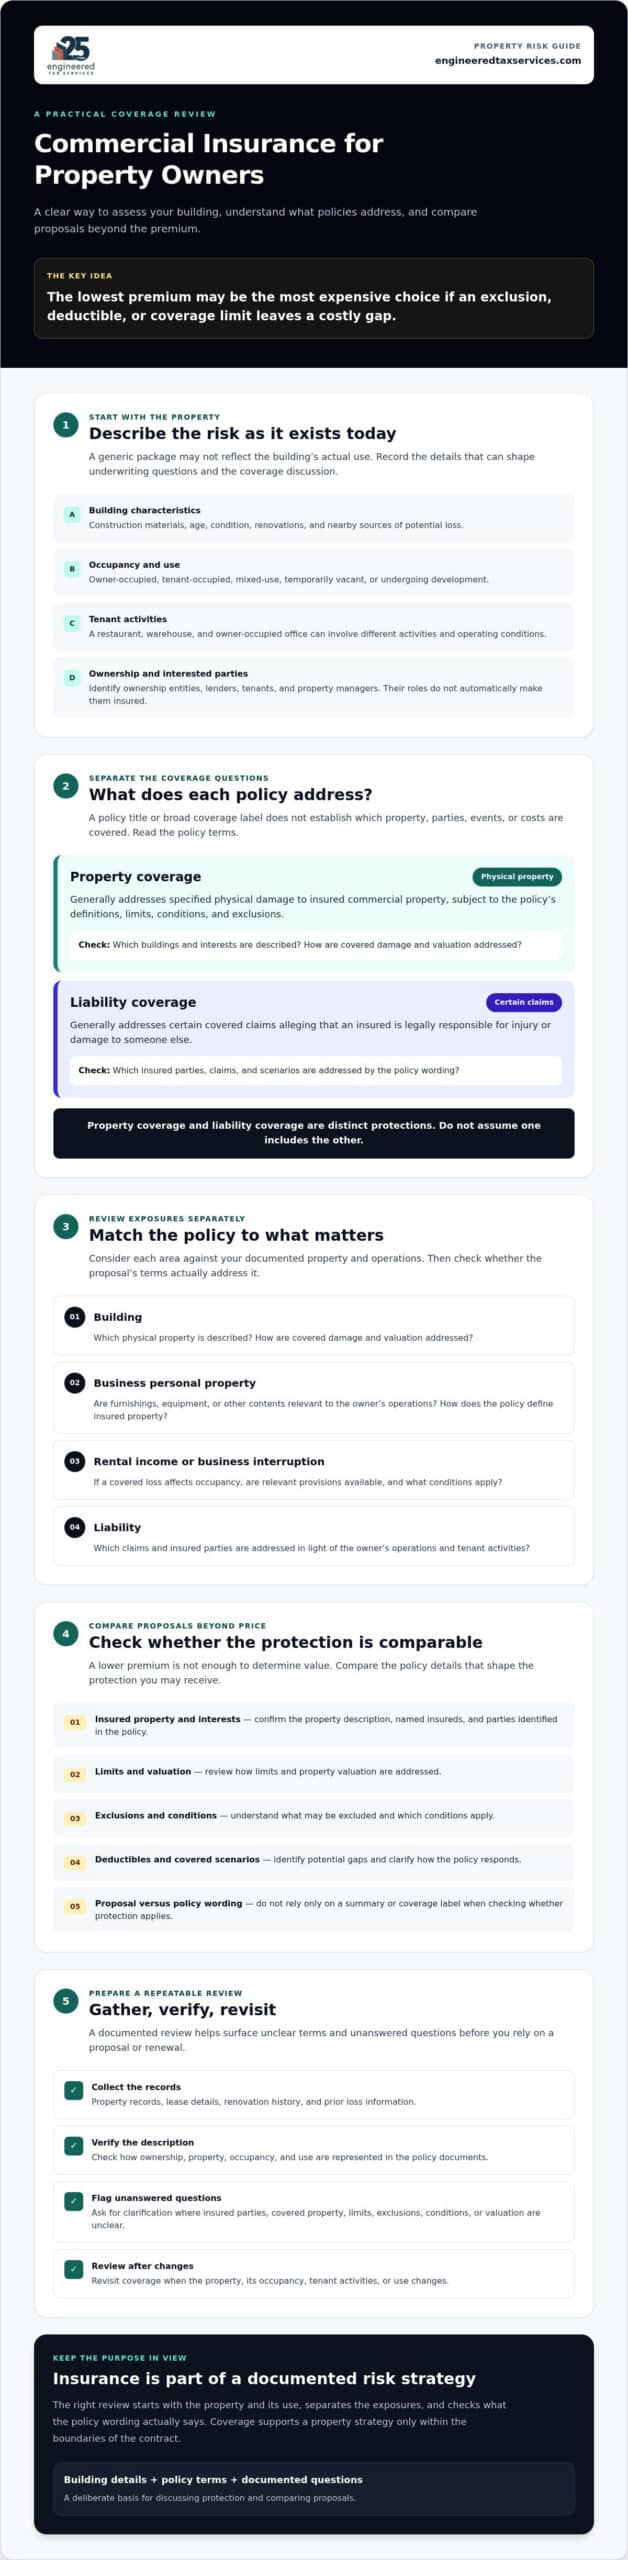
The lowest premium may be the most expensive choice if an exclusion, deductible, or coverage limit leaves a costly gap. When comparing commercial insurance for property owners, start by understanding how each policy responds to the building, its use, and the risks it faces.
It can be difficult to tell which coverages apply, what exclusions mean in practice, or whether competing proposals offer comparable protection. Price matters, but policy wording and the details insurers use to assess a property can shape the protection you actually receive.
This 2026 guide explains common commercial property and liability coverages, what to compare in proposals, and questions to ask when reviewing a policy or renewal. It also outlines how property use, valuations, maintenance, and risk mitigation can inform a more deliberate insurance discussion. Treat coverage as part of a documented risk strategy, not simply a policy purchase. Engineered Tax Services offers commercial insurance for property owners seeking a tailored risk-management conversation.
Key Takeaways
- Use the building’s construction, occupancy, tenant activities, and condition to identify risks that need closer review.
- Assess commercial insurance for property owners by checking what each policy insures, including the interests, limits, exclusions, and conditions in its wording.
- Gather property records, lease details, renovation history, and prior loss information before discussing coverage.
- Use a repeatable review process to flag unanswered questions and revisit coverage when the property or its use changes.
Commercial Insurance for Property Owners: What Does It Protect?
Commercial insurance isn’t one universal policy. It can include different coverages for property and business exposures, with the appropriate combination depending on the owner’s circumstances and the policy terms. A building policy may address physical damage to insured property, while liability coverage addresses certain claims alleging that an insured is responsible for injury or damage. Don’t assume one includes the other.
Commercial property insurance covers specified physical damage to insured commercial property, subject to the policy’s definitions, limits, conditions, and exclusions. A policy’s title alone doesn’t establish which buildings, interests, events, or costs are covered. Foundational concepts such as named and open perils, replacement cost, and actual cash value are discussed in Property insurance, but the policy documents determine how coverage applies to a particular risk.
Start by listing the property and the parties with an insurable interest in it. Ownership entities, lenders, tenants, and property managers may have different roles or interests, but their status doesn’t automatically make them insured under a policy. Check the named insureds and how the policy describes the covered property. If the ownership entity or property description is unclear, ask for clarification before relying on the coverage.
Which property owners may need commercial coverage?
Owners, investors, developers, and entities holding income-producing or business-use property may need to consider commercial coverage. The right approach depends on ownership structure, occupancy, tenant activities, and building use. A vacant property, a multi-tenant building, and a site undergoing development can raise different underwriting questions. Describe how the property is owned, occupied, and used rather than assuming one package suits every asset.
What is the difference between property and liability coverage?
Property coverage generally addresses covered physical damage to property identified by the policy. Liability coverage generally addresses certain covered claims alleging that an insured is legally responsible for injury or damage to someone else. These are distinct protections, and whether either applies depends on the policy language and circumstances. Check definitions, insured parties, limits, exclusions, and covered scenarios in the policy documents instead of relying only on a proposal summary or coverage label.
This distinction offers a practical starting point for commercial insurance for property owners: identify the asset and the parties involved, then check which policy terms address the exposures you want to manage. Clear documentation makes it easier to spot unanswered questions and compare proposals. Coverage can support a property strategy, but only within the boundaries set by the contract.
Match Commercial Property Insurance to the Risks Your Building Faces
Begin with the building as it exists today, not with a generic coverage package. Construction materials, age and condition, occupancy, tenant activities, renovations, and nearby sources of potential loss help frame the discussion. A building with a restaurant tenant, for example, has different activities and operating conditions from a warehouse or an owner-occupied office. Give the insurer accurate details, since underwriting and policy terms influence which risks may be accepted and how a covered loss is handled.
Evaluate coverage against documented exposures, not a standard package or a broad label. Record the building’s characteristics and use, then consider the property, contents, income continuity, and liability separately. This helps you ask whether the proposal addresses each relevant exposure instead of assuming one coverage handles them all.
- Building: Which physical property is described, and how are covered damage and valuation addressed?
- Business personal property: Are furnishings, equipment, or other contents relevant to the owner’s operations, and how does the policy define insured property?
- Rental income: If a covered loss affects occupancy, are rental-income or business-interruption provisions available, and what conditions apply?
- Liability: Which claims and insured parties are addressed, considering the owner’s operations and tenant activities?
How do occupancy and tenant activities change the review?
Owner-occupied, tenant-occupied, mixed-use, and temporarily vacant buildings can raise different underwriting questions. A change in use, an empty unit, or a tenant’s activity may affect how a risk is assessed and whether policy terms remain appropriate. Describe current and planned occupancy accurately, and review lease language to understand how insurance responsibilities are allocated. For interpretation of lease obligations, consult an appropriate legal professional.
Which loss scenarios should owners ask about?
Ask how the policy addresses relevant physical-loss scenarios, such as fire, water damage, and severe weather. The answer may depend on how a cause of loss is defined, as well as exclusions, deductibles, limits, and conditions. If income continuity matters, ask specifically about rental-income or business-interruption provisions, including any waiting periods and the circumstances that trigger them. The New Hampshire Insurance Department’s property and casualty insurance checklist can prompt broader coverage questions, but it doesn’t determine what a particular policy includes.
Use these questions to prepare a focused discussion about commercial insurance for property owners. Engineered Tax Services offers commercial insurance as an option for owners seeking a tailored risk-management conversation. Review its commercial insurance offering as you consider your options.
Compare Commercial Insurance Proposals Beyond the Premium
A lower premium doesn’t show whether two proposals protect the same interests or address the same exposures. Compare actual policy terms, including coverage definitions, limits, deductibles, exclusions, and conditions. A proposal summary can help orient your review, but confirm important details in the policy wording and ask about differences that could affect a claim.
Use a comparison worksheet to record what each proposal says and where you need clarification:
| Coverage | Limit | Deductible | Exclusions or conditions | Questions to resolve |
|---|---|---|---|---|
| Building | Record stated limit | Record amount or basis | Note relevant wording | How is the building valued? |
| Business personal property | Record stated limit | Record amount or basis | Note relevant wording | Which property and interests are included? |
| Income-related coverage | Record stated limit | Record amount or basis | Note triggers and waiting periods | What loss of income may qualify? |
| Liability | Record stated limit | Record amount or basis | Note exclusions and conditions | Who is insured, and which claims are addressed? |
Don’t leave a cell blank without a reason. Mark unavailable information as a question rather than assuming coverage is included or excluded.
How should property owners assess limits and deductibles?
A limit is generally the maximum payable for specified coverage under the policy, subject to its terms, conditions, and exclusions. A deductible is the owner’s stated share of certain covered losses. Ask how the policy values the property and what rebuilding assumptions inform the proposed limit. Check whether the valuation reflects relevant building features and current information, and clarify how a deductible applies to each coverage or loss scenario.
Which exclusions and conditions deserve closer review?
Look beyond the headline limit. Check exclusions, sublimits, waiting periods, protective safeguards, and notice requirements. Ask how vacancy, maintenance, renovations, or changes in tenant use could affect policy conditions, and what steps or notifications may be required. If wording is ambiguous, ask an insurance professional to explain it before binding or renewing coverage. Where appropriate, request clarification in writing.
The right proposal depends on the property, financing arrangements, contractual requirements, and the owner’s risk tolerance. A lender or contract may set requirements, but meeting them alone doesn’t establish that a policy fits the owner’s broader objectives. For commercial insurance for property owners, compare the trade-offs, document open questions, and evaluate terms as carefully as price.
Build a Practical Commercial Property Insurance Review Checklist
A structured review turns property records and policy documents into a focused conversation. Use this sequence to prepare:
- 1. Document the asset. Record the property address, construction and building details, ownership entity, current declared values, and significant renovations.
- 2. Identify exposures. Describe occupancy, tenant activities, maintenance practices, known protective systems, prior losses, and changes that may affect the property.
- 3. Compare terms. Review proposals side by side, noting coverage definitions, limits, deductibles, exclusions, and conditions.
- 4. Resolve open questions. Ask an insurance professional to explain unclear wording or how specific scenarios may be treated. Have qualified legal or insurance professionals review relevant contract requirements.
- 5. Schedule the next review. Set a reminder before renewal and revisit coverage after material changes to the property or its use.
What should owners prepare before speaking with an insurance professional?
Bring building characteristics, ownership details, tenant uses, current leases, maintenance records, renovation history, prior loss information, and details of known protective systems. Gather lender, lease, or contract insurance requirements for review by the appropriate professionals. Working with a thoroughly trained property and casualty producer helps ensure these intricate details are evaluated accurately; learn more about IICS to see how commercial risk producers build this specialized expertise. Prepare specific questions about valuation assumptions, exclusions, deductibles, and income interruption. These records help focus the discussion on the property’s actual circumstances and make it easier to identify missing information.
When should commercial property coverage be reviewed?
Review coverage before renewal, and don’t wait for the annual cycle if a material change occurs. Tell the insurer about changes in ownership, property use, occupancy, renovations, or building condition, and ask whether policy documents need updating. Revisit declared values after significant work or changes in rebuilding assumptions. Including these checks in routine property and risk-management planning helps keep information current.
Use the checklist as a working record, not a substitute for advice. There is no universal limit that suits every property, and policy obligations depend on the actual documents and circumstances. Ask an insurance professional to clarify coverage questions and consult a qualified legal professional about interpreting lease or contract obligations.
A deliberate review can make commercial insurance for property owners easier to assess. Explore commercial insurance with Engineered Tax Services as an option for a tailored risk-management conversation.
Make Commercial Insurance Part of a Long-Term Property Strategy
Insurance is one part of preserving a commercial property’s value. Regular maintenance, accurate records, thoughtful operational planning, and financial planning all contribute to risk management. A policy transfers specified risks according to its terms; it can’t prevent a loss, replace sound property oversight, or eliminate every operational or investment risk.
As an asset changes, its exposures may change too. Renovations can alter the building, and tenant activity can shift. Keep consistent records of condition, upgrades, occupancy, and insurance decisions so owners, property managers, lenders, and insurance professionals can work from current information. Review coverage needs alongside asset and cash-flow planning, not as a substitute for tax advice.
How can owners coordinate insurance and property oversight?
Make insurance review part of routine property planning rather than a task reserved for renewal. Share relevant updates among the people responsible for ownership, management, financing, and insurance discussions. Document maintenance and repairs, improvements, changes in use, and coverage decisions. A current record can help explain the property’s condition and support a more informed conversation when circumstances change.
- Record building condition, maintenance, and completed upgrades.
- Track changes to ownership, occupancy, tenant activities, and property use.
- Keep policy documents and notes on coverage decisions together.
- Revisit insurance assumptions alongside cash-flow and asset plans.
What should owners expect from a tailored insurance discussion?
A useful discussion should clarify the provider’s role, scope, available coverage options, and service responsibilities. Ask how proposed limits and exclusions relate to the property, which assumptions inform the proposal, and what exposures remain unresolved. Confirm that the provider can address the property type and the coverage needs under discussion. Clear answers help owners judge whether the proposed approach fits their needs instead of relying on broad assurances.
Engineered Tax Services offers commercial insurance as an option for property owners and developers seeking a tailored risk-management conversation. If you’re assessing whether that approach fits your property, explore commercial insurance with Engineered Tax Services. A considered review can make commercial insurance for property owners a more deliberate part of long-term asset oversight.
Turn Your Coverage Review Into a Stronger Property Strategy
Protecting a commercial asset takes more than selecting a policy. Start with the building’s documented exposures, then compare policy wording, limits, deductibles, exclusions, and conditions rather than relying on premium alone. Keeping property, occupancy, renovation, and maintenance records current also makes coverage discussions more precise as circumstances change.
Commercial insurance for property owners can support a broader effort to manage exposure, but it transfers only specified risks and can’t replace ongoing property oversight or financial planning. Treat coverage as one part of a long-term strategy, and bring unresolved questions to a qualified insurance professional.
Engineered Tax Services offers commercial insurance solutions for property owners and developers, with an approach focused on risk management. To explore whether its offering may fit your needs, explore commercial insurance solutions for property owners. A clear, well-documented conversation is a practical next step toward managing your investment with greater confidence.
Frequently Asked Questions
What insurance do commercial property owners typically need?
Commercial property owners typically assess coverage for the building, business personal property, liability exposures, and potential income interruption. These protections may be addressed through separate coverages or policy arrangements; they don’t automatically come together in one package. Commercial insurance for property owners should reflect the building’s construction, occupancy, tenant activities, ownership interests, and financing or contract requirements. Ask an insurance professional which options apply, then confirm the insured parties, definitions, limits, and exclusions in the policy documents.
Does commercial property insurance cover tenant damage?
It may, but tenant-caused damage isn’t automatically covered in every situation. The outcome depends on the policy’s covered causes of loss, exclusions, conditions, deductible, and which property and interests are insured. Damage to the owner’s building may be treated differently from damage to a tenant’s belongings or a claim alleging liability. Review the policy and lease together, and ask an insurance professional how specific tenant-related scenarios may be handled.
Is commercial property insurance required for a rental building?
Whether insurance is required depends on the property’s circumstances and applicable requirements. A lender, lease, or other contract may require particular insurance, even where an owner isn’t otherwise subject to a specific requirement. Don’t assume a contract’s minimum terms provide sufficient protection for the owner’s broader needs. Review financing and lease documents with the appropriate professionals, and ask an insurance professional to explain available coverage options and requirements that apply to the property.
How do property owners choose the right insurance coverage limits?
Choose limits by evaluating the property’s valuation basis, rebuilding assumptions, contents, potential income exposure, and relevant policy sublimits. Ask how the insurer arrived at proposed values and whether renovations or distinctive building features affect those assumptions. Compare limits with lender or contract requirements, then consider the financial impact of retaining losses above them. There’s no universal limit for every building; an insurance professional can explain options and how policy terms affect potential recovery.
What is typically excluded from commercial property insurance?
Exclusions vary by policy, so check the actual wording rather than relying on a standard list. Areas to ask about may include flood or earth movement, gradual deterioration, maintenance-related damage, vacancy, and particular causes of water loss. In incidents involving water damage or pipe breaks, working with specialists like Dryrite Restoration can help limit physical damage and document the event; find out more about emergency restoration services. Some risks may be excluded, limited by sublimits, or addressed through separate terms. Ask the insurance professional to clarify relevant exclusions, conditions, and any steps required to address exposures important to your property.
It can if the policy includes applicable rental-income or business-interruption provisions and the loss meets their terms. Coverage may depend on a covered physical loss affecting the property, as well as policy limits, exclusions, and any waiting period or time limitation. Ask what triggers coverage, how the amount is determined, and which rental income or expenses may be considered. Don’t assume lost rent is included just because the building has property coverage.
When should a commercial property owner review an insurance policy?
Review the policy before renewal and after material changes to ownership, occupancy, tenant activities, renovations, property use, or building condition. Revisit declared values when substantial work or changed rebuilding assumptions could affect them. Keep maintenance, upgrade, and prior loss records available for the discussion. Notify the insurer about relevant changes and ask whether policy terms or information need updating. Regular reviews help keep coverage decisions connected to the property as it evolves.