What if your building's envelope and mechanical systems were actually high-yield financial assets rather than just construction line items? For many developers and property owners, the 2026 landscape for energy efficient building tax incentives feels like a minefield of shifting prevailing wage requirements and dense IRS compliance hurdles. You've likely felt the frustration of trying to determine whether Section 179D or 45L offers the best return for your specific asset. We understand that navigating these technical intersections requires more than just accounting; it requires engineering-based precision.
This guide provides a clear roadmap to help you strategically leverage federal incentives to offset costs and enhance property value. We'll explore the critical multipliers for 2026, the nuances of the specialized methodology used to substantiate claims, and how to secure third-party certifications that are built to withstand the most rigorous scrutiny. By the end, you'll have the technical framework needed to transform sustainability into a powerful engine for project cash flow.
Key Takeaways
- Learn how the 2026 shift from temporary tax extenders to permanent federal incentives creates long-term stability for your capital planning and project budgeting.
- Identify which commercial systems, including advanced HVAC and building envelopes, qualify for maximum Section 179D deductions through technical certification.
- Discover how multifamily developers capture significant per-unit tax savings across apartment buildings and student housing assets using Section 45L credits.
- Master the 5-step engineering-based study process required to secure energy efficient building tax incentives while meeting strict IRS documentation standards.
- Understand how specialized tax engineering directly improves Net Operating Income and property cap rates to maximize your portfolio's overall market value.
The 2026 Landscape of Energy Efficient Building Tax Incentives
The federal government has transitioned from viewing energy efficient building tax incentives as temporary relief to treating them as permanent pillars of national energy independence. This evolution began with the Energy Policy Act of 2005, but the 2026 regulatory environment is far more sophisticated. Building owners now face rigorous performance baselines set by the Department of Energy (DOE). These standards require engineering-based precision to ensure that systems like lighting, HVAC, and building envelopes meet the specific efficiency targets mandated for the current tax year. Modern incentives are no longer just “perks”; they're strategic financial assets designed to reward proactive optimization rather than just baseline compliance. This shift means that technical documentation is the only bridge between a standard construction project and a high-yield tax strategy.
Key Federal Incentives for Property Owners
Strategic property owners must distinguish between the two primary vehicles for tax optimization to maximize their ROI. Understanding these mechanisms is vital for project cash flow, as they impact the balance sheet in different ways.
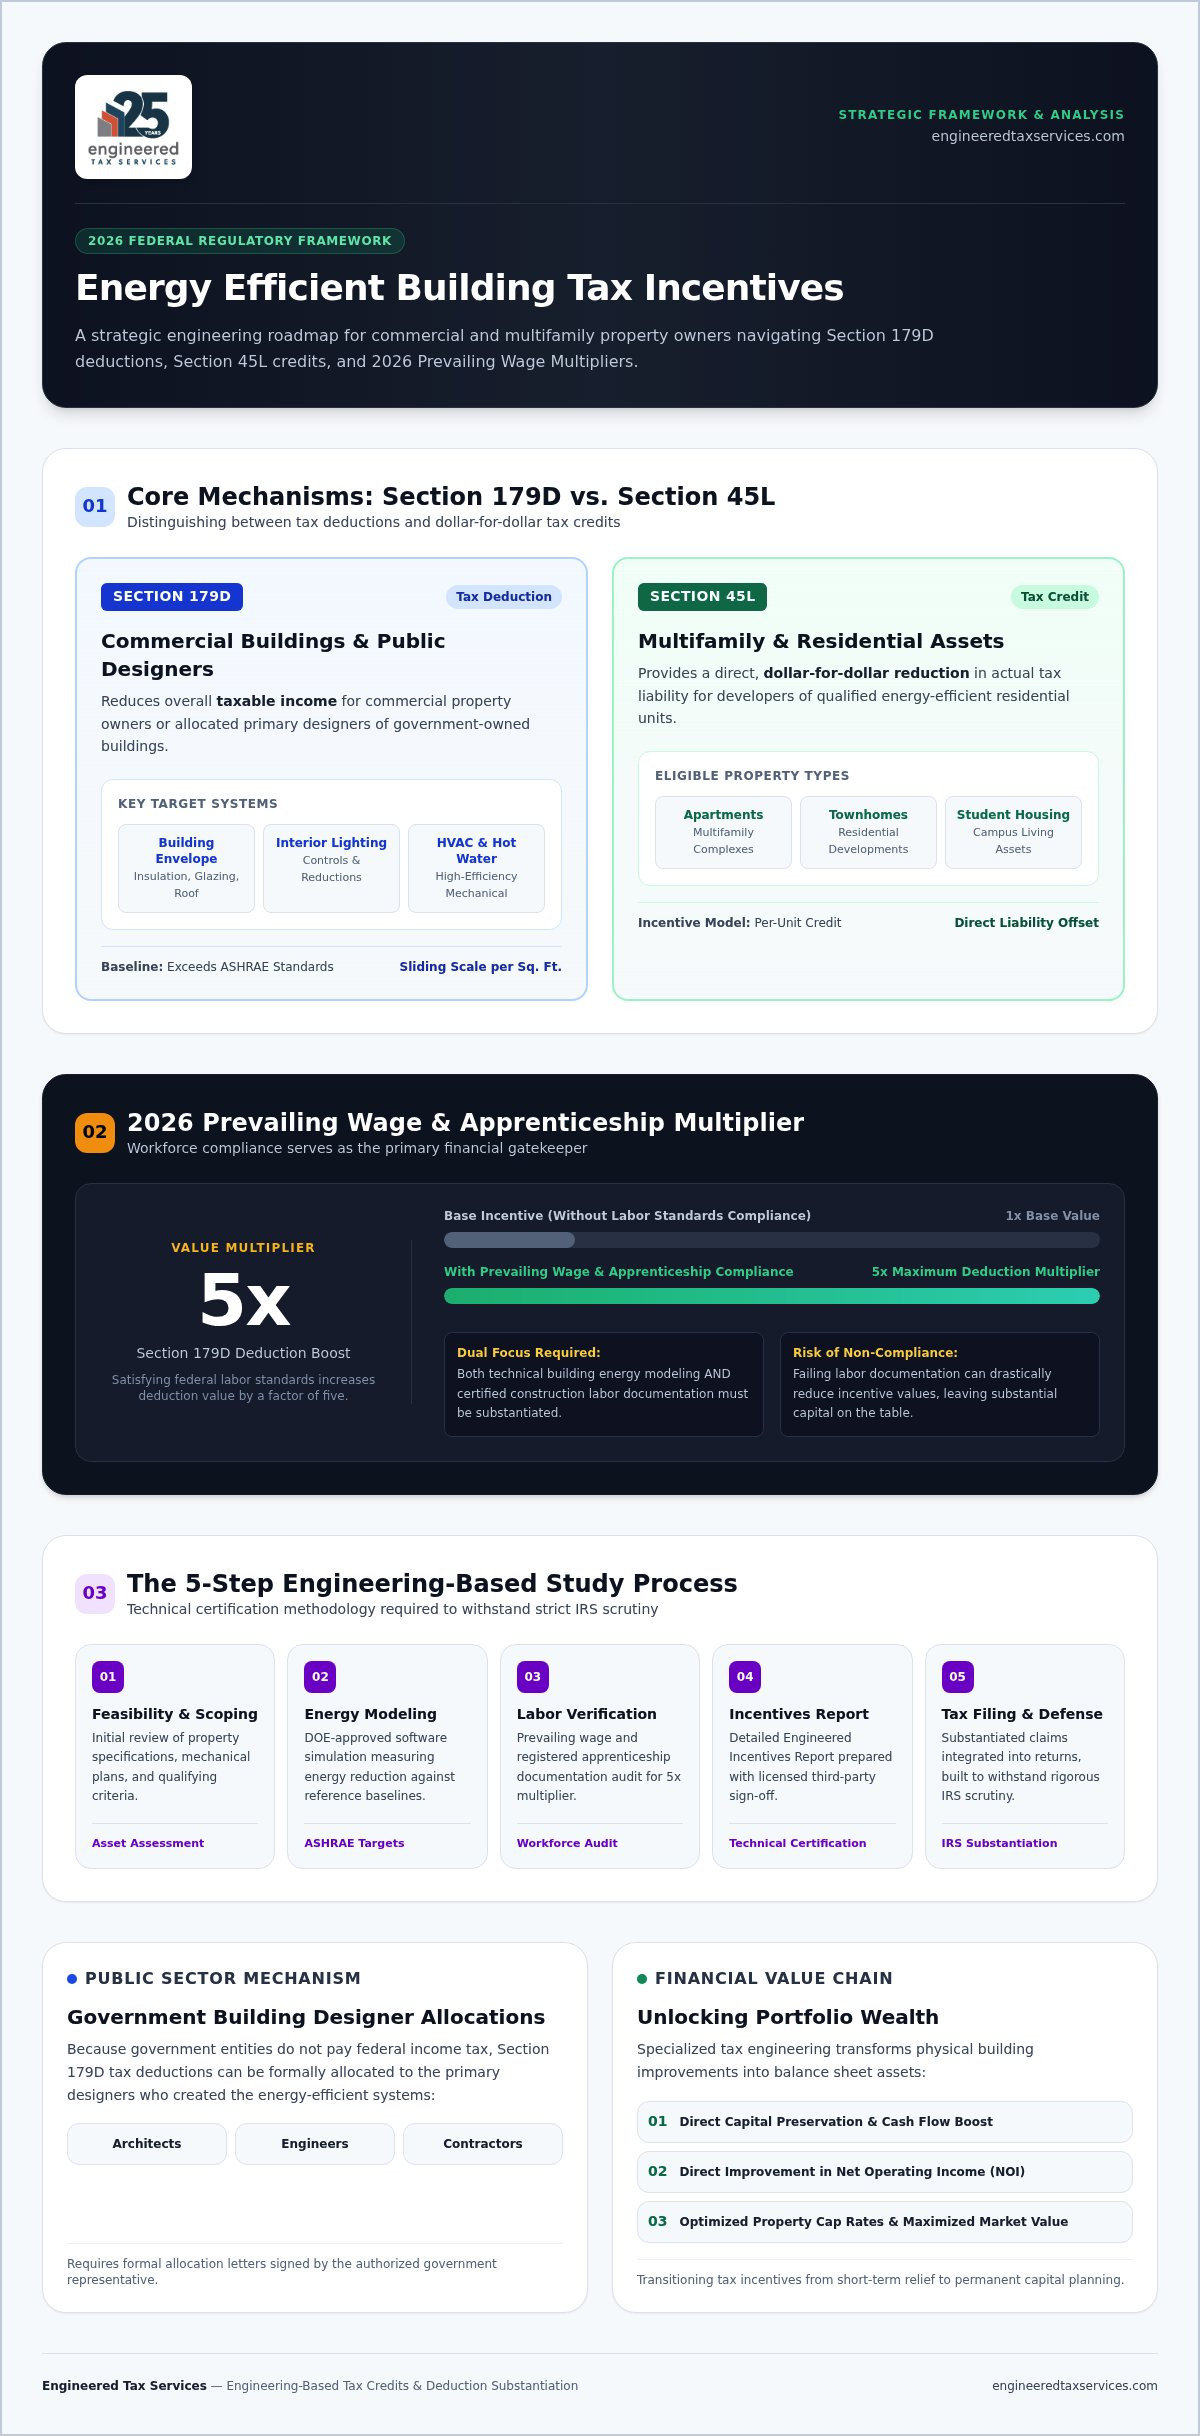
- Section 179D: This is a tax deduction for commercial property owners or designers of government buildings who achieve specific energy reduction targets. It targets systems that significantly reduce the energy and power costs of the building's total energy use.
- Section 45L: This is a tax credit for developers of energy-efficient residential units, including multifamily apartment buildings, townhomes, and student housing.
The distinction between a deduction and a credit is fundamental. A deduction reduces your overall taxable income, while a credit provides a direct, dollar-for-dollar reduction in the actual tax liability. Both mechanisms require detailed Engineered Incentives Reports to prove that the building's technical performance justifies the claim under current IRS standards.
Prevailing Wage and Apprenticeship Requirements in 2026
In 2026, labor standards are the primary gatekeepers of high-value tax benefits. They function as a powerful multiplier for tax savings, rewarding those who adhere to strict federal guidelines. Failing to document prevailing wage and apprenticeship compliance can lead to a drastic reduction in the incentive's value, often leaving millions on the table. The 179D deduction increases by a factor of five for projects that successfully satisfy these labor standards. This creates a high-stakes environment where technical documentation must cover both the engineering performance of the building and the administrative details of the construction workforce. Without this dual focus, developers risk significant financial exposure and lost opportunities for capital preservation. It's no longer enough to build green; you must also build with a certified, compliant workforce to unlock the full potential of these incentives.
Section 179D: The Strategic Framework for Commercial Building Deductions
Section 179D stands as the primary vehicle for commercial property owners to recoup capital invested in high-performance infrastructure. While the 2026 landscape is complex, the core objective remains the same: rewarding those who exceed ASHRAE standards. This deduction isn't just a broad tax break. It's a targeted incentive for specific systems, including the building envelope, interior lighting, and HVAC or hot water systems. Both private commercial building owners and the primary designers of government facilities can qualify, provided the technical benchmarks are met.
The 2026 deduction operates on a sliding scale. The total benefit is directly tied to the percentage of energy reduction achieved relative to a reference building. For owners, this creates a clear financial incentive to push for higher efficiency tiers. In 2026, the maximum deduction limits per square foot have been adjusted to reflect current economic conditions and updated efficiency baselines. Meeting these benchmarks requires a specialized approach that bridges engineering data with tax law to ensure every square foot is optimized for savings.
Government Building Designers and the Allocation Process
Architects, engineers, and contractors play a unique role in the public sector. Since government entities don't pay taxes, they can't utilize the deduction themselves. Instead, they can allocate the deduction to the primary designer responsible for the energy-efficient systems. This process requires a formal allocation letter signed by an authorized government representative. Securing this document is a critical step in the 179D Energy Efficient Commercial Building Deduction strategy for professional service firms looking to improve their project margins.
Technical Requirements for 179D Certification
Achieving 179D status isn't a matter of simple accounting. It requires a rigorous energy model performed using IRS-approved software. This model compares the building's projected energy consumption against the performance of a hypothetical building meeting minimum standards. Per the IRS Section 179D deduction requirements, a licensed engineer or contractor must personally inspect the property and sign off on the study. This ensures the technical documentation is accurate and legally defensible.
Understanding the difference between interim and permanent 179D rules in 2026 is essential for long-term planning. The permanent rules offer a stable framework for multi-year developments, while interim rules may provide specific pathways for retrofits. To ensure your project maximizes these energy efficient building tax incentives, you should utilize Engineered Incentives Reports that provide the technical precision required for IRS compliance.
The 45L Tax Credit: Optimizing ROI for Multifamily and Residential Developers
While the IRS Section 179D commercial buildings deduction targets large-scale square footage, the 45L credit offers a different but equally potent mechanism for wealth preservation: a per-unit tax benefit. For developers of apartment buildings, townhomes, and student housing, these energy efficient building tax incentives have become a cornerstone of the modern capital stack. In 2026, the financial viability of a multifamily project often hinges on the ability to capture these credits to offset rising construction costs and interest rates. By shifting the focus from total building volume to individual living units, 45L provides a scalable way to enhance project cash flow and long-term asset value.
The 2026 landscape requires a transition toward more rigorous performance benchmarks. Developers can't rely on outdated efficiency standards; instead, they must align their projects with ENERGY STAR and Zero Energy Ready Home (ZERH) certifications. This evolution reflects a broader federal push toward extreme efficiency, turning what used to be a “nice-to-have” sustainability feature into a mandatory requirement for high-level tax optimization. Integrating these standards early in the design phase isn't just about compliance. It's a strategic move to secure a competitive advantage in a market that increasingly values “Green” certified assets.
Calculating the 45L Credit Per Unit
The financial impact of 45L depends entirely on the tier of efficiency achieved during construction. For 2026, units that meet the latest ENERGY STAR requirements qualify for a substantial base credit. However, the most significant opportunity for growth lies in the 45L Tax Credit Multifamily program for Zero Energy Ready Homes. These units command a much higher credit amount, providing a powerful incentive for developers to invest in superior building envelopes and mechanical systems. This tiered approach allows you to choose the level of investment that best aligns with your project's financial goals and performance targets.
Certification and Compliance for Multifamily Assets
Securing these credits requires more than just meeting efficiency goals; it demands a rigorous third-party verification process. An ‘Eligible Certifier,' typically a licensed professional unrelated to the project, must verify that each unit meets the required standards. According to 2026 DOE standards, a Zero Energy Ready Home is a high-performance building so energy-efficient that a renewable energy system can offset most or all of its annual energy consumption. This definition serves as the technical baseline for the highest tier of 45L savings. To survive a potential IRS audit, developers must maintain comprehensive documentation, including energy models and certification letters, often consolidated into specialized Engineered Incentives Reports. This technical precision ensures that your tax claims are substantiated and your wealth is protected against regulatory scrutiny.
Compliance and Certification: Navigating the Engineering-Based Study Process
Securing energy efficient building tax incentives requires a shift from standard accounting to rigorous engineering analysis. The IRS doesn't simply take your word for it; they require technical substantiation that your property meets specific performance thresholds. This begins with a comprehensive data collection phase where architectural plans, mechanical, electrical, and plumbing (MEP) drawings, and utility data are meticulously reviewed. This documentation forms the foundation of a defensible tax claim. Without these technical records, even the most energy-efficient buildings may fail to qualify for the deductions they deserve.
Independent third-party verification is the gold standard for compliance and audit protection. Using a licensed engineering firm ensures that the analysis is objective and adheres to the highest professional standards. One of the most effective strategies for 2026 involves integrating energy studies with Cost Segregation Commercial Property analyses. This “double-dip” approach allows you to accelerate depreciation on non-structural components while simultaneously claiming energy-based deductions or credits. This specialized methodology creates a powerful synergy that maximizes project cash flow and improves your overall return on investment.
Step-by-Step Engineering Analysis
A successful study follows a methodical, five-step progression to ensure technical accuracy and IRS compliance.
- Step 1: Feasibility analysis. We perform a preliminary review to estimate potential 2026 savings based on your building's data to determine if the study provides a positive ROI.
- Step 2: On-site inspection. Licensed engineers verify that the installed systems match the design plans and perform according to specified efficiency ratings.
- Step 3: Energy modeling. Using IRS-approved software, we simulate your building's performance against ASHRAE standards to calculate the exact percentage of energy reduction.
- Step 4: Issuing the formal certification. We generate the final Engineered Incentives Report, which provides the technical signature required to claim the incentive.
- Step 5: Audit defense and implementation. We provide the necessary documentation for your tax filings and stand behind the study should the IRS require further clarification.
Avoiding Common Pitfalls in Energy Tax Claims
Many property owners fall into the trap of using “accounting-only” firms that lack the technical depth to navigate 179D or 45L nuances. These firms often fail to understand the engineering complexities of HVAC performance or building envelope thermal resistance. Another common risk is the use of non-approved software for energy modeling. The IRS is specific about which tools can be used to substantiate claims; using an unlisted program can lead to an immediate disqualification of your deduction. Precision is your best defense against regulatory scrutiny. To ensure your project meets every technical requirement, request a professional engineering review of your current assets.
Beyond Compliance: Unlocking Wealth Through Specialized Tax Engineering
How does a tax strategy translate into real-world property value? For sophisticated investors, energy efficient building tax incentives are more than just a reduction in liability; they're a mechanism for improving Net Operating Income (NOI). By lowering the effective cost of capital improvements and reducing operational expenses through efficiency, these incentives directly compress property cap rates. This financial optimization creates a stronger balance sheet and increases the asset's valuation during a sale or refinance. It's a strategic move that transforms a tax obligation into a growth engine.
In the 2026 rental market, “Green” certified buildings command a distinct marketing advantage. Tenants are increasingly prioritizing sustainability, allowing owners of energy-efficient assets to maintain higher occupancy rates and premium rents. Maximizing energy efficient building tax incentives allows owners to fund further sustainable upgrades, creating a virtuous cycle of improvement and wealth preservation. This forward-thinking approach ensures that your portfolio remains resilient against shifting market demands and regulatory requirements.
The ETS Advantage: Engineering-Based Precision
Standard CPAs often lack the technical depth to identify every available opportunity within a building's mechanical and envelope systems. As a licensed engineering firm, we act as the technical bridge between construction data and tax law. We specialize in uncovering “hidden” incentives that generic consultants might overlook, such as specific component-level efficiencies that qualify for higher deduction tiers. Our Engineered Incentives Reports provide a level of substantiation that offers peace of mind; if the IRS ever questions a claim, our technical team is ready to provide a rigorous audit defense based on empirical data and professional engineering standards. This expertise ensures that your tax strategy remains robust even under the most intense scrutiny.
Strategic Next Steps for Property Owners
The first step toward maximizing your 2026 pipeline is scheduling a preliminary feasibility study. This analysis provides a clear estimate of potential savings before you commit to a full study, ensuring an optimal return on investment. To start the process, consider the following actions:
- Evaluate current assets for retroactive 179D or 45L opportunities that may have been missed in previous years.
- Review your 2026 development pipeline to integrate efficiency standards into the design phase.
- Consolidate technical documentation from recent retrofits to substantiate new claims.
Don't limit your focus to new construction; existing portfolios often hold untapped potential for capital recovery. To begin your journey toward wealth optimization, Contact Engineered Tax Services for a 2026 incentive analysis and discover the full potential of your portfolio.
Strategize for Long-Term Growth with Engineering-Based Tax Optimization
The 2026 regulatory environment has fundamentally redefined the value of energy efficient building tax incentives. We've analyzed how Section 179D and 45L function as sophisticated financial instruments that do more than just lower your tax bill; they enhance property valuation and improve Net Operating Income. Successfully capturing these high-value benefits requires a partner who understands the technical nuances of both building performance and IRS compliance. Precision in documentation isn't just a requirement; it's your primary defense against regulatory risk.
As a licensed engineering firm and a national authority on 179D and 45L, we conduct over 10,000 studies annually to ensure our clients receive the maximum legal tax reduction possible. This level of precision is the only way to build a defensible tax strategy that stands up to scrutiny while driving portfolio-wide optimization. It's time to stop viewing efficiency as a cost and start treating it as a cornerstone of your capital stack. Maximize your 2026 building incentives with an ETS engineering study to secure your project's financial health and long-term stability. Your portfolio's potential for growth is waiting to be unlocked through technical excellence.
Frequently Asked Questions
What is the difference between the 179D deduction and the 45L credit?
Section 179D is a tax deduction for commercial property owners or designers of government facilities, while 45L is a per-unit tax credit for residential and multifamily developers. The distinction is critical for project cash flow; credits provide a dollar-for-dollar reduction in liability, whereas deductions reduce total taxable income. Both require specialized energy efficient building tax incentives studies to substantiate performance against federal baselines. Choosing the right incentive depends entirely on the asset type and your financial objectives.
Can I claim both Section 179D and Cost Segregation on the same building?
You can absolutely leverage both Section 179D and Cost Segregation on the same commercial asset. This dual approach is a cornerstone of strategic wealth optimization. While Cost Segregation reclassifies structural components into shorter recovery periods to accelerate depreciation, 179D provides an additional deduction for the energy-efficient performance of those systems. Integrating these studies through a single engineering firm ensures that your technical documentation is consistent and maximizes your total tax savings for the project.
Do government buildings qualify for energy efficient building tax incentives?
Government buildings do qualify, but the tax benefit is handled through an allocation process. Since public entities don't pay federal income tax, they can transfer the 179D deduction to the primary designer of the energy-efficient systems. This includes architects, engineers, and contractors responsible for the building's envelope or mechanical infrastructure. Securing a formal allocation letter from the government representative is the essential step for professional service firms to claim this valuable incentive and improve their margins.
What are the 2026 prevailing wage requirements for 179D?
The 2026 prevailing wage and apprenticeship requirements function as a major multiplier for the 179D deduction. Projects that satisfy these labor standards can increase their deduction by five times the base amount. To comply, contractors must ensure that laborers and mechanics are paid at rates not less than the prevailing wages determined by the Department of Labor. You must also meet specific participation percentages for qualified apprentices during the construction or renovation phase to unlock the full savings.
How much can I save per square foot with the 179D deduction in 2026?
The 179D deduction in 2026 follows a sliding scale based on the percentage of energy cost reduction achieved. The benefit starts at a base rate for meeting minimum efficiency thresholds and increases for every additional percentage point of savings up to a maximum cap. These rates are adjusted annually for inflation. Because the calculation depends on complex energy modeling against ASHRAE standards, an Engineered Incentives Report is required to determine the exact value for your specific square footage.
What documentation is required to claim the 45L multifamily tax credit?
Claiming the 45L credit for multifamily projects requires a robust package of technical documentation. This includes an energy model performed with IRS-approved software and a certification from an independent eligible certifier. You must also provide proof that the units meet current ENERGY STAR or Zero Energy Ready Home standards. Maintaining these records is vital for audit defense, as they substantiate the energy performance and the specific credit tier claimed for each residential unit in the development.
Is a licensed engineer required to certify my building's energy efficiency for the IRS?
A licensed engineer or contractor is legally required to certify your building's energy efficiency for 179D and 45L claims. The IRS mandates that a qualified third party, unrelated to the project, must perform the physical inspection and verify the energy modeling results. This ensures that the technical data used to claim energy efficient building tax incentives is accurate and follows professional standards. Relying on an engineering firm provides the rigorous substantiation needed to withstand potential IRS scrutiny.
Can I retroactively claim energy tax incentives for buildings completed in prior years?
You can often claim energy tax incentives retroactively for buildings completed in prior years through a look-back study. If you didn't claim the 179D deduction or 45L credit when the building was placed in service, you might be able to file an amended return or an accounting method change. This allows you to capture missed savings and improve current project cash flow. We recommend evaluating your portfolio for any assets placed in service within the last three years to identify hidden opportunities.