By 2026, the tax advantages that fueled the last decade of real estate wealth are scheduled to hit a structural cliff. You've likely noticed the increasing pressure of tax drag on your portfolio as bonus depreciation percentages continue their steady descent. It's frustrating to watch a significant portion of your capital gains and rental income disappear into federal coffers when that liquidity could be reinvested into new acquisitions. Utilizing engineering-based cost segregation for high net worth investors isn't just a tax strategy anymore; it's a fundamental requirement for wealth preservation.
This guide will show you how to optimize your cash flow and manage the 2026 tax law changes with technical precision. You'll discover how to legally reduce your federal income tax liability while ensuring your documentation is robust enough to withstand rigorous IRS scrutiny. We'll examine the specific methodologies that bridge the gap between accounting and engineering to unlock hidden value in your commercial holdings. From understanding the phase-down schedule to implementing advanced 1031 exchange synergies, you're about to learn how the nation's most successful investors are positioning themselves for a more restrictive tax environment.
Key Takeaways
- Learn how engineering-based cost segregation for high net worth investors serves as a critical defense against the scheduled 2026 bonus depreciation phase-down.
- Understand the technical difference between accounting-based and engineering-based studies to ensure your documentation meets the highest IRS standards for precision.
- Discover how to navigate Passive Activity Loss limitations and leverage Real Estate Professional Status to maximize your portfolio's immediate cash flow.
- Identify the common red flags in non-engineered reports that trigger audits and how to secure audit-proof technical substantiation for your tax positions.
- Explore the strategic integration of cost segregation with 179D energy deductions to further accelerate wealth growth and unlock reinvestment capital.
Navigating the 2026 HNWI Tax Landscape: Why Cost Segregation is Essential
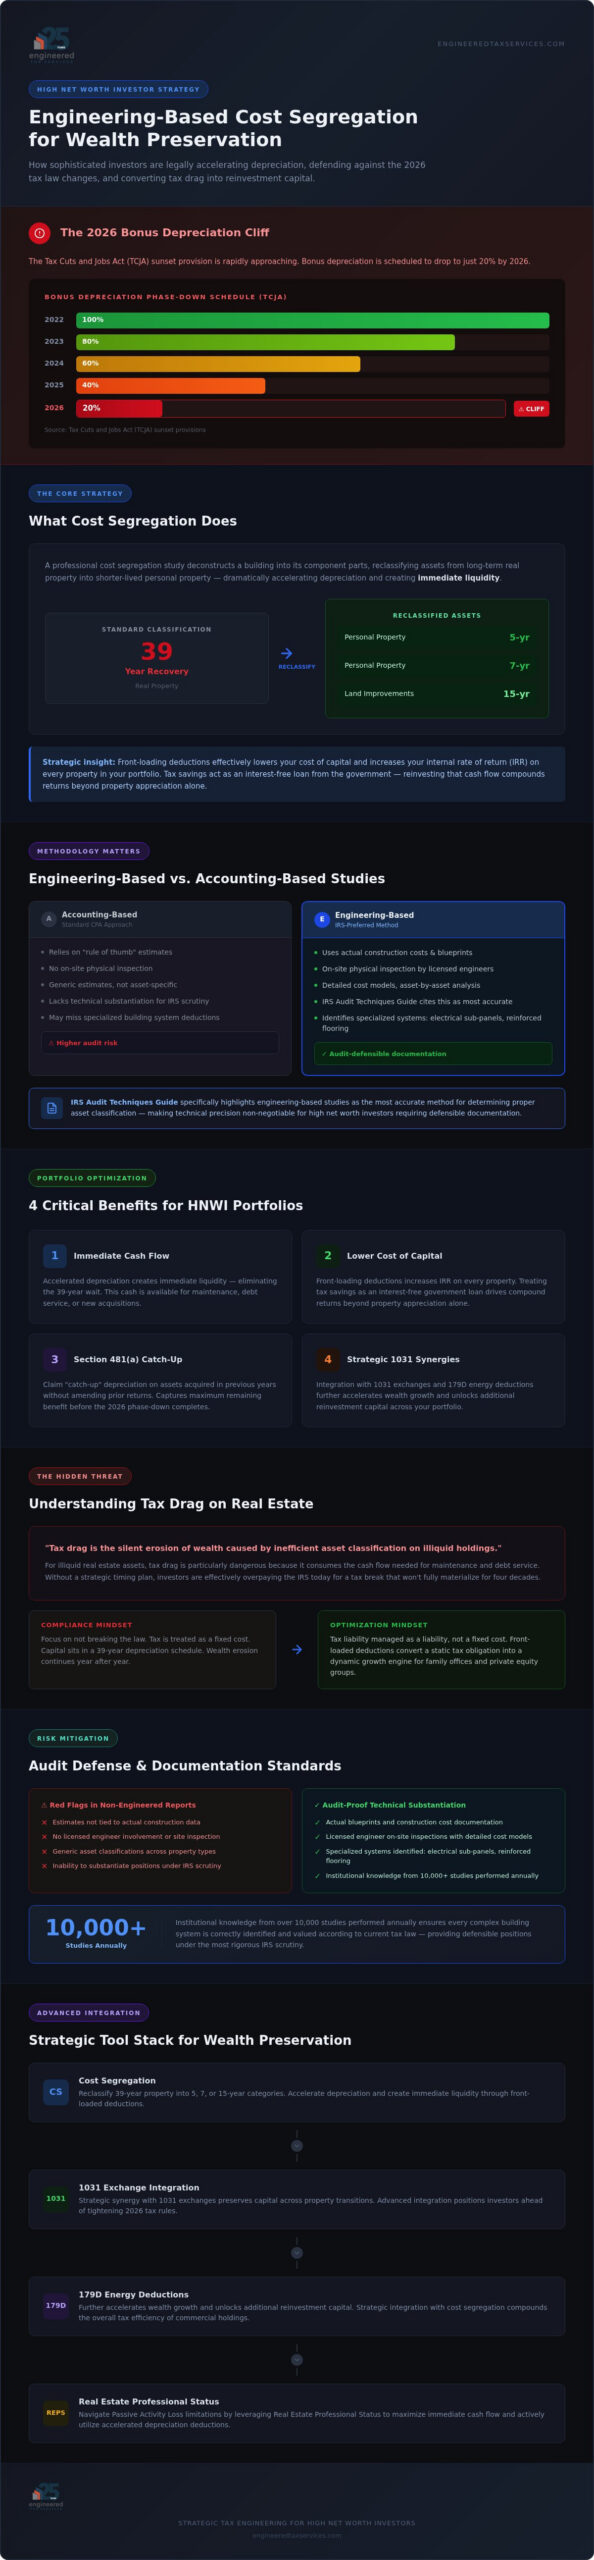
For the sophisticated property owner, real estate isn't just about rental income; it's a structural tax shield. Cost segregation serves as the precision tool that deconstructs a building into its component parts for maximum financial efficiency. By conducting a professional cost segregation study, you can reclassify assets from 39-year real property to 5, 7, or 15-year personal property. This shift accelerates depreciation, creating immediate liquidity. For those managing substantial portfolios, cost segregation for high net worth investors is the primary defense against tax drag, which is the silent erosion of wealth caused by inefficient asset classification on illiquid holdings.
Tax drag is particularly dangerous for illiquid real estate assets because it consumes the very cash flow needed for maintenance and debt service. Without a strategic timing plan, you're essentially overpaying the IRS today for a tax break you won't fully realize for four decades. Sophisticated investors treat their tax liability as a liability to be managed, not a fixed cost. By front-loading deductions, you effectively lower your cost of capital and increase your internal rate of return (IRR) on every property in your portfolio.
The 2026 Bonus Depreciation Outlook
The Tax Cuts and Jobs Act (TCJA) introduced a sunset provision that is now rapidly approaching. By 2026, bonus depreciation is scheduled to drop to just 20%. This phase-down significantly alters the ROI profile of new acquisitions. However, investors can still leverage Section 481(a) adjustments to claim “catch-up” depreciation on assets acquired in previous years without needing to amend prior returns. Implementing these studies early in 2026 ensures you capture the maximum remaining benefit before the incentive disappears entirely. It's a timing strategy that preserves capital for your next acquisition rather than letting it sit idle in a standard 39-year recovery period.
Wealth Preservation vs. Simple Tax Compliance
Most CPAs focus on compliance, ensuring you don't break the law. We focus on optimization, ensuring you keep your capital. Moving beyond standard depreciation strategies for commercial real estate requires an engineering-based approach. The shift from a compliance mindset to an optimization mindset allows you to treat tax savings as an interest-free loan from the government. When you reinvest that cash flow back into the market, the compound interest effect can often outweigh the appreciation of the property itself. High-level cost segregation for high net worth investors turns a static tax obligation into a dynamic growth engine for your family office or private equity group.
The Engineering-Based Method: Why Technical Precision Matters
Many investors assume cost segregation is a simple accounting exercise. It isn't. While accounting-based studies rely on “rule of thumb” estimates, an engineering-based approach uses actual construction costs, blueprints, and physical inspections. The IRS Audit Techniques Guide specifically highlights engineering-based studies as the most accurate method for determining the proper classification of assets. This level of technical precision is non-negotiable for cost segregation for high net worth investors who require defensible documentation. With over 10,000 studies performed annually, our firm's institutional knowledge ensures every complex building system is correctly identified and valued according to current tax law.
The Role of Licensed Engineers in Tax Law
A standard CPA firm possesses the financial acumen to manage your filings, but they often lack the technical training to dissect a building's mechanical systems. Licensed engineers bridge this gap by conducting on-site inspections and creating detailed cost models. This process involves substantiating specialized building systems, such as electrical sub-panels dedicated to equipment or reinforced flooring, for accelerated treatment. Providing this level of technical substantiation is what differentiates a high-quality report from a generic estimate. If you're looking for a partner to provide this level of detail, you can review our engineered incentives reports to see how technical analysis drives value.
Maximizing Asset Reclassification
Identifying 5, 7, and 15-year assets requires a deep understanding of construction quality and material lifespan. For instance, land improvements like decorative landscaping or parking lot lighting qualify for 15-year treatment, while specialized plumbing or cabinetry might fall into the 5-year category. The quality of construction significantly impacts these depreciation schedules; a luxury high-rise has different mechanical requirements than a standard warehouse. The engineering-based method serves as the primary defense against IRS reclassification of these assets back into 39-year real property. By utilizing a rigorous engineering methodology, you ensure that your asset reclassification is both maximized and audit-proof.
Optimizing HNWI Portfolios: Passive Loss Rules and Strategic Integration
Managing a high-value real estate portfolio requires more than just identifying assets; it requires understanding how those assets interact with the broader tax code. The primary hurdle for many is the Passive Activity Loss (PAL) limitation. This rule often prevents investors from using depreciation to offset their high-earning active income. Through the strategic use of cost segregation for high net worth investors, we can align these deductions with specific status designations like Real Estate Professional Status (REPS). When an investor qualifies for REPS, their rental losses become active, allowing them to shield their entire income stream from excessive taxation. It's a powerful synergy that transforms a static asset into a dynamic tax-planning tool.
For those who don't meet REPS criteria, the short-term rental (STR) strategy remains a viable 2026 maneuver. If a property's average guest stay is seven days or less, the IRS doesn't classify the income as a passive rental activity. This allows for significant front-loaded depreciation to offset active business income, provided the investor meets material participation standards. It's a sophisticated way to bypass traditional PAL restrictions while building a diversified portfolio.
Strategic 1031 Exchange Synchronization
Cost segregation and property swaps shouldn't exist in silos. When you utilize 1031 exchange services, you're deferring capital gains, but you also need to manage depreciation recapture. A common fear is that accelerated depreciation will trigger a massive tax hit during the exchange. Proper engineering-based analysis protects your equity gain by ensuring the replacement property has sufficient “like-kind” personal property components to absorb the carryover. This synchronization is vital for long-term estate planning, especially when positioning assets for a future step-up in basis for your heirs.
Active vs. Passive Income Strategies
The utility of your depreciation losses depends heavily on how your activities are grouped. We help investors navigate the complexities of the Alternative Minimum Tax (AMT) by optimizing the timing of these deductions. By grouping related business activities, you can often maximize the reach of your cost segregation benefits. This isn't just about compliance; it's about active wealth preservation. The goal is to ensure that every dollar of depreciation is working to offset the highest possible tax bracket, effectively increasing your available capital for future investment rounds.
Mitigating Risk: Audit Defense and Technical Documentation Standards
Portfolio growth shouldn't come at the expense of security. As the IRS increases its enforcement focus, the scrutiny on cost segregation for high net worth investors will reach unprecedented levels through 2026. An “audit-proof” study isn't a guarantee against an inquiry, but it's a guarantee of a successful defense. The IRS prioritizes technical reports that utilize engineering-based cost modeling over simple rule-of-thumb estimates. Non-engineered studies often rely on generic industry averages. These lack the building-specific blueprints and site-visit documentation required to withstand a rigorous federal challenge. Specialized firms defend their technical findings by providing the underlying data that proves an asset's shorter recovery period, ensuring your tax positions are grounded in physical reality.
The IRS Cost Segregation Audit Techniques Guide
The IRS provides a specific roadmap for what they consider a high-quality study. Aligning your analysis with the official IRS Cost Segregation Audit Techniques Guide is the only way to ensure your cost segregation commercial property report remains defensible. This guide emphasizes the need for technical substantiation of asset reclassification. It moves beyond simple accounting entries to require physical evidence, such as electrical schematics and plumbing diagrams. If your report can't pass the “Whiteco” legal tests or other relevant judicial precedents, the IRS may reclassify your accelerated assets back to a 39-year life, triggering interest and penalties. Contemporaneous documentation, created at the time of the study, is your most powerful shield in these scenarios.
Choosing a Specialized Tax Engineering Firm
Selecting the right partner is a strategic decision that impacts your financial security. You need to verify that your provider holds the necessary engineering licenses and carries professional liability insurance specifically for tax work. Ask your provider if they've ever had a study overturned in an audit. An independent, licensed engineering firm provides a level of technical depth that an in-house accounting department simply cannot replicate. They act as the “Expert's Expert,” bridging the gap between tax law and structural engineering. When your wealth is on the line, you don't want a generalist; you want a specialist with a national track record of success. You can contact our team of licensed engineers to discuss how we secure your portfolio's specific requirements through rigorous technical analysis.
Engineered Tax Services: The Strategic Partner for Wealth Preservation
Engineered Tax Services (ETS) operates as a licensed engineering firm, performing over 10,000 studies annually. This volume provides a unique perspective on the national tax landscape, positioning the firm as a strategic partner rather than a mere service provider. For those seeking cost segregation for high net worth investors, the value lies in the intersection of engineering precision and tax law. By identifying every available incentive, we don't just ensure compliance; we drive significant capital back into your portfolio. Our case studies frequently demonstrate multi-million dollar cash flow realizations for HNWI portfolios, proving that technical analysis is the most effective tool for wealth preservation in a shifting regulatory environment. We function as the “Expert's Expert,” providing the specialized data that standard accounting practices often overlook.
Beyond Depreciation: A Holistic Approach
True wealth optimization requires looking beyond simple depreciation. We specialize in synergizing cost segregation with 179D energy efficient commercial building deductions and 45L credits for residential developments. This holistic view ensures that every structural improvement and energy-efficient system is leveraged for its maximum tax benefit. Additionally, as a specialized R&D tax credit engineering firm, we assist family-owned businesses in capturing incentives for technical innovation within their operations. Our commitment to technical precision ensures that these complex, multi-layered strategies remain robust and defensible. This integrated approach allows you to stack incentives, maximizing the total value-add of your specialized research and development efforts alongside your real estate holdings.
Your Path to Enhanced Cash Flow
The ETS process is designed to be thorough yet efficient, moving from an initial intake and preliminary analysis to the delivery of a finalized, engineering-based report. We don't replace your existing professional network; we enhance it. By working alongside your CPA and legal team, we provide the technical substantiation they need to optimize your 2026 tax position safely. This collaborative approach ensures that your overall wealth strategy is cohesive and aligned with your long-term goals. Every study we perform is grounded in rigorous standards, portraying a character that is both forward-thinking in its search for opportunities and conservative in its commitment to accuracy. Taking the next step begins with a preliminary analysis to identify the specific opportunities hidden within your commercial holdings, ensuring that cost segregation for high net worth investors is implemented with the highest level of technical integrity. It's time to transition from standard tax planning to a high-level, engineered strategy that prioritizes your liquidity, growth, and long-term financial stability.
Secure Your Portfolio's Future Through Technical Precision
The 2026 tax landscape represents a significant pivot point for real estate wealth preservation. As bonus depreciation percentages continue their scheduled decline, the implementation of engineering-based cost segregation for high net worth investors becomes a fundamental requirement for maintaining liquidity. We've explored how technical reclassification, strategic 1031 exchange synchronization, and rigorous audit defense standards protect your capital from unnecessary tax drag. By moving beyond simple compliance and embracing a specialized, engineered approach, you ensure your portfolio remains a dynamic engine for growth.
Engineered Tax Services brings national expertise and a specialized focus on wealth preservation to every engagement. With over 10,000 tax studies performed annually by our licensed engineering professionals, we provide the technical substantiation required to withstand IRS scrutiny. Don't leave your 2026 tax position to chance or generic estimates. It's time to unlock the hidden value in your commercial holdings with an “expert's expert” by your side.
Request a complimentary preliminary cost segregation analysis from Engineered Tax Services and take the first step toward optimizing your cash flow today. Your future growth depends on the strategic decisions you make now.
Frequently Asked Questions
Is cost segregation worth it for high-net-worth investors in 2026?
Cost segregation for high net worth investors remains one of the most effective tools for immediate liquidity. Even with legislative shifts, the ability to front-load depreciation expenses allows you to reinvest capital into higher-yielding assets today. By reducing your current federal tax liability, you effectively create an interest-free loan from the government. This strategy is particularly valuable when managing large portfolios where tax drag can significantly impede your long-term wealth accumulation and compounding goals.
What is the impact of bonus depreciation phase-outs on cost segregation?
The scheduled phase-down means bonus depreciation will reach 20% in 2026. While the immediate first-year deduction is lower than in previous years, the core benefit of cost segregation remains unchanged. You're still reclassifying assets from a 39-year life to 5, 7, or 15-year recovery periods. This technical reclassification ensures you're maximizing the present value of your tax savings regardless of the specific bonus percentage available in a given tax year.
Can cost segregation be used for residential rental properties?
Yes, residential rental properties are excellent candidates for these studies. Whether you own multi-family complexes or a portfolio of single-family rentals, many building components qualify for accelerated depreciation. Items such as specialized cabinetry, decorative lighting, and site improvements like fencing or driveways can be moved to shorter recovery periods. This approach is especially powerful for investors who meet the criteria for Real Estate Professional Status to offset their active income.
How does cost segregation affect a 1031 exchange?
Cost segregation creates a synergy with 1031 exchanges but requires precise technical management. When you swap properties, you must account for the depreciation recapture of personal property components. We provide specialized 1031 exchange facilitation to ensure that the replacement property has sufficient qualifying assets to absorb the carryover basis. This coordination prevents unexpected tax hits and preserves the full amount of equity you've built within your commercial or residential real estate holdings.
Does cost segregation increase the risk of an IRS audit?
A professionally prepared engineering-based study actually provides a layer of security. The IRS has a specific Audit Techniques Guide for cost segregation for high net worth investors, and our reports are designed to meet those exact technical standards. By using blueprints, site visits, and detailed cost modeling, we provide the substantiation that auditors look for. This level of precision is far more defensible than using rule-of-thumb percentages, which are often the primary red flags that trigger IRS inquiries.
What is the difference between an accounting-based and an engineering-based study?
Accounting-based studies often rely on high-level estimates or industry averages, which lack the technical depth required for high-value properties. In contrast, an engineering-based study involves a physical inspection and a detailed breakdown of building systems by licensed professionals. This method identifies specific electrical, plumbing, and mechanical components that qualify for shorter lives. The IRS explicitly prefers the engineering approach because it provides the most accurate and verifiable data for asset reclassification.
Can I perform a cost segregation study on a property I have owned for several years?
You can absolutely perform a study on a property acquired in a previous tax year. This is known as a look-back study and utilizes a Section 481(a) adjustment. It allows you to claim all the depreciation you missed in previous years in a single current-year filing. You don't need to go through the hassle of amending prior tax returns, making it an efficient way to unlock significant cash flow from your existing real estate portfolio.
How much does a cost segregation study typically cost for a HNWI?
The professional service fees for a study are determined by the complexity and scale of the property rather than a flat rate. Factors such as the building's size, its specific use, and the level of engineering detail required all influence the final cost. However, the focus for most investors is the return on investment. The tax savings generated typically represent a significant multiple of the fee, providing a clear path to improved liquidity and reinvestment capital.