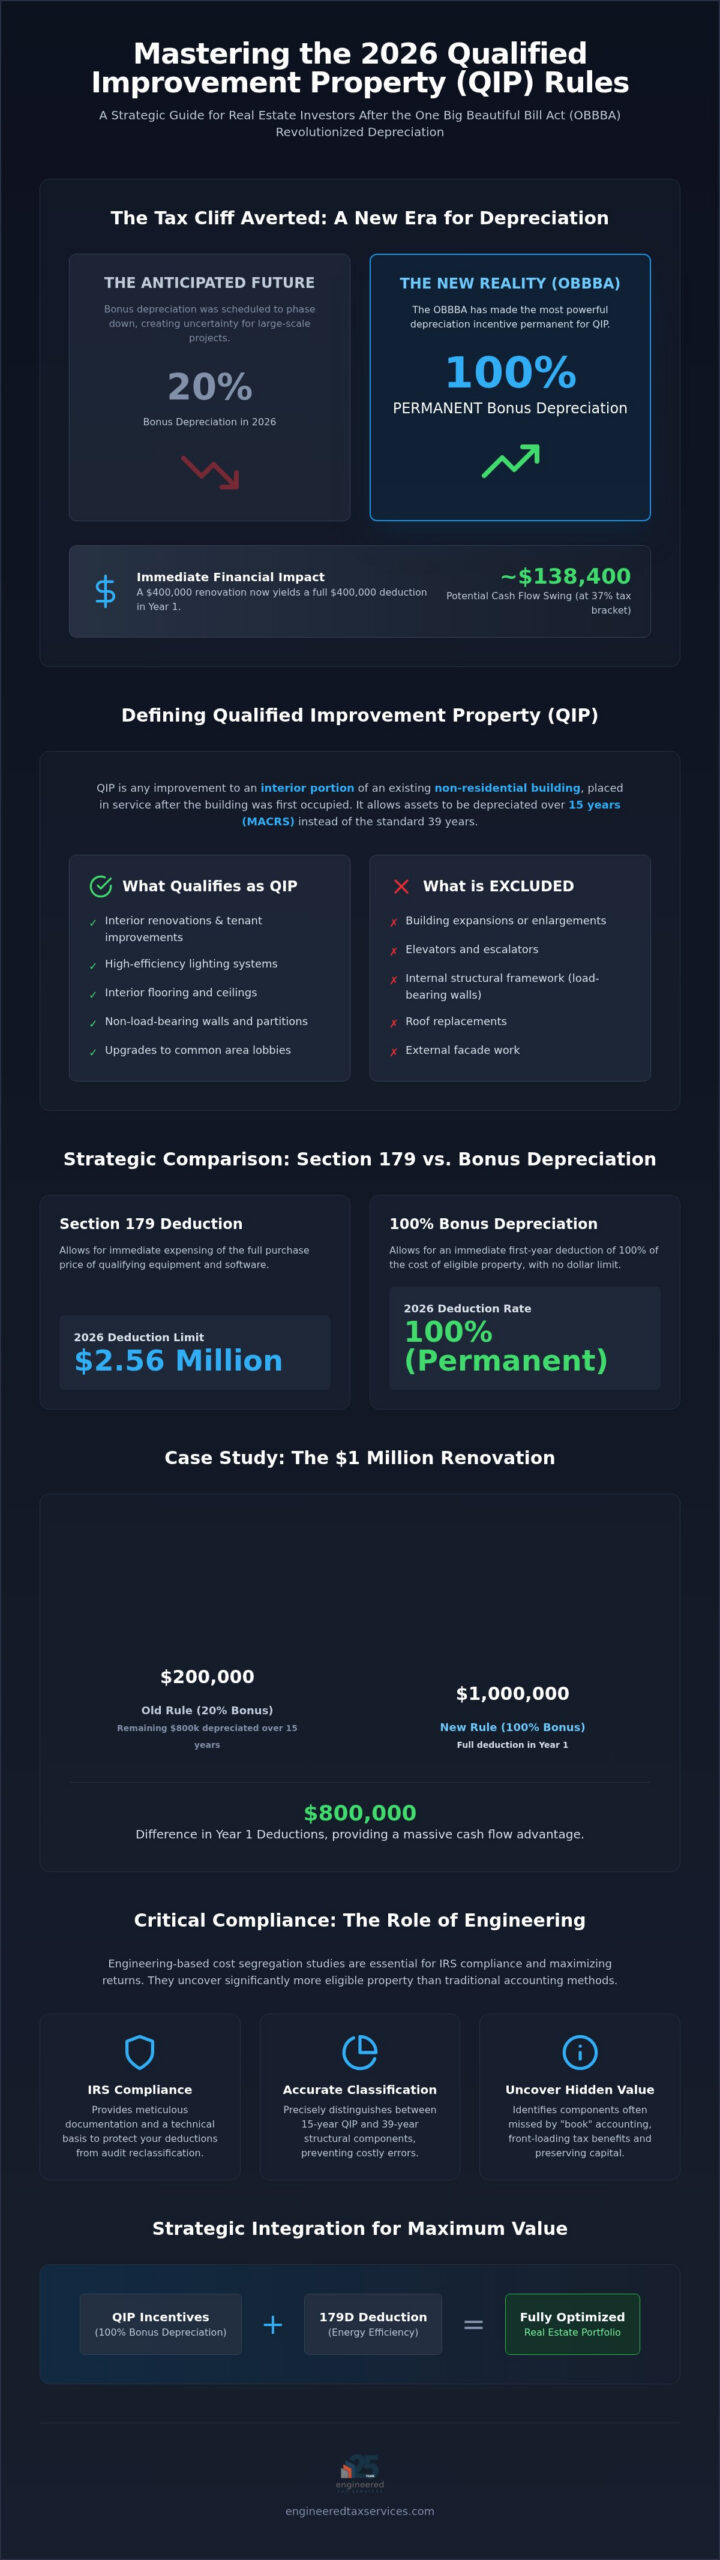
The widely anticipated “tax cliff” for real estate investors has been officially averted. While many prepared for a world where incentives dwindled to a mere 20%, the enactment of the One Big Beautiful Bill Act (OBBBA) has fundamentally shifted the qualified improvement property depreciation rules 2026. Instead of a phase-down, taxpayers now have access to permanent 100% bonus depreciation for eligible interior renovations. This means a $400,000 project can still yield a full $400,000 deduction in year one, creating a potential cash flow swing of approximately $138,400 for those in the 37% federal bracket.
It's natural to feel some whiplash from these rapid legislative changes. Staying compliant while maximizing your return requires more than just basic accounting; it demands technical precision. This strategic guide will help you master the 2026 QIP landscape, clarify the nuances between Section 179 and bonus depreciation, and leverage engineering-based studies to secure your deductions. We'll explore the current $2.56 million Section 179 limit, the 15-year MACRS recovery period, and the specific documentation needed to satisfy IRS scrutiny on large-scale improvement projects.
Key Takeaways
- Discover how the One Big Beautiful Bill Act (OBBBA) revolutionized the qualified improvement property depreciation rules 2026 by establishing permanent 100% bonus depreciation for eligible interior renovations.
- Navigate the $2.56 million Section 179 deduction limit and understand how to strategically apply this first-year expensing to maximize immediate cash flow.
- Identify the specific technical criteria for QIP eligibility to ensure your interior projects qualify for a 15-year recovery period while excluding structural framework and elevators.
- Learn why engineering-based cost segregation is essential for IRS compliance, often uncovering significantly more eligible property than traditional “book” accounting methods.
- Explore the strategic integration of QIP incentives with the 179D energy efficient commercial building deduction to unlock the full potential of your real estate portfolio.
Defining Qualified Improvement Property (QIP) in the 2026 Landscape
Qualified Improvement Property (QIP) is defined as any improvement to an interior portion of an existing non-residential building placed in service after the building was first occupied, and it's specifically classified as 15-year property under the Modified Accelerated Cost Recovery System (MACRS). This classification remains a cornerstone of tax strategy for commercial real estate investors. Under the qualified improvement property depreciation rules 2026, shifting assets from a standard 39-year life to a 15-year schedule allows owners to significantly front-load their tax benefits. This preservation of capital is essential for funding future acquisitions or sustaining operational growth. Even without the added benefit of bonus depreciation, the 15-year recovery period offers a much faster return on investment compared to traditional commercial structures.
QIP Eligibility Requirements for Commercial Owners
To qualify for these accelerated benefits, improvements must be made to a building that's already operational. This excludes first-generation build-outs in new construction projects. Whether you're upgrading common area lobbies or funding specific tenant improvements, the technical distinction lies in the timing and location of the work. For 2026 projects, meticulous documentation is non-negotiable. You need clear records showing that the building was occupied before the improvements began. This precision ensures that your project meets the strict criteria set by the IRS, protecting your cash flow from potential reclassification during an audit. Proper documentation bridges the gap between a successful claim and a costly oversight.
Common Misconceptions: What QIP Is Not
Confusion often arises regarding what actually constitutes an interior improvement. The law is specific about exclusions. You cannot include building expansions, elevators, escalators, or any work affecting the internal structural framework. For instance, while high-efficiency lighting and flooring qualify, replacing a roof or modifying load-bearing walls does not. External facade work is also disqualified, as the improvements must be strictly internal. Understanding these boundaries prevents costly errors in your tax filings. Our engineering-based approach helps distinguish between these categories, ensuring that every dollar spent on your renovation is correctly classified under the most advantageous depreciation schedule possible. It's this level of detail that separates a standard tax filing from a strategic wealth-preservation plan.
The 2026 Bonus Depreciation Phase-Down: Navigating the 20% Rule
The Tax Cuts and Jobs Act (TCJA) originally set a strict trajectory for bonus depreciation, moving from 100% down to a 20% floor for the 2026 tax year. This phase-down created significant concern for commercial owners planning large-scale renovations, as it threatened to delay the recovery of capital. Under the qualified improvement property depreciation rules 2026, the “placed in service” date is the ultimate arbiter of which rate applies. If a project isn't fully operational by December 31, you risk falling into a different tax bracket or incentive tier. While the 15-year MACRS schedule remains a powerful fallback for any remaining basis, the goal for most investors is to maximize that immediate first-year deduction.
Calculating the 20% Benefit for Large-Scale Renovations
Consider a $1 million interior renovation completed in 2026. Under the original 20% phase-down, your year-one bonus deduction would be $200,000. You'd then depreciate the remaining $800,000 over 15 years as outlined in IRS Publication 946. However, the legislative landscape shifted with the One Big Beautiful Bill Act (OBBBA), which restored the 100% rate. This change means that same $1 million project now yields a full $1 million deduction immediately. This $800,000 difference in year-one deductions provides a massive cash flow advantage. Understanding how the qualified improvement property depreciation rules 2026 apply to these components ensures you don't leave money on the table. You can consult with a specialist to verify your project's eligibility under these updated standards.
Engineering-based cost segregation is more critical than ever to ensure every component of that spend is accurately classified to withstand IRS scrutiny. Even with the restoration of the 100% rate, the technical documentation required to prove an asset qualifies as QIP remains rigorous. Precise classification prevents the IRS from reclassifying your 15-year property back to a 39-year life, which would drastically reduce your immediate tax savings.
Future Outlook: The 2027 Cliff and Planning Ahead
This legislative shift provides much-needed stability by making the 100% rate permanent for property acquired after January 19, 2025. It effectively removes the “2027 cliff” where bonus depreciation was scheduled to vanish entirely. Investors no longer need to rush projects purely to beat a declining percentage. Instead, the focus can shift to long-term strategic implementation and technical documentation. We continue to monitor legislative updates, but the current path favors those who invest in high-quality, documented improvements. This permanence allows for more deliberate capital allocation across your entire portfolio, ensuring that tax strategy remains a driver of growth rather than a source of uncertainty.
Section 179 vs. Bonus Depreciation for QIP: A 2026 Comparison
Choosing between Section 179 and bonus depreciation isn't just about picking a rate; it's about aligning your tax strategy with your current year's income. Under the qualified improvement property depreciation rules 2026, both mechanisms offer a 100% first-year deduction, yet they operate under vastly different constraints. Section 179 is limited by a $2.56 million deduction cap and a $4.09 million phase-out threshold, making it a targeted tool for specific asset management. Conversely, bonus depreciation remains the most flexible option for larger portfolios because it has no investment ceiling and can create a net operating loss (NOL) to offset future income. For the 2026 tax year, Section 179 offers a $2.56 million deduction cap for targeted expensing, while bonus depreciation provides a permanent 100% allowance for all other eligible qualified improvement property.
When to Prioritize Section 179 for Improvements
Section 179 is particularly effective for small to mid-sized commercial properties where the total equipment and improvement spend stays below the $4.09 million phase-out mark. One critical advantage of Section 179 is its ability to cover certain non-QIP assets like roofs or HVAC systems that are otherwise ineligible for bonus depreciation. However, you must have sufficient taxable income to utilize this deduction. Unlike bonus depreciation, Section 179 can't be used to drive your taxable income below zero. If your renovation project is large enough to create a loss, bonus depreciation is the technically superior choice to preserve that value as a carryforward. This allows you to protect your long-term wealth by carrying that loss into future profitable years.
The Synergy: Combining Both Strategies for Maximum Impact
Strategic investors often utilize a specific order of operations to maximize their immediate tax savings. By applying Section 179 first to assets that don't qualify for bonus depreciation, you preserve your bonus eligibility for the remaining QIP basis. This dual approach is vital for high-net-worth investors managing multiple properties across a national portfolio. It allows for a surgical application of tax benefits, ensuring that no capital is left idle. Integrating these two strategies requires the technical precision of an engineered study to correctly identify and segregate every eligible component. This level of analysis ensures that your 2026 filings are both optimized for cash flow and fully compliant with current IRS standards. By leveraging both tools, you create a robust shield against over-taxation while maintaining the flexibility to reinvest in your portfolio's growth.
Critical Compliance: Engineering Requirements for QIP Identification
Standard book accounting often fails to capture the full scope of eligible assets, typically missing 10-15% of the value that should be classified as QIP. While many property owners rely on general ledger entries or simple tax software, the IRS Cost Segregation Audit Techniques Guide clearly establishes engineering-based studies as the gold standard for substantiation. Under the qualified improvement property depreciation rules 2026, relying on surface-level records leaves your portfolio vulnerable during a federal review. Technical precision is required to identify “hidden” QIP buried within complex electrical and mechanical systems. For example, dedicated plumbing lines for a specific tenant or specialized electrical circuits often qualify for accelerated treatment, yet they're frequently lumped into 39-year structural costs by traditional accounting methods. Our licensed engineers bridge this gap by providing the technical evidence necessary to defend your deductions.
The Role of an Engineering-Based Tax Study
A professional study moves beyond lump-sum renovation contracts by performing a granular, component-level analysis of every invoice and blueprint. We dissect your project to differentiate between 5-year personal property, 7-year equipment, and 15-year QIP. This distinction is vital for maximizing cash flow while maintaining a conservative, defensible tax position. Engineering-based cost segregation identifies assets that are physically part of the building but legally classified as shorter-lived property due to their specific function. This level of detail is particularly important when navigating the interplay between different asset classes within a single large-scale renovation, ensuring you don't leave capital on the table.
Substantiating the ‘Interior' Requirement
The IRS is focused on the “interior” and “placed in service” requirements. You must prove the building was occupied prior to the improvements and that no work affected the structural framework. We use technical site visits, detailed blueprints, and contemporary photographs to create a permanent record of the project's non-structural status. In the 2026 tax environment, these records are your primary defense against reclassification. The definition of “structural” is often a point of contention with the IRS; our engineers provide the technical definitions required to prove that your interior glass partitions or decorative millwork don't support the building's load. Contemporaneous documentation ensures that your claims remain secure during an audit.
To ensure your documentation meets these rigorous standards and captures every dollar of eligible incentive, you should schedule an Engineered Incentives Report with our technical team today.
Strategic Implementation: Optimizing QIP with Engineered Tax Services
Realizing the full potential of a commercial renovation requires a synthesis of technical engineering and tax law. Engineered Tax Services (ETS) specializes in this intersection, ensuring that every asset is classified with the precision required by the qualified improvement property depreciation rules 2026. This technical approach is especially valuable for “Catch-Up” opportunities. If you failed to claim accelerated depreciation on prior-year improvements, IRS Form 3115 allows you to claim those missed deductions in the current year without amending past returns. This strategy unlocks immediate liquidity, providing the capital needed for new acquisitions or portfolio expansion. By correcting these classifications, you transform static assets into active cash flow.
Maximizing ROI Through Comprehensive Cost Segregation
Cost segregation for commercial property is the primary vehicle for optimizing QIP. By accelerating depreciation from 39 years to 15, 7, or 5 years, you dramatically increase the net present value (NPV) of your tax savings. For a 2026 improvement project, the difference between standard accounting and an engineered study can mean hundreds of thousands of dollars in year-one cash flow. We perform over 10,000 studies annually, focusing on wealth preservation through technical accuracy. This isn't just about compliance; it's about the strategic preservation of capital. Our engineers identify components that typical accounting methods overlook, ensuring your project's ROI is fully realized.
Complementary Strategies: 179D and 45L
The true power of an engineered approach lies in layering multiple incentives. You can often integrate QIP benefits with the 179D energy efficient commercial building deduction. While QIP focuses on interior improvements, 179D provides deductions for energy-efficient lighting, HVAC, and building envelope systems. For multifamily developers, 45L tax credits for multifamily projects can be stacked alongside QIP rules to further reduce your tax liability. This holistic strategy ensures that every aspect of a sustainable renovation is financially optimized. Our team coordinates these disparate incentives into a single, cohesive wealth-building plan that maximizes your total tax benefit.
Don't leave your tax strategy to chance. Contact Engineered Tax Services for a complimentary QIP analysis to see how we can maximize your 2026 cash flow and secure your portfolio's financial future.
Secure Your Portfolio's Future Through Technical Precision
The recent shift to permanent 100% bonus depreciation provides a rare window for aggressive yet compliant wealth preservation. Mastering the qualified improvement property depreciation rules 2026 requires more than just high-level accounting; it demands a rigorous, engineering-based approach to ensure every deduction is substantiatable. By correctly segregating interior improvements and layering incentives like 179D, you can transform your tax liability into a powerful strategic advantage. This level of detail is essential for maintaining liquidity in a competitive market.
As an independent, licensed engineering firm performing over 10,000 tax studies annually, we provide the technical precision needed to maximize your returns. Our reports offer IRS-defensible technical documentation that protects your wealth while unlocking hidden capital. It's time to move beyond standard compliance and embrace a proactive strategy for your real estate investments. Optimize Your 2026 Tax Strategy with an Engineering-Based Study today and take the first step toward long-term financial stability. Your portfolio's growth depends on the accuracy of your strategy, and we're here to ensure you capture every available benefit.
Frequently Asked Questions
What exactly qualifies as Qualified Improvement Property (QIP) in 2026?
QIP consists of any improvement to the interior portion of an existing non-residential building placed in service after the building was first occupied. This category covers renovations like new flooring, lighting, and interior walls. However, you must exclude building enlargements, elevators, escalators, and internal structural framework. Under the qualified improvement property depreciation rules 2026, these assets are classified as 15-year property, which allows for significantly faster capital recovery than standard 39-year commercial structures.
Can I still claim 100% bonus depreciation in 2026?
Yes, you can claim 100% bonus depreciation in 2026 for property acquired and placed in service after January 19, 2025. The One Big Beautiful Bill Act (OBBBA) made this incentive permanent, reversing the previous phase-down schedule. This legislation provides commercial owners with a reliable mechanism for immediate expensing. It ensures that your entire investment in eligible interior improvements can be deducted in the first year, drastically improving your project's immediate cash flow and overall net present value.
What is the difference between QIP and Section 179 expensing?
The primary difference is that Section 179 has strict dollar caps and income limits, while bonus depreciation does not. Section 179 allows for dollar-for-dollar deductions up to a $2.56 million limit for 2026, but it cannot create a tax loss. In contrast, bonus depreciation for QIP has no investment cap, allowing you to drive taxable income below zero. The qualified improvement property depreciation rules 2026 favor bonus depreciation for large-scale renovations across national portfolios.
How do the 2026 QIP rules apply to leased office spaces?
Improvements to leased office spaces qualify for accelerated depreciation if the work is performed on the building's interior after the structure was first occupied. These tenant improvements (TIs) are treated as 15-year property, making them eligible for 100% bonus depreciation. This applies regardless of whether the landlord or the tenant pays for the renovation. Strategic documentation is required to ensure these build-outs don't include structural modifications, which would disqualify the assets from the QIP classification.
Does QIP apply to residential rental properties like apartment buildings?
QIP specifically excludes residential rental properties, such as apartment buildings or single-family rentals. The tax code defines QIP as improvements made to non-residential real property. If you own residential assets, you can't use the QIP 15-year schedule, but you can still utilize cost segregation to identify 5-year or 7-year personal property within those buildings. This alternative strategy still allows for significant front-loaded depreciation through bonus incentives, even without the specific QIP designation.
What happens if I don't use a cost segregation study for my improvements?
Without a cost segregation study, you'll likely default to a 39-year depreciation schedule for all renovation costs. This oversight results in significantly slower capital recovery and reduced year-one cash flow. Simple accounting often misses technical components like specialized electrical or plumbing that qualify for shorter lives. An engineering-based study provides the IRS-defensible documentation needed to reclassify these costs, ensuring you capture the full 100% bonus depreciation benefit while protecting your claims during a potential audit.
Can I use QIP depreciation rules for a building I just purchased?
You can use QIP rules for improvements you initiate after the purchase, but the existing building structure itself does not qualify. QIP must be an improvement made by the taxpayer to the interior of a building that was already in service. If you buy a building and immediately start an interior renovation, those new costs are eligible for 15-year treatment and 100% bonus depreciation. The original purchase price of the building remains subject to standard 39-year commercial depreciation rules.
Is there a limit to how much QIP I can depreciate in one year?
No, there's no ceiling on the total amount of QIP you can depreciate in a single year through bonus depreciation. Unlike Section 179, which has a $2.56 million cap for 2026, bonus depreciation allows for the full expensing of any eligible interior renovation regardless of the total cost. This makes it an exceptionally powerful tool for developers and high-net-worth investors managing multi-million dollar renovation projects across multiple commercial properties throughout the United States.