What if your rental property wasn't just a source of monthly income, but a sophisticated tax shield capable of generating six figures in immediate liquidity? Most investors accept the standard 27.5 or 39 year depreciation schedules as an unavoidable reality of real estate ownership. You likely feel the weight of high tax liabilities eroding your monthly cash flow, especially if you haven't yet optimized cost segregation for rental property to reclaim your capital. It's a common frustration to watch potential growth funds sit locked away in a building's structure for decades while fearing the complexity of IRS compliance.
This 2026 guide will show you how to unlock the engineering-based strategies used by high-net-worth investors to accelerate depreciation and maximize cash flow on residential and commercial rentals. By reclassifying building components into shorter recovery periods, you can leverage the permanent 100% bonus depreciation established by the One Big Beautiful Bill Act. We'll examine how to secure a defensible engineering report that stands up to scrutiny while aligning your tax strategy with wealth-building tools like 1031 exchanges. You'll learn exactly how to transform passive depreciation into a proactive engine for portfolio expansion and long-term stability.
Key Takeaways
- Understand how reclassifying building components can transform your tax liability into immediate liquidity by moving assets to shorter recovery periods.
- Don't rely on simple estimates; learn why a rigorous, engineering-based methodology is essential for alignment with the IRS Audit Techniques Guide.
- Master the 2026 bonus depreciation rules to capture the available 20% rate, helping you front-load deductions before the scheduled phase-down.
- Follow a structured process for implementing cost segregation for rental property, from the initial feasibility analysis to gathering essential construction data.
- Identify how to integrate your depreciation strategy with other specialized incentives like 179D or 45L credits to maximize your long-term portfolio growth.
What is Cost Segregation for Rental Property?
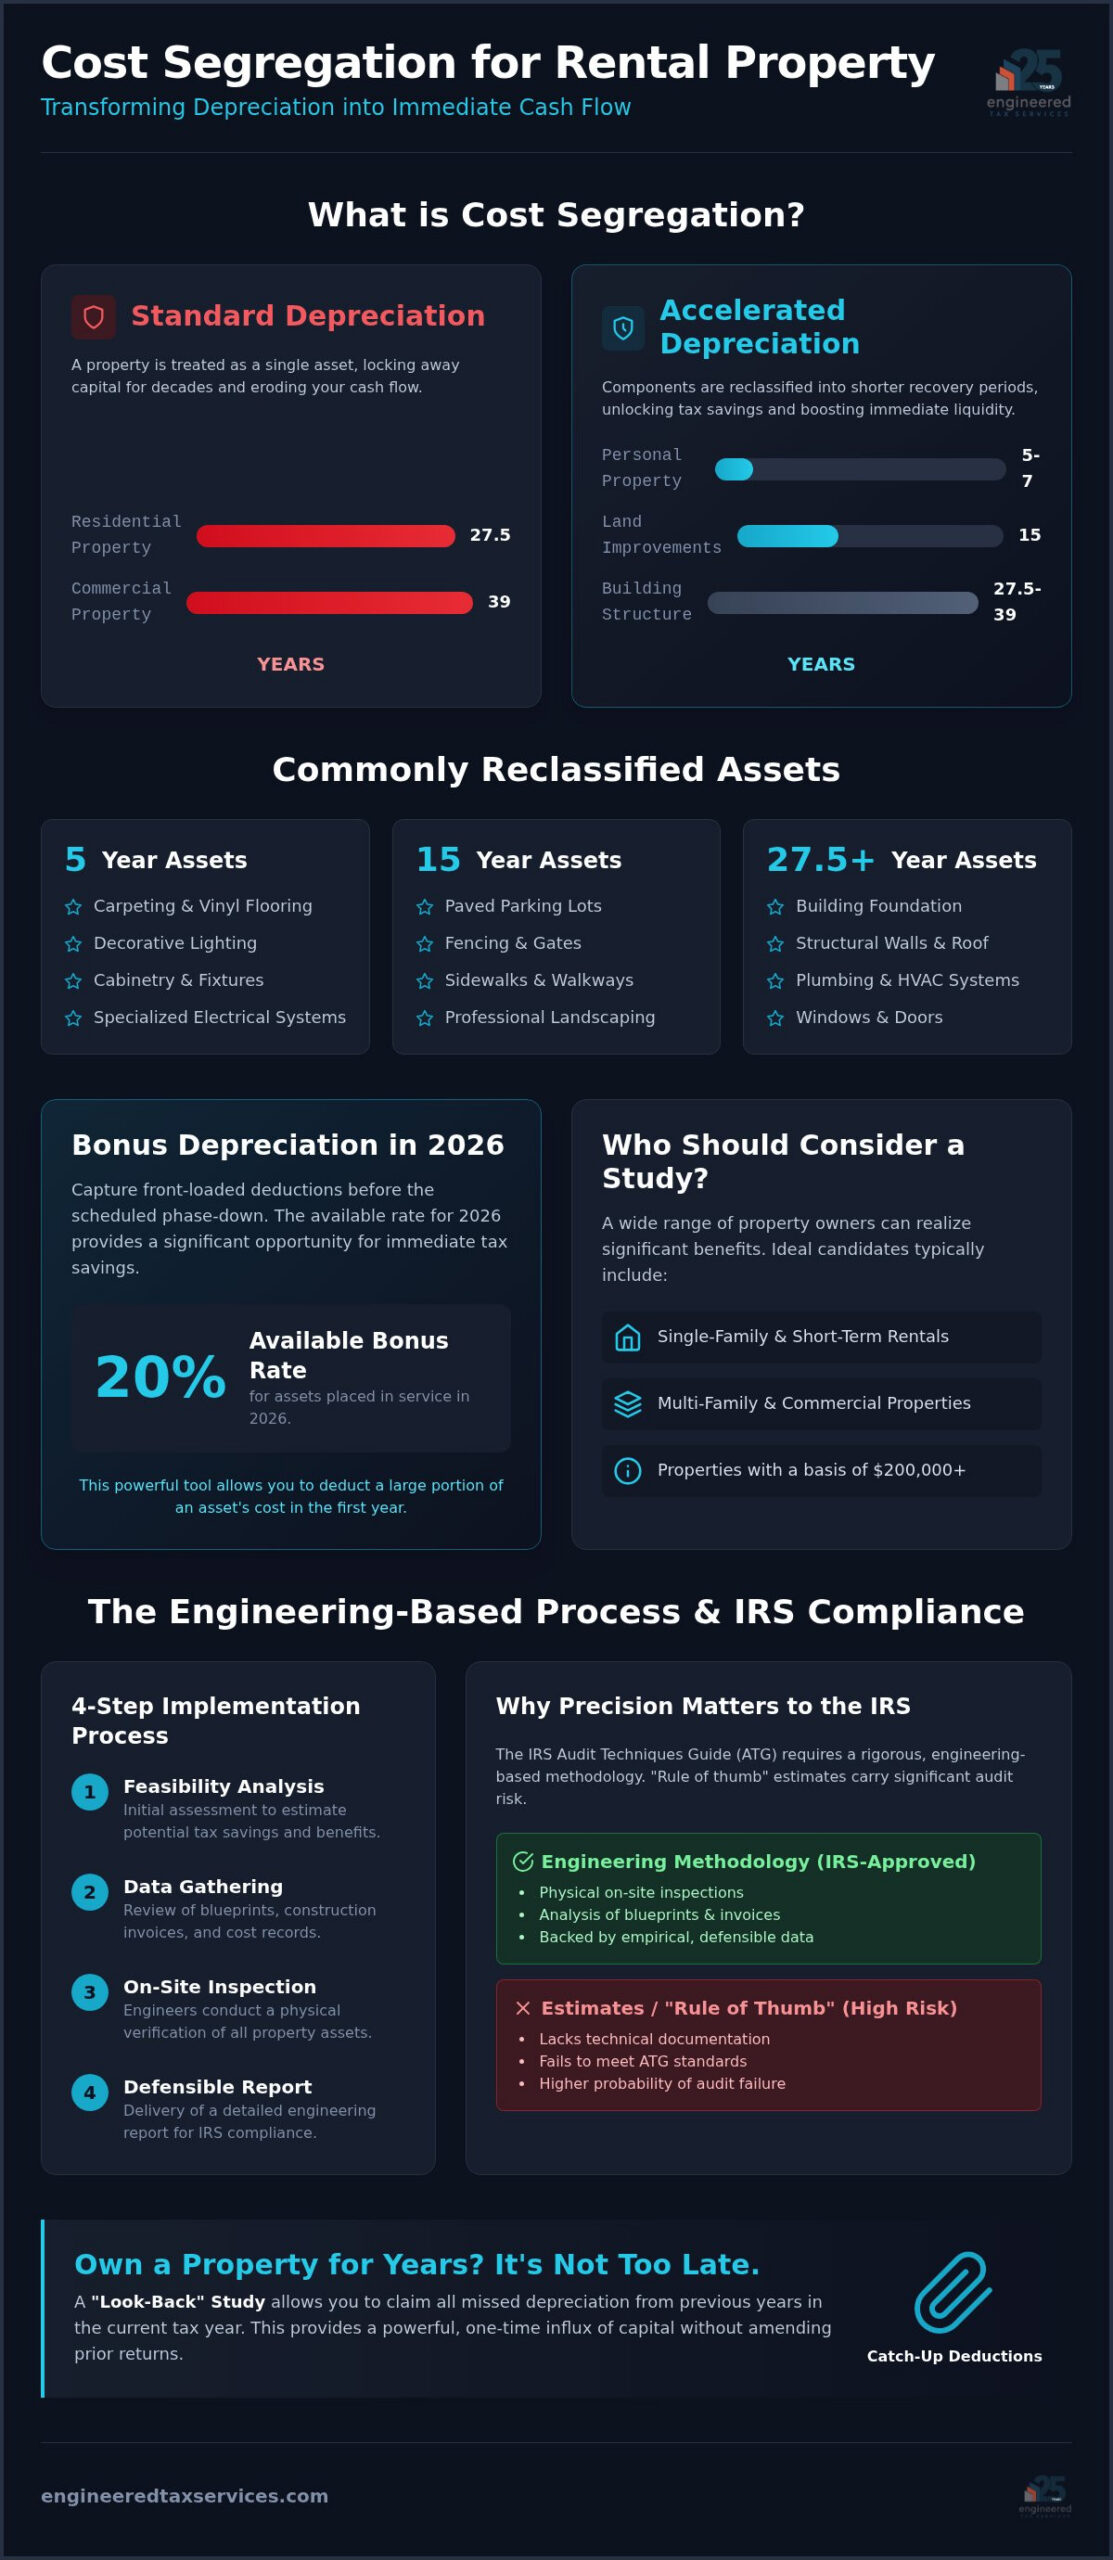
Cost segregation for rental property is a strategic tax planning tool that separates real estate into its individual components. Instead of treating a building as a single structural unit, an engineering-based cost segregation study identifies specific assets that the IRS allows you to depreciate over a much faster timeline. Standard IRS rules typically require residential properties to be depreciated over 27.5 years and commercial properties over 39 years. This slow pace often leaves significant capital trapped within the property's walls for decades. By reclassifying personal property and land improvements, you shift these costs into 5, 7, or 15-year recovery periods. This isn't just about compliance; it's about the time value of money. A dollar of tax savings captured today is inherently more valuable than that same dollar received two decades from now because it can be immediately reinvested into your portfolio to drive compounded growth.
The Mechanics of Accelerated Depreciation
The process involves a granular analysis of the property to isolate assets that aren't part of the building's core structure. While the roof and foundation remain on a long-term schedule, many other elements qualify for accelerated treatment. Identifying these assets requires a blend of engineering expertise and tax law knowledge. Commonly reclassified assets include:
- 5-year assets: Decorative lighting, specialized electrical systems for equipment, cabinetry, and certain flooring like carpeting or vinyl.
- 15-year assets: Land improvements such as paved parking lots, fencing, sidewalks, and professional landscaping.
Accelerating these deductions creates a substantial non-cash expense that offsets rental income. This directly increases your near-term cash flow, providing the liquidity needed to acquire new units or fund capital improvements without seeking external financing. It's a proactive way to preserve capital while building long-term stability.
Who Should Consider a Cost Segregation Study?
While cost segregation was once reserved for institutional investors, it's now a vital tool for a wide range of property owners. High-net-worth individuals managing single-family rentals (SFRs), multi-family complexes, and short-term rentals can all realize significant benefits. Generally, properties with a depreciable basis of $200,000 or more are strong candidates for a study, though the exact threshold depends on the specific asset mix and your tax bracket. If you've owned a property for several years without optimizing its depreciation, you don't need to miss out on the benefits. A look-back study allows you to claim all the missed depreciation from previous years in the current tax year through a simple accounting method change. This provides a powerful mechanism for a sudden, strategic influx of capital without the need to amend prior returns.
The Engineering Methodology: Why Precision Matters to the IRS
The IRS doesn't accept “rule of thumb” percentages when you apply cost segregation for rental property. While some providers use simplified accounting-based estimates, these often fail to meet the rigorous standards outlined in the IRS Cost Segregation Audit Techniques Guide (ATG). A quality study requires a technical bridge between tax law and structural engineering. Licensed engineers are uniquely qualified to perform this work because they can dissect building systems, interpret blueprints, and conduct on-site physical inspections to identify assets that a general accountant might overlook. This level of technical precision ensures that every reclassified dollar is backed by empirical data rather than speculation.
- A thorough review of architectural blueprints and construction drawings.
- Physical on-site inspections to verify the existence and condition of assets.
- Analysis of contractor invoices and itemized cost records.
- Professional cost estimating using industry-standard engineering software.
IRC Section 1245 vs. Section 1250 Property
Distinguishing between personal property and structural components is the core of this strategy. According to IRS Publication 946, assets are categorized based on their function and permanence. Section 1245 property includes tangible personal property like specialized lighting, decorative millwork, or removable flooring. These qualify for a 5 or 7 year life. Conversely, Section 1250 property consists of structural components like walls, plumbing, and HVAC systems that must follow the standard 27.5 or 39 year schedule. Engineering expertise provides the “bright line” needed to determine if an asset is truly removable or incidental to the building's operation, preventing errors that could compromise your filing.
The Risk of Inaccurate Reclassification
Aggressive reclassification without a technical basis is a red flag for auditors. If a study lacks a site visit or detailed cost records, the IRS may disqualify the accelerated deductions, leading to back taxes and penalties. A defensible, engineering-based report provides the institutional security needed to withstand scrutiny. It's a proactive safeguard for your financial health and long-term portfolio stability. You can consult with a licensed engineering firm to ensure your assets are valued with absolute precision. An engineering-based methodology is the gold standard for IRS compliance.
Bonus Depreciation in 2026: Navigating the Phase-Down
2026 represents a critical juncture for real estate tax strategy. Under the Tax Cuts and Jobs Act (TCJA), bonus depreciation has been undergoing a structured phase-down since its peak. For assets placed in service during the 2026 calendar year, the bonus depreciation rate is 20%. While this is a significant decrease from the 100% or 80% rates seen in previous years, cost segregation for rental property remains a potent tool for capital preservation. Even a 20% first-year deduction on reclassified assets provides a substantial cash flow advantage over the standard straight-line method, which would otherwise stretch those same deductions over nearly three or four decades.
Strategic timing is essential to capturing these benefits. To qualify for the 2026 rate, your property must be “placed in service”—meaning it's ready and available for its specific income-producing use—by December 31, 2026. This makes the upcoming months a vital window for investors to finalize acquisitions or complete renovations. Properly documenting this timeline ensures you don't inadvertently slide into the 0% bonus depreciation scheduled for 2027.
Comparison of Depreciation Strategies
The difference between standard straight-line depreciation and an accelerated approach is often the difference between a stagnant portfolio and one that's ready for expansion. While straight-line depreciation offers a predictable, slow burn, cost segregation front-loads your deductions. Consider a hypothetical $1,000,000 residential rental property where an engineering study reclassifies 25% of the basis into 5 and 15-year assets:
- Standard Straight-Line (Year 1): Approximately $36,363 in deductions.
- Cost Segregation with 20% Bonus (Year 1): Approximately $75,000+ in deductions (including the 20% bonus on the $250,000 reclassified portion plus regular depreciation).
This strategy is particularly effective when paired with the “Short-Term Rental Loophole.” If your property's average guest stay is seven days or less and you materially participate in the operation, the resulting depreciation losses can often offset active income, such as W-2 wages. This creates a massive opportunity for high-earning professionals to shield their income while building real estate equity.
The 2026 Tax Planning Window
Because 2026 is the final year for bonus depreciation before it potentially hits 0% in 2027, it's the last chance for many to maximize immediate expensing. However, the strategy isn't limited to new acquisitions. If you've owned a property for years but never performed a study, you can utilize “catch-up” depreciation. By filing IRS Form 3115, you can claim all the depreciation you missed in previous years in a single tax return without amending prior filings. This provides an immediate influx of liquidity that can be used for new down payments or debt reduction. For those managing more complex portfolios, understanding depreciation strategies for commercial real estate can provide additional layers of wealth optimization across different asset classes.
Implementing a Cost Segregation Study: Step-by-Step Process
Executing a successful cost segregation for rental property requires a methodical approach that bridges the gap between physical engineering and tax law. This isn't a simple accounting entry; it's a rigorous technical process designed to withstand IRS scrutiny while maximizing your immediate liquidity. The lifecycle of a study typically follows five distinct phases:
- Step 1: Feasibility Analysis. A preliminary evaluation determines if the projected tax savings justify the investment. A reputable firm will provide an estimated range of benefits before you move forward.
- Step 2: Information Gathering. You'll provide essential documents such as closing statements, appraisals, and, for new construction, contractor pay applications or “sworn statements.”
- Step 3: Engineering Review and Site Inspection. A licensed engineer conducts a physical walkthrough to identify and document non-structural assets, from specialized electrical circuits to site improvements.
- Step 4: Report Finalization. Engineers apply cost-estimation data to allocate the building's basis into the correct IRS recovery periods (5, 7, 15, or 27.5/39 years).
- Step 5: Tax Filing. Your CPA uses the final report to adjust your depreciation schedule. For properties owned in prior years, this involves filing IRS Form 3115 to claim “catch-up” depreciation.
Gathering the Necessary Documentation
Precision begins with data. Your engineering partner will need a comprehensive checklist to ensure the report is defensible. Key items include the final closing disclosure, property surveys, and architectural floor plans if available. If you're dealing with an older property where original construction records are missing, don't worry. Specialized engineers use industry-standard cost-estimation manuals, such as RSMeans, to accurately reconstruct the value of components based on the year of construction. Your CPA plays a vital role here by ensuring the final cost segregation data integrates seamlessly with your overall tax return. To get started with a professional review of your portfolio, you can request a feasibility analysis from a licensed engineering firm.
Avoiding Common Pitfalls in Rental Studies
While the benefits are substantial, you must account for specific IRS limitations. Passive activity loss rules under Section 469 can restrict your ability to use large depreciation deductions if you don't qualify as a Real Estate Professional or meet the material participation requirements for the short-term rental loophole. Additionally, consider depreciation recapture. When you eventually sell the property, the IRS will “recapture” the accelerated portion of the depreciation at ordinary income tax rates. This makes cost segregation most effective for investors planning to hold assets long-term or those utilizing 1031 exchanges to defer those gains. Selecting a “cheap” study that lacks a physical site visit or engineering documentation is often a false economy; the cost of an IRS audit and subsequent disqualification of deductions far outweighs the initial savings of a cut-rate report.
Strategic Wealth Optimization with Engineered Tax Services
Maximizing the benefits of cost segregation for rental property requires more than a standard accounting exercise; it demands a partnership with a firm that sits at the intersection of engineering and tax law. Engineered Tax Services (ETS) is a licensed engineering firm that serves as the “Expert’s Expert” for high-net-worth investors and their professional advisors. With a national authority built on conducting over 10,000 studies annually, we provide the technical precision required to ensure your deductions are both maximized and defensible. Our role isn't just to deliver a report, but to act as a proactive advocate for your financial health throughout the entire property lifecycle, from acquisition and renovation to eventual disposition.
Choosing a specialized partner provides a level of institutional knowledge that generalist firms cannot match. Our engineers understand the nuances of building systems and the specific IRS requirements for technical documentation. This precision creates a foundation of security, allowing you to focus on portfolio growth while we handle the complexities of valuation and reclassification. We bridge the gap between different professional disciplines to ensure your tax strategy is as robust as your investment strategy.
Synergistic Tax Incentives for Real Estate
A sophisticated wealth strategy doesn't view cost segregation in isolation. For developers and owners of multifamily rentals, we identify opportunities to layer multiple incentives for exponential cash flow impact. This often includes pairing accelerated depreciation with the 45L tax credit multifamily for energy-efficient residential units. If your portfolio includes larger mixed-use or commercial assets, we can integrate the 179D energy efficient commercial building deduction to further reduce your tax liability. When the time comes to sell, our 1031 exchange services facilitate seamless capital preservation, ensuring your hard-earned equity continues to work for you in your next acquisition.
Taking the Next Step in Your Tax Strategy
The path to optimized cash flow begins with a clear understanding of your property’s potential. We offer a complimentary feasibility analysis to help you determine the exact ROI of a study before you commit any resources. During your initial consultation, an ETS engineer will review your portfolio and identify the most impactful incentives available for your specific asset class. For those managing larger, high-stakes portfolios, you can also explore our pillar guide on cost segregation commercial property to understand how engineering-based optimization scales with your growth. Don't leave your capital trapped in your building's structure; let us help you unlock its full potential.
Secure Your Real Estate Wealth Strategy
Navigating the complexities of tax law requires more than just a reactive approach; it demands a strategic partnership built on technical precision. As bonus depreciation rates transition to 20% in 2026, the window to capture significant near-term liquidity is closing. Implementing cost segregation for rental property isn't merely a tax-saving exercise; it's a fundamental capital reallocation strategy that fuels your next acquisition. By moving assets into 5, 7, or 15-year recovery periods through a rigorous engineering-based study, you transform passive depreciation into a proactive engine for growth.
Success in this field hinges on defensibility. As a licensed engineering firm that conducts over 10,000 studies annually, Engineered Tax Services provides the institutional knowledge and audit defense support required for high-stakes portfolios. Don't leave your capital trapped in your property's structure. You can schedule a complimentary cost segregation feasibility analysis with Engineered Tax Services to identify the hidden potential within your residential or commercial rentals. Take control of your cash flow today and build a more resilient, optimized financial future.
Frequently Asked Questions
Can I do a cost segregation study on a single-family rental property?
Yes, single-family rentals are excellent candidates for this strategy. While once considered a tool for large commercial assets, the rise of short-term rentals and high-value residential portfolios has made this a standard practice. An engineering-based study identifies 5-year assets like cabinetry and 15-year land improvements like fencing. This is particularly effective for properties with a high depreciable basis where the front-loaded tax savings can be immediately reinvested into new acquisitions.
How much does a cost segregation study for a rental property typically cost?
The investment required for a study varies based on the property's complexity and the level of technical documentation provided. Professional fees for engineering-based studies, which include physical site visits and rigorous IRS-defensible reports, are generally higher than automated “desktop” estimates. However, these fees are typically a small fraction of the total tax savings generated. It's best to look for a firm that provides a feasibility analysis to confirm the projected ROI before you proceed.
Is cost segregation worth it if I plan to sell the property in 3 years?
It depends on your broader wealth strategy and whether you intend to use a 1031 exchange. While selling early can trigger depreciation recapture, the time value of money often makes accelerated deductions beneficial even over a short holding period. Having extra liquidity today allows you to fund other projects or reduce high-interest debt. If you exchange the equity into a new property, you can continue deferring those taxes while maintaining a high cash flow.
What is depreciation recapture and how does it affect cost segregation?
Depreciation recapture is the process where the IRS taxes the gain on a property sale to the extent of previously claimed depreciation. Reclassified personal property assets are typically recaptured at ordinary income rates, while structural components are capped at 25%. Strategic investors manage this through 1031 exchanges or by timing the sale to align with other capital losses. It is a critical factor that your strategic partner will help you navigate during the planning phase.
Can I perform a cost segregation study on a property I bought several years ago?
Yes, you can perform a “look-back” study on properties acquired in prior years. This allows you to catch up on all the depreciation you missed since the date of purchase in a single tax year. It's a powerful mechanism for generating an immediate influx of cash flow without the need to amend previous tax returns. This strategy is ideal for investors who have owned assets for years but haven't yet optimized their depreciation schedules.
Do I need to amend my previous tax returns to claim accelerated depreciation?
No, you generally don't need to amend prior returns. Instead, you file IRS Form 3115, which is an Application for Change in Accounting Method. This form allows you to claim a “catch-up” deduction for the total amount of missed depreciation in the current tax year. It simplifies the process of implementing cost segregation for rental property on existing assets, providing immediate tax relief and significantly improving your near-term liquidity and portfolio stability.
What happens if my rental property is considered a passive activity?
Passive activity loss rules may limit your ability to use depreciation deductions to offset active income like W-2 wages. If your losses exceed your passive income, they are typically suspended and carried forward to future years. However, if you qualify as a Real Estate Professional or meet specific material participation requirements for short-term rentals, you can often use these deductions more aggressively. This allows you to shield a larger portion of your total income from taxation.
How does bonus depreciation in 2026 affect my cost segregation results?
In 2026, the bonus depreciation rate is 20% for qualifying assets placed in service during the year. This allows you to immediately expense 20% of the value of reclassified 5, 7, and 15-year assets in the first year. The remaining 80% is then depreciated over their respective shorter recovery periods. While this is lower than previous years, it still provides a massive cash flow advantage over standard straight-line methods that stretch deductions over decades.