What if the most important step after receiving a cost segregation report isn’t finding accelerated depreciation, but making sure the findings are recorded correctly? Knowing how to use a cost segregation report means understanding its classifications and supporting analysis, then coordinating them with your tax-return preparer. The report informs tax treatment; it doesn’t replace the decisions and documentation needed to apply the findings to your circumstances.
It’s reasonable to be unsure which findings belong on a return, especially when the report needs to align with existing depreciation schedules and accounting records. Treating every line as a ready-to-enter tax item can create confusion. A careful review helps you spot questions, clarify assumptions, and ground implementation in the report’s technical support.
This guide explains how to review a report, discuss its findings and limitations with a qualified tax professional, and organize records for current and future reporting. You’ll also learn how engineering documentation can support collaboration between property owners, engineers, and return preparers, so the report becomes a practical part of your tax process.
Key Takeaways
- A cost segregation report documents asset classifications for tax analysis; its findings don’t guarantee a deduction or specific tax result.
- To understand how to use a cost segregation report, compare its assumptions with purchase, construction, renovation, and placed-in-service records.
- Reconcile the report with existing depreciation schedules and accounting records before discussing possible reporting treatment with your tax-return preparer.
- Keep the final report with source documents, tax schedules, preparer communications, and filed returns to support future reporting.
- If information is unclear or circumstances have changed, ask about the report’s scope, assumptions, supporting schedules, and deliverables.
Understand What a Cost Segregation Report Tells You
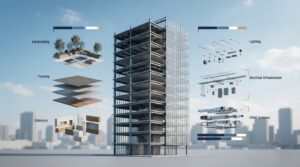
A cost segregation report is technical documentation that analyzes a property’s components and supports their classification for depreciation purposes. It helps show how the property’s depreciable basis may be allocated among assets with different classifications, rather than treated as one undivided amount. This Cost Segregation Study overview offers background on the study process and asset classifications.
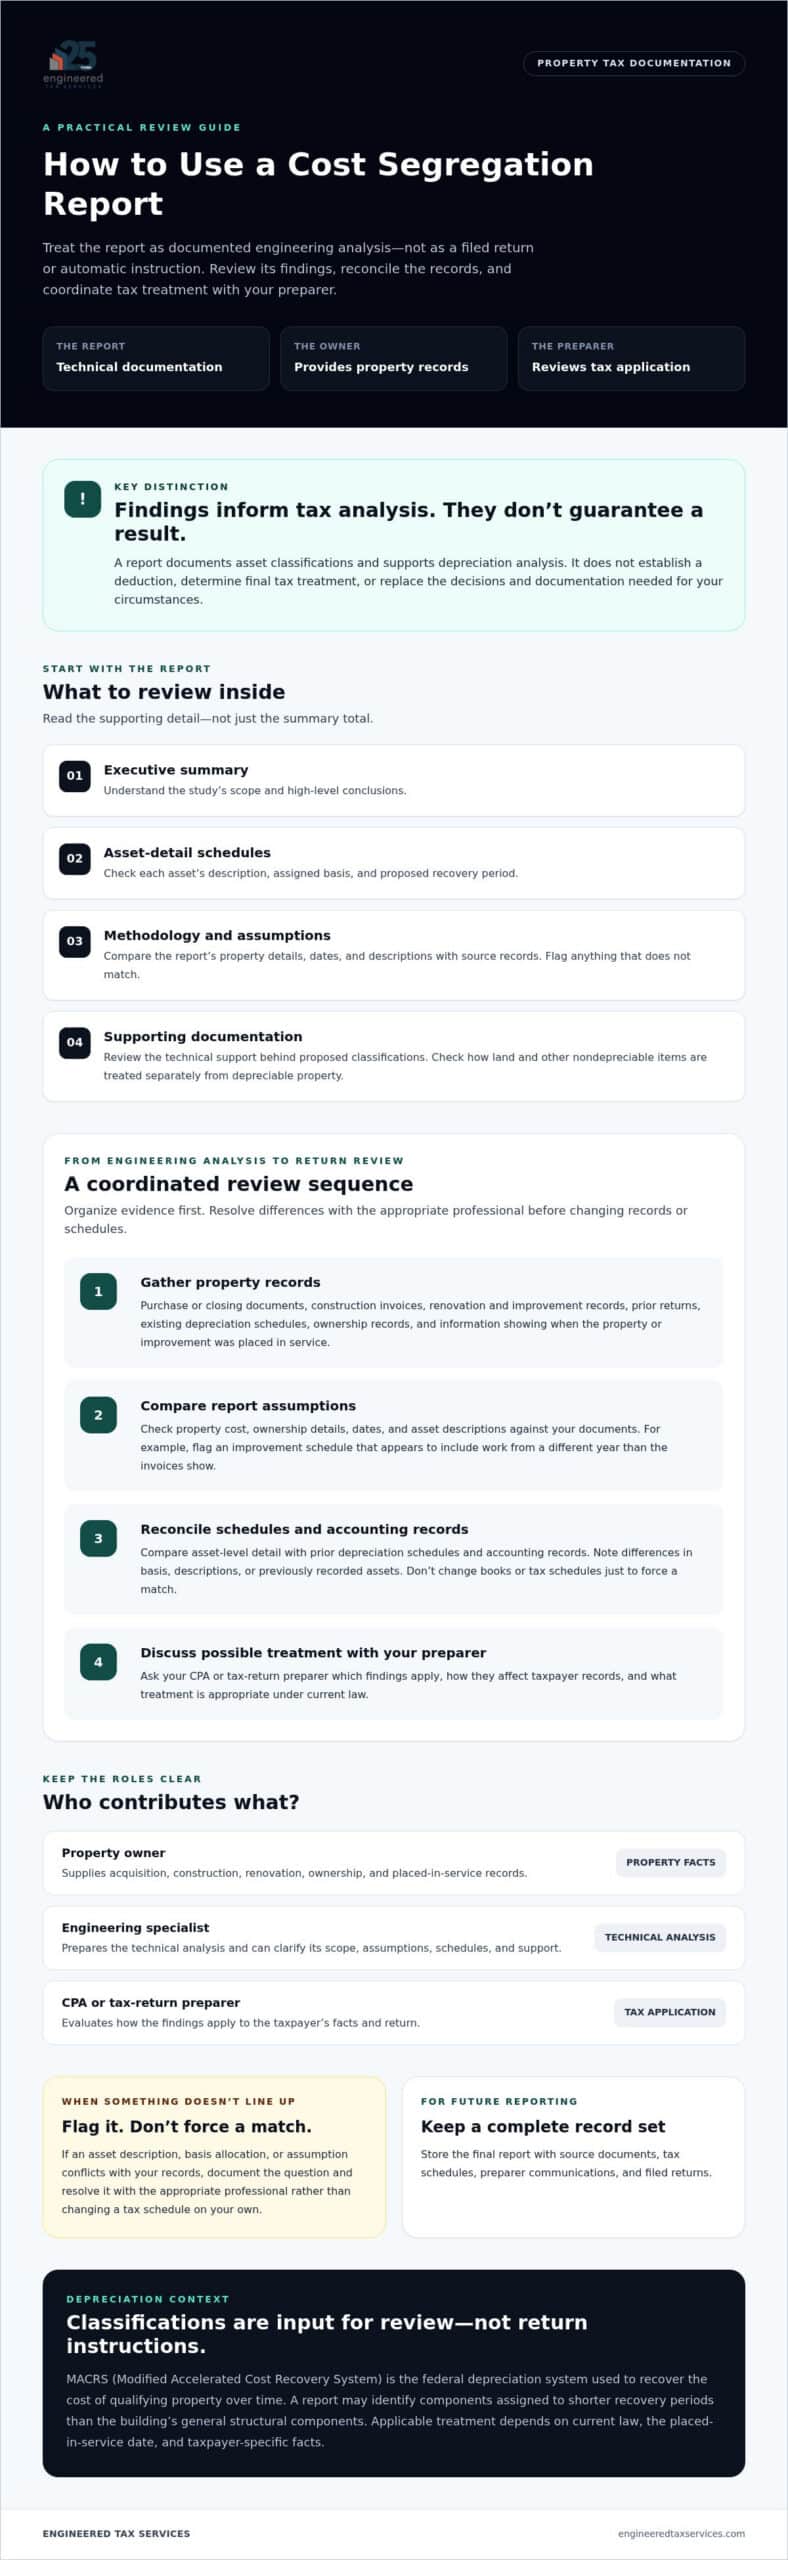
A cost segregation report is an engineering analysis, not a filed tax return. Its findings inform tax analysis, but they don’t establish a deduction, determine final tax treatment, or guarantee a particular result. The property owner can provide acquisition and improvement records; an engineering specialist prepares the technical analysis; and the CPA or tax-return preparer reviews how the findings apply to the taxpayer’s facts and return.
Which findings and schedules should you locate first?
Start with the executive summary to understand the study’s scope and high-level conclusions. Then review the asset-detail schedules, methodology, assumptions, and supporting documentation. For each asset, look for its description, assigned basis, and proposed recovery period. These details help you compare the report with property records instead of relying on a summary total alone.
Check how the report treats land and other nondepreciable items, which require distinct treatment from depreciable property. The appropriate allocation depends on the underlying facts. If an asset description, basis allocation, or assumption doesn’t match your records, flag it for review rather than changing a tax schedule on your own.
What do asset classifications mean for depreciation?
MACRS, the Modified Accelerated Cost Recovery System, is the federal depreciation system used to recover the cost of qualifying property over time. A report may identify components assigned to shorter recovery periods than the building’s general structural components. Those classifications can inform depreciation analysis, but they are findings for a tax professional to evaluate, not automatic instructions for a return.
Applicable depreciation treatment depends on current law, the property’s placed-in-service date, and taxpayer-specific facts. The report’s methodology and assumptions help the preparer assess whether its proposed classifications fit the property and intended tax treatment. That review is central to how to use a cost segregation report responsibly: treat the engineering analysis as documented input, then coordinate its application with your tax professional.
Use a Cost Segregation Report in Five Coordinated Steps
A report is most useful when its technical findings are checked against property records and reviewed for tax-return application. This workflow clarifies the handoff: you organize the evidence, the engineering provider clarifies the analysis when needed, and your CPA or tax-return preparer determines what treatment fits your circumstances. For broader study context, see this commercial property cost segregation guide.
- Gather the records. Assemble purchase or closing documents, construction invoices, renovation and improvement records, prior returns, and existing depreciation schedules. Include records that establish ownership and when the property or improvement was placed in service.
- Review the report’s assumptions. Compare the property cost, ownership details, dates, and asset descriptions in the report with your source documents. For example, if an improvement schedule appears to include work completed in a different year than your invoices show, flag the discrepancy for review.
- Reconcile the schedules. Compare the report’s asset-level detail with your accounting records and prior depreciation schedules. Note differences in basis, descriptions, or previously recorded assets. Don’t change the books or tax schedules just to force a match; document questions and resolve them with the appropriate professional.
- Consult your return preparer. Ask your CPA or tax-return preparer to assess which findings apply, how they affect the taxpayer’s records, and what treatment is appropriate under current law. The Journal of Accountancy’s overview of how cost segregation works provides process context, but your preparer must evaluate your specific facts.
- Document the decisions. Record which findings were used, which were not, and why. Retain the report, source records, reconciled schedules, and relevant communications so the rationale is easier to follow in future reporting.
Reconcile the report with property and accounting records
Look for mismatches without assuming that every difference signals an error. A purchase allocation may not align neatly with later renovation costs, and an asset description in the report may use technical language that differs from your ledger. Ask the engineering provider to clarify its methodology, assumptions, or asset-level descriptions as needed. This cost segregation application overview can also help frame questions about categorization and depreciation analysis.
Coordinate tax treatment with your return preparer
Ask the preparer to evaluate eligibility and applicable depreciation rules based on current law and your facts. If the property was placed in service in a prior year, discuss whether the situation raises a separate accounting-method question. That analysis may require additional review and should not be assumed from the report alone. For information about engineering-based analysis, see ETS cost segregation services.
Translate Report Findings Into Reviewed Tax-Return Treatment
A cost segregation report gives your tax-return preparer technical findings to evaluate, not entries to transfer automatically to a return. Before deciding whether and how a finding should be reported, the preparer must consider property records, existing depreciation history, applicable tax law, and your individual circumstances. This review turns the report into a coordinated tax decision.
Use a comparison table to organize the handoff. Answers vary by property and tax year, so treat the last column as a decision to make with your preparer.
| Report finding | Supporting record | Preparer question | Implementation decision |
|---|---|---|---|
| An asset is assigned a shorter recovery period | Report detail, invoices, construction or improvement records | Does the classification fit the asset and applicable rules? | Confirm whether and how to reflect it in depreciation records and the return |
| A basis amount is assigned to a property component | Closing statement, cost records, prior depreciation schedule | Does the amount reconcile with the property’s documented basis and prior reporting? | Resolve differences and document the basis used |
| The report covers property placed in service in an earlier year | Placed-in-service records, prior returns, depreciation schedules | Does the reporting history require separate analysis? | Determine the appropriate procedure based on current rules and taxpayer facts |
How should prior-year property be handled?
For property already depreciated on filed returns, a report may prompt a method-change analysis. That doesn’t automatically mean an amended return is appropriate. Depending on the taxpayer’s history and current requirements, a qualified tax professional may consider whether Form 3115, Application for Change in Accounting Method, and a Section 481(a) adjustment are relevant. Verify current IRS guidance and the facts before deciding eligibility, timing, or filing approach.
How do current depreciation rules affect the result?
For current-year property, the preparer should verify the applicable MACRS and bonus depreciation rules for the relevant tax year, including the property’s placed-in-service date and other taxpayer-specific facts. Engineering classifications describe the assets analyzed; tax law determines whether those classifications affect a deduction and when it may be claimed. Neither substitutes for the other.
For broader context on depreciation concepts, review this commercial real estate depreciation guide. Applying how to use a cost segregation report responsibly means pairing its documented findings with a separate, fact-specific review of tax treatment.
Protect the Value of Your Cost Segregation Report With Strong Records
A completed report is not a guaranteed deduction, and it doesn’t prevent an examination. Its value depends in part on whether the findings can be traced to property records and whether the tax treatment fits the facts and applicable rules. Preserve the report alongside the records your preparer used to evaluate and implement its findings.
Defensible tax treatment depends on the property’s facts, supporting documentation, and the tax rules that apply to the reporting year. Clear records connect an engineering classification to its source evidence and explain how the finding was handled on the return. They can also make future reviews more efficient when accounting records, ownership, or the property itself change.
What documentation should property owners retain?
Keep a complete file for the property, not only the report’s summary pages. Retain:
- The final cost segregation report, including asset-level schedules and supporting analysis.
- Closing documents, invoices, construction records, and details of renovations or improvements relevant to the study.
- Tax returns and depreciation schedules showing how reviewed findings were treated.
- Material questions, explanations, and decisions shared with the engineering provider and tax-return preparer.
Use consistent asset descriptions across the report, accounting records, and tax schedules where practical. If the preparer decides not to use a finding or adjusts how it is reflected, preserve the rationale and related communications. This reconciliation trail helps explain why records may differ and supports continuity in later reporting.
What should you revisit after a sale or property change?
Tell your tax advisor about a property sale or disposition, renovation, ownership change, or corrected record. These events may affect how individual assets are treated, but the consequences depend on the property’s history, the assets involved, and current tax rules. Don’t assume an old report automatically resolves a new reporting question. Give your advisor relevant updated documents and ask whether the existing schedules or analysis need review.
Organized engineering documentation can help property owners, engineering specialists, and tax-return preparers work from a shared record. For a technically grounded review of property classifications and supporting analysis, see engineering-based cost segregation analysis.
Choose the Right Next Step for Your Cost Segregation Report
The right next step depends on what remains unresolved. If the report’s assumptions or asset descriptions don’t match your purchase, construction, or improvement records, ask the engineering provider to explain the discrepancy. If the report is clear but you’re unsure how a finding affects a return, bring it to your CPA or tax-return preparer. A new engineering analysis may be worth discussing when property work, ownership history, or available documentation differs materially from the existing study’s scope. Not every property needs further analysis.
When is clarification enough, and when might further analysis help?
Request clarification when you need a better explanation of an existing report, such as how an asset was described, which assumptions informed its classification, or where supporting detail appears in the schedules. Consider professional review when complex ownership history, prior depreciation, or substantial property changes raise questions that clarification alone cannot answer. The appropriate path depends on the records and facts, not on an assumption that every report or property requires additional work.
What should you prepare before contacting a provider?
Gather available acquisition and closing documents, construction and renovation records, placed-in-service information, prior depreciation schedules, and the report itself, if one exists. Then prepare focused questions about the work you need reviewed:
- What property and improvements are within the analysis scope?
- Which assumptions, records, and engineering methods support the asset classifications?
- What asset-level schedules and supporting documentation will be provided?
- How can the report’s details be shared with my tax-return preparer?
These questions help establish whether you need an explanation, a fresh engineering assessment, or simply tax-return coordination. They also clarify what the analysis can and cannot resolve. A cost segregation report informs tax analysis; the tax-return preparer evaluates reporting treatment based on applicable rules and your circumstances.
Engineered Tax Services is an independent, licensed engineering firm specializing in cost segregation and other engineering-based tax studies. Its role is to provide engineering analysis and technical documentation, not standard income tax filing or tax-court representation. If you’re considering how to use a cost segregation report, share the property’s history and your specific questions with the relevant engineering and tax professionals.
Put Your Cost Segregation Findings to Work With Confidence
Using a cost segregation report responsibly means more than identifying asset classifications. Compare its assumptions with property records, reconcile findings with existing depreciation schedules, and work with your tax-return preparer to determine appropriate reporting treatment. Keep the report and supporting records together so future decisions can be traced to the underlying facts.
Understanding how to use a cost segregation report also means recognizing the roles involved. Engineering documentation supports the analysis; your tax professional evaluates how it applies to your return and circumstances. No report can guarantee a deduction or a particular tax outcome.
Engineered Tax Services is an independent, licensed engineering firm specializing in cost segregation. The firm reports conducting over 10,000 tax studies annually. Its engineering-based work provides technical documentation for coordination with your tax professional.
Discuss your cost segregation needs with Engineered Tax Services to identify a possible next step for your property. Organized records and appropriate professional review can help you move forward with greater clarity.
Frequently Asked Questions
How do you use a cost segregation report on a tax return?
Share the completed report and relevant property records with your CPA or tax-return preparer. To understand how to use a cost segregation report, treat it as technical support for review, not as automatic instructions for entering deductions. Your preparer should assess asset classifications, report assumptions, ownership details, placed-in-service dates, and current tax rules before deciding how applicable depreciation should be reflected on your return.
Does a cost segregation report get filed with the IRS?
A cost segregation report is generally supporting documentation for tax analysis, not a tax-return form by itself. Work with your tax-return preparer to determine what forms or records are needed for the specific reporting position and how supporting documents should be retained. Keep the report with relevant property records, such as purchase documents and improvement invoices, and confirm filing and record-retention requirements with a qualified tax professional under current guidance.
Can you use a cost segregation report for a property you bought in a prior year?
Possibly, but property placed in service in a prior year can raise accounting-method and timing questions that differ from a current-year acquisition. Ask a CPA or other qualified tax professional to review prior returns, depreciation schedules, property records, and applicable rules. Don’t assume an amended return or a particular method-change procedure is automatically appropriate. The right approach depends on the property’s history, your circumstances, and current guidance.
What documents should I give my CPA with a cost segregation report?
Provide the final report, purchase or closing records, construction and renovation invoices, placed-in-service information, prior tax returns, and existing depreciation schedules when available. Include records that clarify ownership, property use, and changes made after acquisition. These materials help your preparer compare the report’s assumptions with your records and evaluate applicable tax treatment. Your preparer can identify missing information or request clarification about specific assets and basis allocations.
Does a cost segregation report guarantee tax savings?
No. A report documents engineering-based asset classifications, but tax treatment depends on current law, property details, taxpayer circumstances, and professional review. It doesn’t guarantee eligibility, a specific deduction, improved cash flow, or a particular examination outcome. Before relying on projected results, ask your tax professional to assess whether the findings apply to your situation and explain how depreciation timing may affect your tax reporting.
What happens if the report and my depreciation schedule do not match?
Don’t change your return or accounting records without review. Identify the differences and gather relevant source documents, then ask the report provider and your tax preparer to reconcile assumptions, asset descriptions, basis, and dates. A mismatch could reflect a recordkeeping issue, an earlier reporting decision, or a tax-method question. The appropriate next step depends on the cause, so have a qualified professional review the records before making changes.