An 80% reduction in your potential tax credit value is the immediate penalty for failing to substantiate prevailing wage standards under the latest federal mandates. As the industry moves through this pivotal year, the transition from ENERGY STAR to the more rigorous DOE Zero Energy Ready Home (ZERH) Version 2 standards has left many developers questioning their path to compliance. We recognize the anxiety surrounding these technical benchmarks, especially with the early statutory sunset date of June 30, 2026, looming over current projects.
This guide provides the strategic roadmap you need to master the 45L tax credit eligibility requirements 2026 and secure the maximum $2,500 to $5,000 per unit credit. You'll learn how to satisfy the technical standards of the DOE Efficient New Homes Program and implement an engineering-led approach for audit-proof documentation. We will detail the critical acquisition deadlines, the specific labor standards required for the 5x multifamily multiplier, and how to bridge the gap between engineering precision and tax optimization to ensure your portfolio remains a vehicle for long-term growth.
Key Takeaways
- Master the 45L tax credit eligibility requirements 2026 to capture enhanced credits of up to $5,000 per dwelling unit for high-efficiency developments.
- Understand the mandatory transition to ENERGY STAR v3.2 and ZERH v2 benchmarks to ensure building envelopes and HVAC systems meet federal performance pillars.
- Learn how to satisfy Davis-Bacon prevailing wage requirements to unlock the 5x multifamily credit multiplier and avoid severe valuation penalties.
- Discover strategic ways to stack 45L credits with Section 179D deductions and cost segregation to maximize immediate cash flow through the “Triple Play” approach.
- Implement a rigorous, engineering-led documentation process to secure IRS-ready certifications and mitigate audit risks for multi-state portfolios.
The 2026 45L Tax Credit Landscape: A Strategic Overview
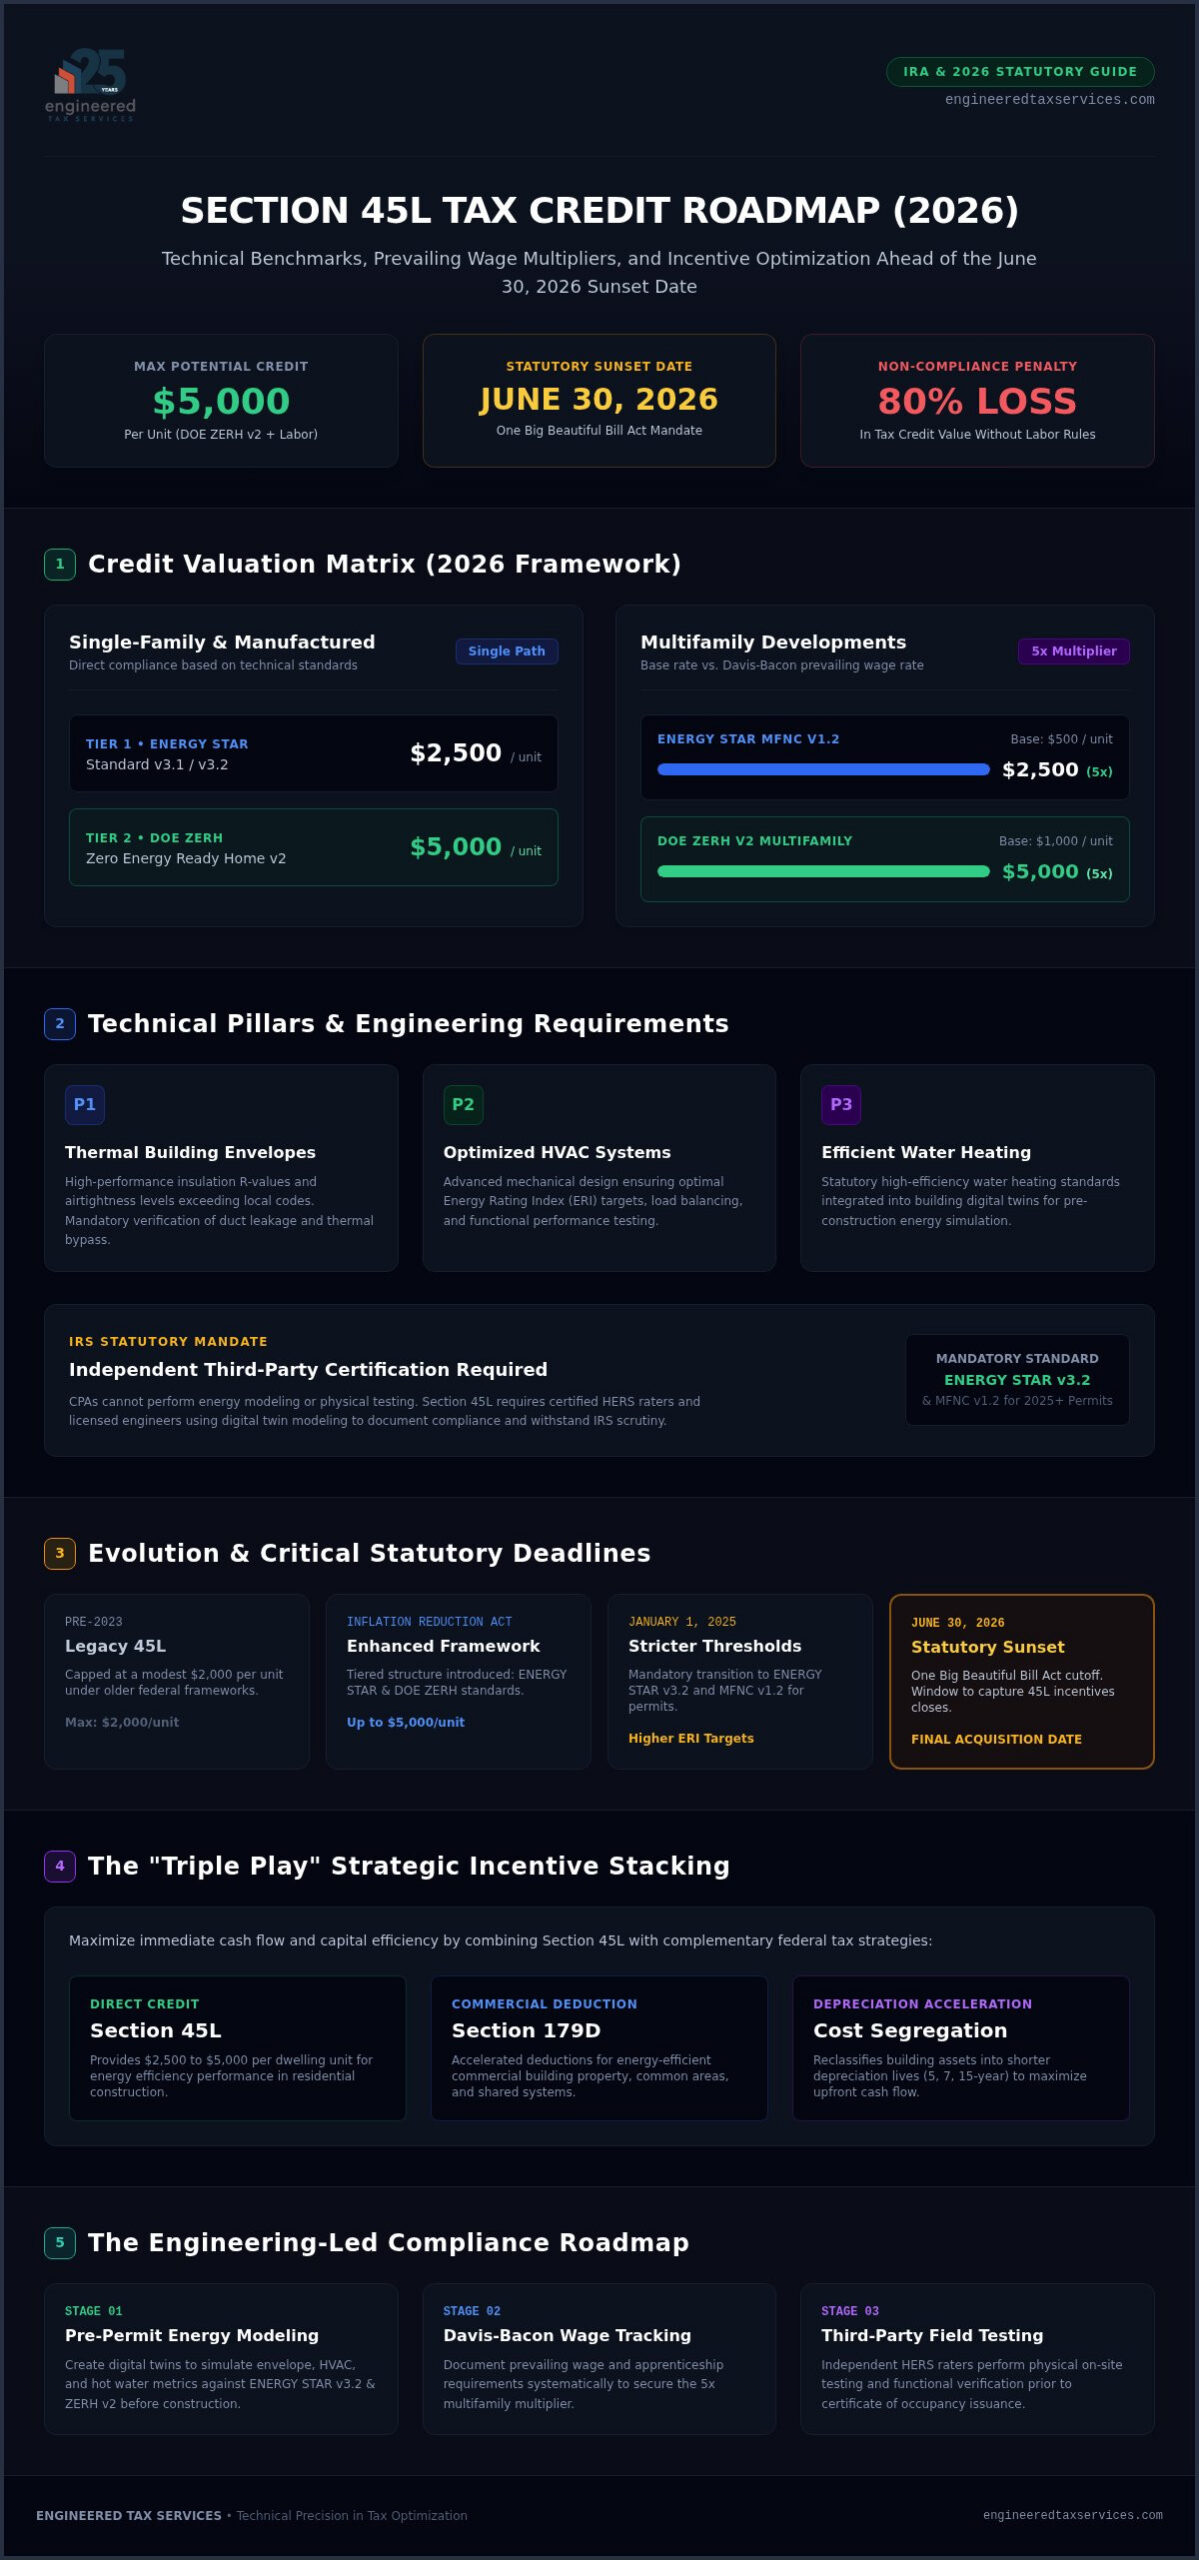
The Section 45L New Energy Efficient Home Credit has evolved from a niche incentive into a cornerstone of modern real estate development strategy. For those tracking the 45L tax credit eligibility requirements 2026, the landscape is defined by higher performance bars and significantly larger financial stakes. While the pre-2023 credit was capped at a modest $2,000 per unit, the current framework under the Inflation Reduction Act offers up to $5,000. This transition reflects a federal push toward deep decarbonization, making 2026 a critical turning point for developers. With the statutory sunset date of June 30, 2026, established under the One Big Beautiful Bill Act, the window to capture these incentives on newly acquired units is closing fast.
Strategic success in 2026 requires a clear understanding of the bifurcated qualification paths. Single-family and multifamily projects now face distinct technical hurdles and labor requirements. It's no longer enough to simply build a quality home. You must prove that every dwelling unit meets specific federal efficiency benchmarks through rigorous, third-party validation. This shift transforms 45L from a simple tax filing into a comprehensive engineering exercise where technical precision dictates the ultimate return on investment.
Maximum Credit Amounts for 2026 Projects
Qualification paths diverge based on the level of efficiency achieved and the labor standards employed. For single-family and manufactured homes, the $2,500 tier requires adherence to the ENERGY STAR program standards, specifically version 3.1 or 3.2 depending on the permit date. Elevating a project to the DOE Zero Energy Ready Home (ZERH) certification doubles that benefit to $5,000 per unit. Multifamily developers face a more complex calculation. The base credits are $500 or $1,000, but these jump to the full $2,500 or $5,000 amounts when prevailing wage requirements are satisfied. These credits apply equally to homes built for sale and units intended for lease, provided the taxpayer holds the basis during construction.
Why Engineering Precision is Non-Negotiable
The IRS mandates that a project must be certified by an independent eligible certifier who is not related to the taxpayer. This requirement places 45L firmly in the territory of licensed engineers and certified HERS raters rather than standard tax preparers. A CPA can record the credit, but they cannot perform the energy modeling or physical testing necessary to validate it. Relying on engineering based tax studies ensures that every technical data point, from duct leakage to thermal envelope performance, is documented to withstand federal scrutiny. In an environment of increased IRS enforcement, this technical precision is the only way to safeguard your 45L tax credit eligibility requirements 2026 against potential audits.
Technical Eligibility Requirements: ENERGY STAR vs. ZERH v2
The technical landscape for 45L has shifted significantly as we approach the mid-2026 cutoff. For projects permitted on or after January 1, 2025, the 45L tax credit eligibility requirements 2026 mandate a move to ENERGY STAR v3.2 for single-family homes and Multifamily New Construction (MFNC) v1.2 for larger developments. These benchmarks aren't mere suggestions. They're statutory requirements that demand a holistic engineering approach to building design and energy modeling.
Three core technical pillars drive these standards: high-performance building envelopes, optimized HVAC systems, and efficient water heating. Achieving the necessary Energy Rating Index (ERI) targets requires more than just better insulation. It demands integrated design where every component works in concert. To validate these designs, engineers utilize advanced simulation software to create a digital twin of the property. This modeling ensures that the proposed construction will meet the stringent federal thresholds before the first shovel hits the ground.
ENERGY STAR v3.2 Thresholds for 2026
The $2,500 credit tier hinges on meeting the latest ENERGY STAR specifications. For 2026 projects, this often means achieving airtightness levels and insulation R-values that far exceed local building codes. A critical part of the process involves mandatory on-site inspections and functional testing conducted by a certified third-party Rater. These professionals must verify everything from duct leakage to thermal bypass before a certificate of occupancy is issued. Following the IRS Section 45L builder tax credit guidance is essential to ensure your documentation matches the technical reality of the build.
Achieving Zero Energy Ready Home (ZERH) v2
Moving to the $5,000 credit tier requires the DOE Zero Energy Ready Home (ZERH) v2 certification. This isn't just a slight improvement over ENERGY STAR; it's a fundamental leap in performance. ZERH v2 introduces mandatory requirements for renewable energy readiness, such as pre-wired solar pathways and designated space for battery storage. It also incorporates the EPA Indoor airPLUS v2 standards to ensure superior indoor air quality. For multifamily developers, meeting the 45L tax credit eligibility requirements 2026 through ZERH v2 compliance represents a “Zero Energy Ready” threshold that future-proofs the asset while maximizing immediate tax benefits. To determine if your current designs meet these elevated standards, a proactive Engineered Incentives Report can identify necessary adjustments early in the development cycle.
Labor Standards: Prevailing Wage and Apprenticeship Rules
While technical design sets the foundation, labor standards dictate the ultimate financial scale for multifamily projects. Under the 45L tax credit eligibility requirements 2026, developers must decide early whether to pursue the base credit or the enhanced multiplier. For multifamily structures, the stakes are binary. Failing to meet prevailing wage standards slashes your potential credit by 80%. This isn't just a minor deduction; it's a structural shift in a project's ROI that requires proactive payroll management from the very first day of construction.
A common point of confusion in the industry involves the distinction between different federal incentives. Many developers conflate 45L with the 179D deduction or the Section 48 investment tax credit. While those programs require both prevailing wage and apprenticeship participation, Section 45L(g) specifically mandates only prevailing wage compliance. You don't need to track apprentice labor hours to qualify for the 45L multiplier. This distinction is a vital piece of strategic knowledge that prevents unnecessary administrative burdens while still securing the highest possible credit tier.
The 5x Multiplier Framework
The financial disparity between compliance and non-compliance is stark. In a typical 100-unit multifamily development, meeting DOE Zero Energy Ready Home requirements without satisfying labor standards results in a $100,000 credit, or $1,000 per unit. However, by ensuring laborers and mechanics are paid at or above the Davis-Bacon Act prevailing wage rates, that same project yields a $500,000 credit. This 5x multiplier applies to all units acquired before the June 30, 2026, deadline. These requirements apply based on the date construction or renovation begins, making retrospective compliance nearly impossible without rigorous, real-time documentation.
Compliance and ‘Good Faith Effort' Exceptions
Maintaining audit-proof records is the only way to safeguard your claim against IRS scrutiny. The IRS requires certified payroll reports that match Department of Labor determinations found on SAM.gov for the specific geographic area and construction type. If you discover a discrepancy during the build, Treasury regulations allow for “curing” non-compliance through back-pay and interest penalties. These corrections must be resolved before the tax return is filed. Utilizing a comprehensive engineered tax incentives report provides the necessary substantiation to document that your project met the 45L tax credit eligibility requirements 2026. This proactive approach ensures that your $2,500 or $5,000 per unit credit remains secure during a potential audit.
Stacking Incentives: 45L, 179D, and Cost Segregation
Maximizing your return in 2026 requires moving beyond isolated tax filings toward a unified “Triple Play” strategy. This approach integrates the Section 45L credit, the Section 179D deduction, and accelerated depreciation through cost segregation. By viewing these incentives as a single wealth optimization engine, developers can unlock capital that would otherwise remain trapped in their tax basis. The 45L tax credit eligibility requirements 2026 are just one piece of this puzzle; the real value lies in how these technical analyses overlap to create a comprehensive Engineered Incentives Report.
Coordinating these studies under a single engineering firm is vital for consistency and audit protection. When one team of Professional Engineers handles the energy modeling for 45L and 179D while simultaneously performing the asset breakdown for cost segregation, the risk of conflicting data is eliminated. This synergy ensures that every square foot of the property is accounted for and optimized according to the latest federal benchmarks.
45L vs. 179D: Navigating the Overlap
For multifamily and mixed-use developments, the distinction between residential and commercial square footage is the key to incentive stacking. While 45L applies to individual dwelling units, the 179D energy efficient commercial building deduction provides a powerful offset for common areas, hallways, and ground-floor retail spaces. In 2026, this deduction reaches up to $5.81 per square foot for projects that satisfy prevailing wage and apprenticeship standards. High-rise developments, which were once restricted, now represent some of the best opportunities for this dual-track approach. Identifying the exact boundaries of residential use ensures you don't double-dip on the same components while still capturing the full value of both incentives. This strategy is particularly effective for developers with multi-state portfolios looking to standardize their technical compliance.
Cost Segregation Integration
Integrating cost segregation for commercial property adds a third layer of savings by identifying 5-, 7-, and 15-year assets within the building structure. Under the One Big Beautiful Bill Act (OBBBA), 100% bonus depreciation is now a permanent fixture for qualifying property placed in service after January 20, 2025. This allows developers to front-load massive deductions in the first year, significantly improving cash flow for future acquisitions. Because 45L credits are triggered by the acquisition date, which must occur by June 30, 2026, timing your engineering studies is critical. A proactive analysis identifies 45L-eligible assets early, allowing for design adjustments that ensure compliance before the statutory window closes. To secure your portfolio's financial health, request a multi-incentive feasibility study to see how these three strategies work in tandem for your specific assets.
The ETS Method: Engineering Your 45L Success
Engineered Tax Services (ETS) stands as a premier authority at the intersection of tax law and structural engineering. For developers, the complexity of 45L tax credit eligibility requirements 2026 demands a partner that understands more than just tax codes. We bridge this gap by providing the technical precision needed to transform energy-efficient designs into significant capital recovery. As the preferred partner for a 45L tax credit for multifamily developers, we utilize a proprietary method that integrates licensed Professional Engineers (PEs) and certified HERS raters into every study.
Our national network allows us to manage multi-state portfolios with consistent, rigorous standards. We don't just fill out forms. We perform deep technical verification. This includes blueprint analysis, duct testing, and thermal envelope inspections. This level of detail is exactly what the IRS requires from an “Eligible Certifier.” By conducting over 10,000 tax studies annually, we've developed an audit-defense protocol that stands up to the most intense federal scrutiny. Our goal is to provide peace of mind through technical precision, ensuring your incentives are both maximized and secure.
The Value of an Engineering-Based Study
Generic tax advice often ignores the physical reality of the building. The ETS Method relies on software-driven energy modeling that satisfies the most recent Department of Energy requirements. We conduct detailed site visits to verify technical specifications in the field. Every study concludes with a final certification signed by a licensed PE. This signature isn't just a formality. It represents a professional commitment to accuracy and compliance that safeguards your wealth. Our reports move beyond standard accounting to provide the granular technical data the IRS expects during a review.
Next Steps for 2026 Planning
The June 30, 2026, sunset date makes early planning mandatory. Start with a design consultation to ensure your current blueprints meet ZERH v2 thresholds. You should also review your contractor agreements. Ensure they include specific language regarding prevailing wage documentation to secure the 5x multiplier. We recommend requesting a preliminary assessment of your 2026 pipeline today. Proactive coordination ensures you don't miss the statutory window for unit acquisition. Our team provides the strategic partnership necessary to navigate these final months of eligibility with confidence and integrity.
Securing Your 2026 Real Estate Wealth
The window to capture these enhanced federal incentives is narrowing as the June 30, 2026, statutory deadline approaches. Success in this final phase requires a dual mastery of evolving technical standards and rigorous labor compliance. By transitioning to ZERH v2 benchmarks and ensuring prevailing wage substantiation, you can secure the full $5,000 per unit credit. Integrating these efforts with 179D deductions and cost segregation creates a powerful multiplier for your portfolio's cash flow. Mastering the 45L tax credit eligibility requirements 2026 isn't just a matter of filing paperwork; it's a strategic engineering challenge that dictates your long-term ROI.
As a Licensed Engineering Firm conducting over 10,000 studies annually, Engineered Tax Services provides the technical precision required for IRS-ready documentation. We bridge the gap between complex energy modeling and wealth optimization. Don't leave your credits to chance or standard accounting methods. Maximize your 2026 tax incentives with a specialized engineering study from ETS and ensure your developments remain a vehicle for growth. We're ready to help you navigate these final months with complete confidence.
Frequently Asked Questions
What is the difference between ENERGY STAR and ZERH for the 45L credit in 2026?
The primary difference lies in the credit value and performance thresholds. Meeting the ENERGY STAR v3.2 standards qualifies single-family homes for a $2,500 credit. Stepping up to the DOE Zero Energy Ready Home (ZERH) v2 standards increases that benefit to $5,000. For multifamily projects, these certifications determine the base credit amount before the prevailing wage multiplier is applied. ZERH v2 introduces more stringent requirements for renewable energy readiness and indoor air quality than the base ENERGY STAR track.
Can multifamily developers claim the 45L credit if they use prevailing wage?
Multifamily developers must pay prevailing wages to laborers and mechanics to unlock the 5x credit multiplier. Without meeting these labor standards, the credit is limited to $500 for ENERGY STAR units or $1,000 for ZERH units. By paying Davis-Bacon Act rates, those amounts jump to $2,500 and $5,000 respectively. This multiplier is the most significant factor in maximizing the ROI on large-scale residential developments acquired before the June 30, 2026, deadline.
Who is considered an ‘Eligible Certifier' for the 45L tax credit?
An eligible certifier must be an independent third party who isn't related to the taxpayer claiming the credit. The IRS requires these professionals to possess the technical expertise to perform energy modeling and physical testing. Typically, this role is filled by licensed Professional Engineers (PEs) or certified HERS raters. These experts provide the official certification that the property meets all 45L tax credit eligibility requirements 2026, ensuring the documentation is audit-proof and technically sound.
Is the 45L tax credit available for renovations or only new construction?
The credit is available for both new construction and substantial renovations. While the statute refers to “new energy efficient homes,” it includes properties that have undergone significant reconstruction or rehabilitation. To qualify, the unit must meet the same ENERGY STAR or ZERH efficiency benchmarks as a new build. The key requirement is that the taxpayer must own and have a basis in the unit during construction and be the first to sell or lease it.
How do the 2026 apprenticeship requirements affect the 45L credit amount?
Apprenticeship requirements don't apply to the Section 45L credit. This is a common misconception among developers who often conflate 45L rules with Section 179D or Section 48 guidelines. While those other incentives require both prevailing wage and apprenticeship participation, 45L exclusively mandates prevailing wage compliance for the multifamily multiplier. You don't need to track apprentice labor hours or ratios to secure the full $2,500 or $5,000 credit per dwelling unit.
Can I stack the 45L credit with the 179D deduction on the same building?
You can stack these incentives by bifurcating the property's square footage. Developers claim the 45L credit for individual dwelling units and the 179D deduction for commercial spaces or common areas like hallways and lobbies. In mixed-use or high-rise multifamily buildings, this dual-track strategy maximizes the total incentive value. It's essential to use an engineering-based study to ensure that no single component is double-counted, maintaining clear boundaries between the residential and commercial footprints.
What documentation does the IRS require to substantiate a 45L claim in 2026?
Substantiating a claim requires a comprehensive technical file. This includes a certification from an eligible certifier, detailed energy modeling reports, and on-site testing results like blower door and duct leakage data. If you're claiming the multifamily multiplier, you must also maintain certified payroll records that prove compliance with Davis-Bacon prevailing wage rates. These documents must be finalized before you file Form 8908 with your tax return to satisfy all 45L tax credit eligibility requirements 2026.
Does the 45L credit apply to low-income housing tax credit (LIHTC) projects?
The 45L credit is highly compatible with Low-Income Housing Tax Credit (LIHTC) projects. Unlike many other federal incentives, claiming the 45L credit doesn't reduce the building's eligible basis for LIHTC purposes. This allows affordable housing developers to capture both the energy credit and the full value of their LIHTC allocation. It's a powerful tool for improving the financial feasibility of subsidized housing projects while ensuring they meet high-performance energy standards for their residents.