In the 2026 tax landscape, the traditional fear of a bonus depreciation phase-down has been replaced by a permanent 100% incentive that makes the synergy between cost segregation and 1031 exchange the most powerful wealth preservation tool in a real estate investor's arsenal. Following the passage of the One Big Beautiful Bill Act, the ability to front-load deductions has never been more vital for those looking to scale their portfolios without losing ground to the IRS. You've likely spent years building equity, only to worry that depreciation recapture taxes at a fixed 25% rate might claw back your gains when you finally decide to trade up. It's a valid concern that often keeps even the most sophisticated owners from moving forward with a replacement property.
We understand that you want to keep your capital working for you rather than handing it over to the government. This article will show you how to strategically combine cost segregation with 1031 exchanges to preserve your capital, neutralize recapture risks, and maximize cash flow through 100% bonus depreciation. We will break down the complex relationship between carryover and excess basis, explain the latest legislative shifts, and demonstrate how a certified engineering report ensures your strategy stands up to the highest levels of professional scrutiny.
Key Takeaways
- Transform passive tax deferral into a proactive engine for growth by leveraging the strategic synergy of the “twin pillars” of real estate wealth preservation.
- Master the technical distinction between carryover and excess basis to identify exactly which portions of your replacement property are eligible for accelerated depreciation.
- Protect your hard-earned equity from the “recapture trap” by using a cost segregation and 1031 exchange to defer taxes on both Section 1245 and 1250 assets.
- Optimize your immediate cash flow in the 2026 tax environment by utilizing accelerated depreciation to offset the impact of the 20% bonus depreciation rate.
- Ensure rigorous IRS compliance through an engineering-based methodology that provides the technical precision and site-specific data required to withstand scrutiny.
The Strategic Synergy of Cost Segregation and 1031 Exchanges
Real estate wealth isn't built just through appreciation; it's built through the relentless preservation of capital. For decades, sophisticated investors have viewed the 1031 exchange and cost segregation as separate tax tools. One defers capital gains; the other accelerates depreciation. In the current 2026 economic environment, these mechanisms have evolved into the “twin pillars” of a unified strategy. By integrating an engineering-based Understanding Cost Segregation study into the exchange process, investors move beyond simple tax deferral into active cash flow generation.
This shift is critical for long-term growth. In 2026, the permanent restoration of 100% bonus depreciation under the One Big Beautiful Bill Act has changed the math for every major transaction. Investors no longer just wait for a property to grow in value. They use a wealth preservation tax strategy to unlock liquidity the moment they close on a replacement property. This synergy ensures that the equity moved from one asset to another isn't just sitting idle. It's actively shielding income from taxation at the highest levels of precision.
Defining the Core Objectives
The primary goal of this combined approach is to eliminate tax leakage during the transition between assets. While Section 1031 allows you to defer capital gains and depreciation recapture, it doesn't create new deductions. That's where the combination of cost segregation and 1031 exchange steps in. By reclassifying building components into shorter recovery periods under IRC Section 1245, we create immediate liquidity that offsets taxable income. Our strategy focuses on three technical goals:
- Deferral: Use Section 1031 to push capital gains and recapture liabilities into the future.
- Acceleration: Use cost segregation to pull future depreciation deductions into the current tax year.
- Compliance: Bridge these distinct tax codes through a licensed engineering firm to ensure the results withstand IRS scrutiny.
The Challenge-Solution-Outcome Framework
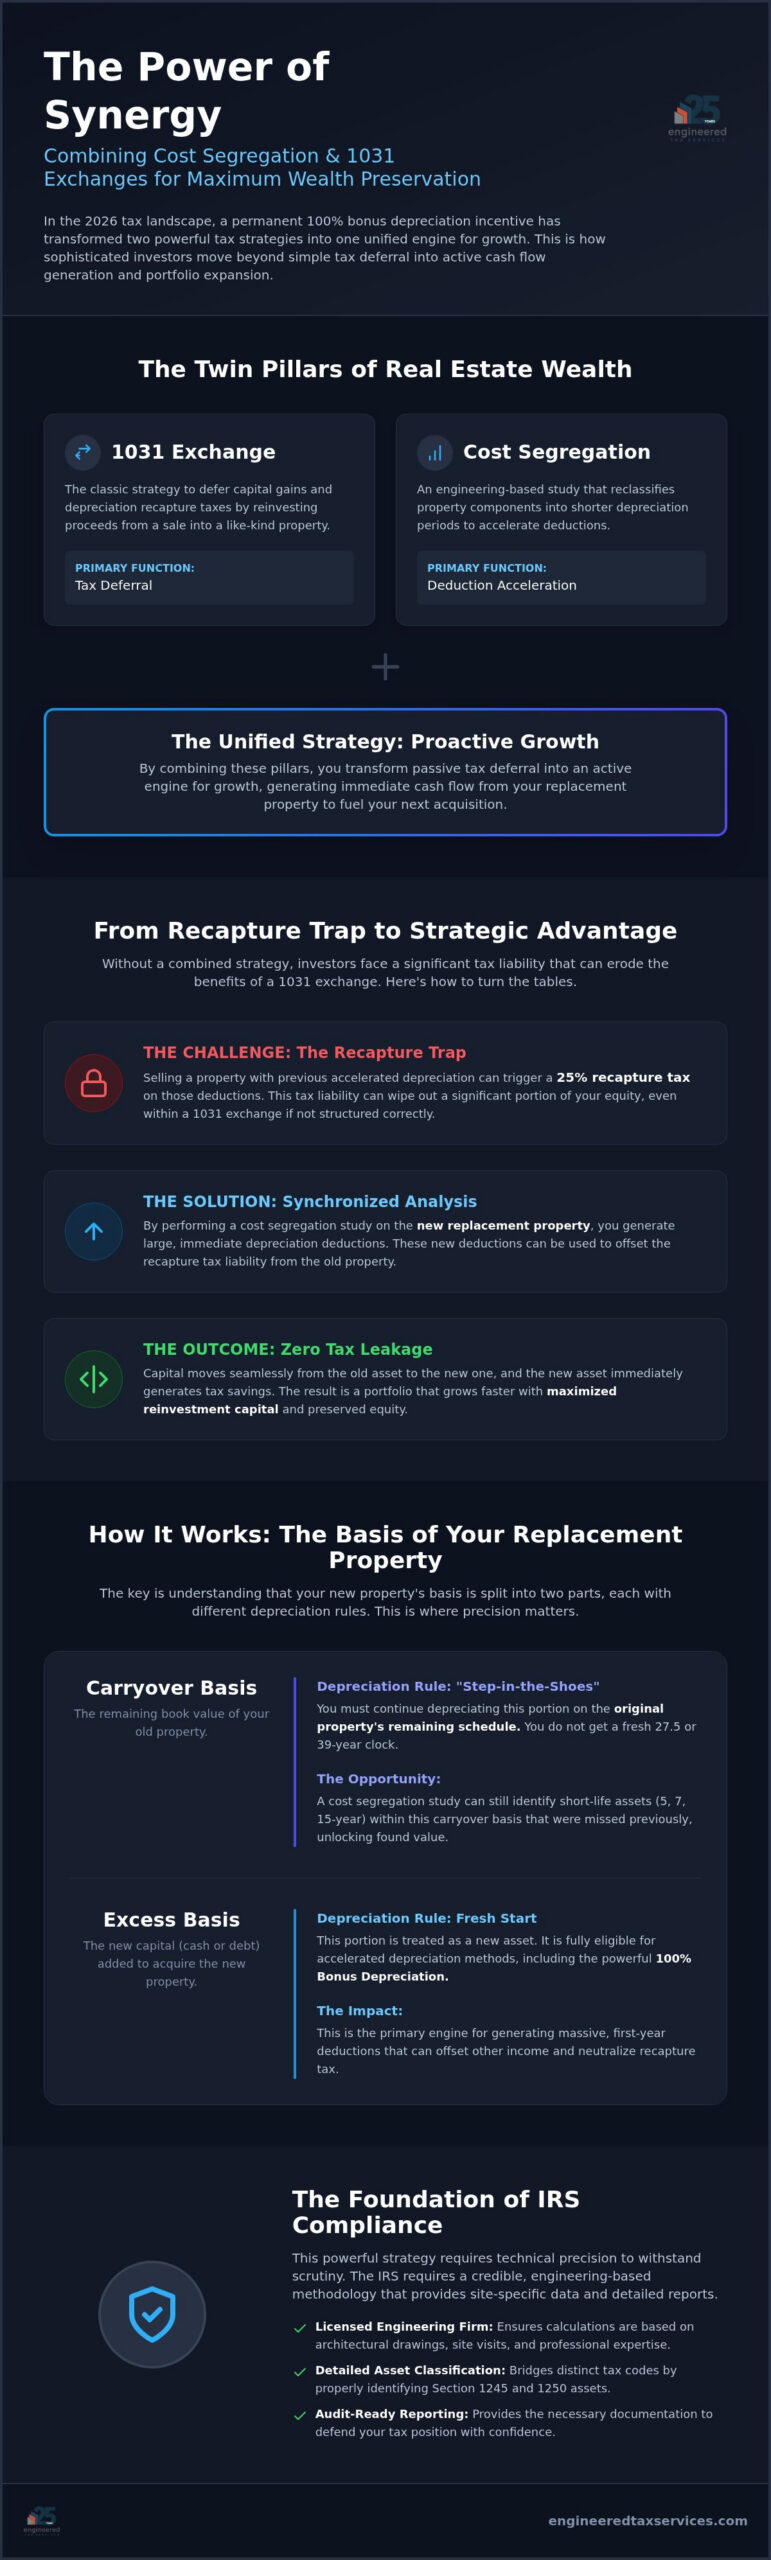
Most investors face the “Challenge” of locked-up equity and the looming threat of depreciation recapture. If you've previously used accelerated depreciation, selling that asset can trigger a 25% recapture tax that wipes out your 1031 benefits. The “Solution” is a synchronized cost segregation and 1031 exchange analysis. By trading into a higher-value replacement property and performing a study on the new asset, you can generate enough new depreciation to neutralize the recapture from the previous sale. The “Outcome” is a portfolio that grows with zero tax leakage. This methodology maximizes the reinvestment capital available for your next acquisition, keeping your wealth under your control rather than the government's.
Understanding Carryover Basis vs. Excess Basis
The tax basis of a replacement property is not a monolithic figure. Instead, the IRS mandates that investors divide their investment into two distinct buckets: carryover basis and excess basis. Precision here is mandatory because each bucket follows different depreciation rules. A strategic cost segregation and 1031 exchange analysis begins by disentangling these values to ensure every dollar of equity is working at its maximum efficiency. When you trade up into a larger asset, you aren't just moving money; you are managing two different tax lifecycles simultaneously.
Depreciating the Carryover Basis
The carryover basis represents the “old” money moving into the new deal. Carryover basis is the remaining book value of the relinquished property transferred to the new asset. Under the “step-in-the-shoes” rule, the IRS requires you to continue depreciating this portion as if you still owned the original property. You don't get to restart the 39-year clock on this amount. Instead, you maintain the remaining recovery period from the asset you sold.
However, this doesn't mean the carryover basis is devoid of opportunity. A professional engineering-based study identifies shorter-lived assets that were previously buried within the structural basis of the old property. By reclassifying these components into 5, 7, or 15-year categories, we can often accelerate deductions on the carryover portion that were previously overlooked. This ensures that even the “old” equity provides a modern cash flow benefit. If you aren't sure how your current basis is structured, you can request a preliminary basis analysis to see the potential savings.
Optimizing the Excess Basis
The excess basis is where the most significant tax-saving opportunities reside. This bucket consists of the new capital you've invested or the new debt you've taken on to acquire a more expensive replacement property. The IRS treats this portion as a brand-new asset placed in service on the date of acquisition. Because it's considered “new” to you, it opens the door for the most aggressive depreciation strategies available.
This portion is fully eligible for bonus depreciation commercial property. In the 2026 tax landscape, the bonus depreciation rate is set at 20%. While this is a step down from previous years, it still allows for a substantial first-year deduction on the excess basis. When combined with a cost segregation and 1031 exchange, this 20% incentive acts as a powerful shield against taxable income. By identifying the 5-year and 15-year property within that new investment, we can maximize your immediate liquidity and ensure that your expansion into a larger asset is supported by a robust tax-efficient foundation.
Navigating Depreciation Recapture and Compliance Risks
The “Recapture Trap” is a significant hurdle that often catches investors off guard during a disposition. When you perform a cost segregation study, you reclassify portions of your property as Section 1245 personal property to accelerate deductions. While this creates immediate cash flow, the IRS requires you to “recapture” those deductions as ordinary income when the asset is sold. If you aren't careful, the resulting tax bill can reach as high as 37%, effectively neutralizing the benefits of your earlier tax savings. This is where the strategic synchronization of a cost segregation and 1031 exchange becomes indispensable for wealth preservation.
A 1031 exchange allows you to defer both capital gains and depreciation recapture taxes, but it requires technical precision. To successfully defer Section 1245 recapture, you must ensure that the replacement property contains an equal or greater value of Section 1245 assets than the property you sold. If there's a shortfall in personal property value in the new acquisition, the IRS considers that difference to be “taxable boot.” Our role as your strategic partner is to identify these values before you close, ensuring your exchange is optimized to eliminate tax leakage.
Managing Section 1245 Property Requirements
Successful deferral depends on matching the “buckets” of your assets. You can't simply trade a cost-segregated apartment complex for a raw piece of land without triggering recapture because the land lacks the Section 1245 property needed to absorb the prior deductions. We work closely with your Qualified Intermediary to coordinate the timing and technical data needed for a seamless transition. A common mistake is assuming that a “like-kind” exchange only refers to the real estate itself. In reality, the IRS tracks the specific classifications of the assets within the building. By conducting a preliminary analysis of the replacement property, we help you avoid unintended liabilities and ensure you meet the equal-or-greater-value threshold.
IRS Audit Protection through Technical Precision
Compliance isn't just about following rules; it's about having the documentation to prove it. The IRS specifically looks for engineering-based reports to substantiate asset classifications in a cost segregation and 1031 exchange. “Rule of thumb” estimates or simple accounting allocations often fail under scrutiny because they lack the technical cost-estimating and site-specific data required by the IRS Cost Segregation Audit Techniques Guide. Every study we perform includes a robust defense file. As a licensed engineering firm, we provide the technical precision needed to defend your deductions. We stand behind our methodology, giving you the confidence to scale your portfolio while maintaining the highest standards of professional integrity.
Strategic Planning for 2026: The 20% Bonus Depreciation Era
As the Tax Cuts and Jobs Act (TCJA) phase-down reaches the 20% threshold in 2026, many investors mistakenly assume the era of aggressive tax planning has ended. This perspective ignores the fundamental “Time Value of Money” principle. In a 2026 environment characterized by sustained interest rates, the value of a dollar saved today significantly outweighs the promise of a deduction decades from now. Even at a 20% bonus rate, the combination of a cost segregation and 1031 exchange provides a vital liquidity injection that can be reinvested into higher-yielding assets or used to pay down expensive debt.
Beyond the immediate bonus deduction, cost segregation serves as a mechanism for generating passive losses. These losses can be used to offset income from other real estate holdings within your portfolio, creating a broader wealth preservation effect. By reclassifying building components, you aren't just shifting timing; you're actively managing your effective tax rate across your entire real estate enterprise. This strategic approach ensures that your capital remains deployed in your portfolio rather than being diverted to tax liabilities.
The Shift to MACRS Permanent Savings
The real power of cost segregation in 2026 lies in the permanent reclassification of assets into 5, 7, and 15-year recovery periods. While bonus depreciation provides a first-year “pop,” the underlying MACRS schedule offers a faster return of capital than the standard 39-year straight-line method. When you engage our 1031 exchange services, we synchronize the timing of your acquisition with these depreciation windows to maximize your 2026 benefits. This ensures that even without 100% bonus depreciation, your replacement property remains a high-performance tax shield.
Combining Cost Segregation with 179D and 45L
To bridge the gap created by the bonus phase-down, sophisticated investors are now “stacking” multiple incentives. By integrating the 179D energy efficient commercial building deduction with your cost segregation study, you can unlock significant first-year relief based on energy performance. For multifamily developers, adding 45L tax credits further enhances the ROI. This multi-incentive approach transforms a standard transaction into an engineered financial outcome, ensuring that every efficiency, both structural and fiscal, is captured and utilized. To see how these incentives can be stacked for your specific property, schedule a technical consultation with our engineering team.
The ETS Engineering-Based Approach to 1031 Optimization
While many tax professionals treat a cost segregation and 1031 exchange as a simple accounting entry, our approach recognizes it as a precision engineering challenge. A standard CPA firm might lack the technical expertise to deconstruct a complex commercial building into its individual components. By contrast, a licensed engineering firm possesses the architectural and construction knowledge required to identify assets that are often hidden within the structural shell. This distinction is critical for maintaining IRS compliance and maximizing the cash flow potential of your replacement property during the 2026 tax year.
Our methodology focuses on total integration. We don't operate in a vacuum; instead, we act as a strategic partner to your existing tax professional and Qualified Intermediary. By providing the technical data they need to calculate basis accurately and manage potential boot, we ensure your entire exchange remains a closed loop of tax deferral. This professional coordination is what separates a standard filing from a wealth-optimization strategy that truly preserves your reinvestment capital.
Technical Precision for High-Value Assets
Identifying Section 1245 assets requires more than a review of closing statements; it demands a forensic analysis of the property's physical systems. From specialized electrical feeds and process piping to decorative finishes and complex HVAC configurations, our engineers pinpoint every eligible component. With over 10,000 studies performed annually, ETS brings unparalleled institutional knowledge to every project, regardless of asset class. ETS utilizes a proprietary engineering-based methodology to ensure every study meets the highest IRS standards. This level of technical deconstruction ensures that your cost segregation and 1031 exchange results are both aggressive in their savings and conservative in their commitment to professional integrity.
Your Path to Capital Preservation
Scaling your portfolio in a higher-interest-rate environment requires a methodical path to liquidity. We follow a structured process designed to provide you with peace of mind through every phase of the acquisition. Our three-step framework includes:
- Step 1: Complimentary Feasibility Analysis: We evaluate your potential transaction to determine if the tax benefits of the study justify the investment before you commit.
- Step 2: Engineering Site Visit: Our team conducts a detailed on-site inspection and technical cost estimation to substantiate every asset classification with site-specific data.
- Step 3: Delivery of Certified Tax Study: You receive a comprehensive, engineered report ready for your 2026 filing, complete with a robust defense file.
Don't let tax leakage diminish the growth of your portfolio. Contact Engineered Tax Services today for your preliminary 1031 analysis and ensure your next transition is optimized for long-term stability.
Securing Long-Term Growth Through Strategic Tax Engineering
The 2026 tax landscape presents a unique set of challenges; however, it also offers significant opportunities for those who approach property transitions with technical precision. By integrating a cost segregation and 1031 exchange, you transform a standard transaction into a sophisticated wealth preservation event. This strategy ensures that your capital isn't just deferred, but actively optimized to support your next acquisition. Success in this environment requires mastering the nuances of basis allocation and anticipating the impact of the 20% bonus depreciation threshold.
Effective execution depends on more than just accounting entries. It requires the forensic detail of an engineering-based methodology to navigate recapture risks and basis complexities. As a licensed engineering firm that performs 10,000+ studies annually, we provide the institutional knowledge and IRS-compliant methodologies needed to protect your investments. It's time to move beyond simple compliance and embrace a proactive stance on your financial health. We are ready to act as your strategic partner in this complex discipline.
Optimize Your 1031 Exchange with an ETS Cost Segregation Study to ensure your portfolio remains a powerful engine for growth in the years ahead. Your journey toward maximized tax efficiency starts with a partner who understands the intersection of engineering and tax law.
Frequently Asked Questions
Can I do a cost segregation study on a property I've owned for years through a 1031 exchange?
Yes, you can perform a “look-back” study on a property acquired through a prior 1031 exchange. This allows you to catch up on missed depreciation deductions from previous years without filing an amended return. You use Form 3115 to claim the cumulative adjustment in the current tax year. It's a powerful way to inject liquidity into an existing portfolio while ensuring your historical basis is fully optimized for 2026.
Does cost segregation trigger depreciation recapture during a 1031 exchange?
No, performing a study itself doesn't trigger recapture; however, selling a property that has been cost-segregated can. A 1031 exchange allows you to defer this recapture as long as you trade into a property with equal or greater value in Section 1245 assets. Strategic coordination between your cost segregation and 1031 exchange is essential to ensure these liabilities are successfully pushed into the future.
What is the 2026 bonus depreciation rate for commercial property?
The bonus depreciation rate for qualifying commercial property in 2026 is 20%. This follows the scheduled phase-down established by the Tax Cuts and Jobs Act. While this is lower than the 100% rate seen in previous years, it still provides a significant first-year deduction on the excess basis of a replacement property. It remains a vital tool for investors looking to maximize their immediate cash flow.
How do carryover basis and excess basis differ in a 1031 exchange?
Carryover basis is the remaining book value from your old property that “steps into the shoes” of the new asset, continuing its original depreciation schedule. Excess basis is the new capital or debt added to acquire the replacement property. Only the excess basis is treated as a new asset and is eligible for 20% bonus depreciation in 2026. Understanding this split is critical for accurate tax planning.
Is a cost segregation study worth it if my bonus depreciation is only 20%?
Yes, cost segregation remains highly valuable because it reclassifies assets into shorter MACRS recovery periods like 5, 7, and 15 years. Even without bonus depreciation, shifting deductions from a 39-year schedule to a 5-year schedule significantly increases your net present value. In a higher-interest-rate environment, the time value of money makes these early deductions more impactful for reinvestment and capital preservation.
What happens if the replacement property has less personal property than the relinquished property?
If the replacement property has a lower value of Section 1245 assets than the property you sold, you may trigger “taxable boot.” This difference is recognized as ordinary income and is subject to depreciation recapture taxes. We work to identify these potential shortfalls during the identification period, allowing you to adjust your acquisition strategy or plan for the resulting tax liability before closing the deal.
Do I need an engineering firm or just a CPA for a cost segregation study?
The IRS specifically highlights that engineering-based studies are the most reliable method for substantiating asset classifications in a cost segregation and 1031 exchange. While a CPA handles the tax filings, they often lack the technical expertise to perform the required cost-estimating and site inspections. As a licensed engineering firm, we provide the technical precision and robust defense files necessary to withstand rigorous IRS scrutiny.
How long does a typical engineering-based cost segregation study take?
A comprehensive engineering-based study typically takes four to six weeks to complete from the date of the site visit. This timeline includes a detailed inspection, technical cost estimating, and the final report generation. Because 1031 exchange deadlines are strict, we recommend engaging our team as early as possible in the acquisition process to ensure your study is ready for your next tax filing.